
By Dr. Pellumb Kabashi, DBA, MBA, CES, CFE, EA
Founder, Tax Expert Today LLC · Tax advisors, enrolled agents, CPAs, and attorneys · Serving clients in all 50 states
Quick Answer: The Rhode Island estate tax applies to net taxable estates above $1,838,056 for 2026 deaths, and it is not a cliff. After a genuine move to Florida, Rhode Island taxes only real estate and tangible property located there, but the tax is computed on the whole estate and then multiplied by the Rhode Island share. Call (239) 441-2005 for a free consultation.
What Is the Rhode Island Estate Tax in 2026?
The Rhode Island estate tax is a state death tax on the transfer of a decedent’s net estate. For 2026 deaths, the Division of Taxation sets a credit of $87,940, which shelters the first $1,838,056 of net taxable estate. Above that line, rates begin at 7.2 percent and reach 16 percent.
The tax is imposed by R.I. Gen. Laws §44-22-1.1 on “every resident or nonresident decedent.” The second half of that phrase is the reason this tax follows people to Naples. A family that sells the Providence house and moves to Florida can leave the tax behind almost entirely. A family that keeps the Newport house, the Block Island cottage or a Rhode Island rental cannot, because Rhode Island keeps a claim on the property that remains physically inside the state.
- 2026 credit: $87,940, for decedents dying on or after January 1, 2026.
- 2026 threshold: $1,838,056 of net taxable estate, up from $1,802,431 for 2025 deaths.
- Effective starting rate: 7.2 percent on the first dollar above the line.
- Highest rate: 16 percent on net taxable estate above $10,100,000.
- Due date: nine months after the date of death.
The credit and threshold come from Division of Taxation Advisory 2025-27, published on December 30, 2025, and reported that day by a long-running Rhode Island tax news service. The same $1,838,056 figure appears in the Tax Foundation’s state table as of October 1, 2026, which also records that Rhode Island reform proposals introduced in the 2025 to 2026 session were not adopted. The credit and the threshold can be reconciled against each other: running $1,838,056 through the statutory schedule produces $87,940, which is exactly the credit.
Rhode Island has one of the lowest thresholds in the country, which is why the tax reaches families who would never think of themselves as wealthy. A paid-off house, a retirement account and a life insurance policy can pass $1,838,056 quickly. The federal exclusion for the same year is $15,000,000, according to the IRS estate tax page, so most estates that owe Rhode Island tax owe no federal estate tax at all.
Is the Rhode Island Estate Tax a Cliff?
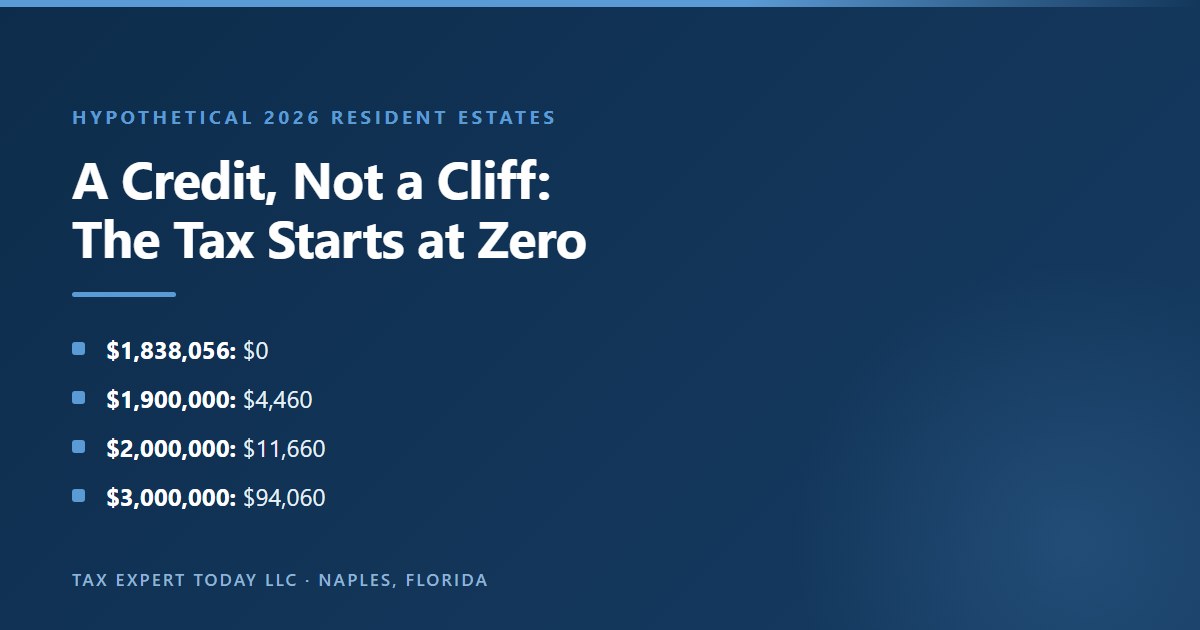
No. Rhode Island estate tax has not been a cliff since 2015. The tax equals a schedule amount minus a fixed credit, so at the $1,838,056 line the two offset exactly and the tax is zero. One dollar above the line produces about seven cents of tax, not a sudden bill on the whole estate.
This is the most widely repeated misunderstanding about the tax, and it has a real origin. Before 2015 the statute worked differently. Under subsection (a)(3), for deaths from 2010 through 2014, the tax was imposed “only if the net taxable estate” exceeded an indexed amount that started at $850,000. An estate under the line paid nothing, and an estate slightly over it paid tax computed from the bottom of the schedule. That was a true cliff.
The General Assembly replaced that design in 2014. Under subsection (a)(4), for deaths on or after January 1, 2015, the condition is gone. The tax is now the schedule amount, and “a Rhode Island credit shall be allowed against any tax so determined.” A credit that is subtracted from the schedule produces a smooth start. Older articles, and some newer ones that copied them, still describe the former rule.
| Net taxable estate (2026 death, resident) | Schedule amount | Less 2026 credit | Rhode Island estate tax | Effective rate on the whole estate |
|---|---|---|---|---|
| $1,838,056 | $87,940 | $87,940 | $0 | 0.00 percent |
| $1,900,000 | $92,400 | $87,940 | $4,460 | 0.23 percent |
| $2,000,000 | $99,600 | $87,940 | $11,660 | 0.58 percent |
| $2,500,000 | $138,800 | $87,940 | $50,860 | 2.03 percent |
| $3,000,000 | $182,000 | $87,940 | $94,060 | 3.14 percent |
| $5,000,000 | $391,600 | $87,940 | $303,660 | 6.07 percent |
| $8,000,000 | $773,200 | $87,940 | $685,260 | 8.57 percent |
| $10,000,000 | $1,067,600 | $87,940 | $979,660 | 9.80 percent |
| $15,000,000 | $1,866,800 | $87,940 | $1,778,860 | 11.86 percent |
| $20,000,000 | $2,666,800 | $87,940 | $2,578,860 | 12.89 percent |
All figures in this guide are hypothetical illustrations of how the statute computes, with no deductions unless stated. Actual results depend on the facts, on final federal values and on the credit in effect for the year of death.
The contrast with a real cliff is instructive. New York’s estate tax does take away the exclusion once a taxable estate passes 105 percent of the basic exclusion amount, and that design is covered in our guide to the New York estate tax cliff. Rhode Island works the way Massachusetts estate tax has worked since 2023: a fixed credit against the old federal table. A planner who treats Rhode Island as a cliff may push for a deduction or a gift to get “under the line” when the actual saving is a modest percentage of the amount moved.
How Is the Rhode Island Estate Tax Calculated Step by Step?
Rhode Island starts with the net taxable estate, subtracts $60,000 to reach the adjusted taxable estate, applies the federal credit table frozen as of January 1, 2001, and subtracts the indexed Rhode Island credit. A nonresident then multiplies the result by the Rhode Island share of the gross estate.
The statute borrows its rate schedule from federal law that no longer exists. The tax is “a sum equal to the maximum credit for state death taxes allowed by 26 U.S.C. §2011, as it was in effect as of January 1, 2001.” That federal section was phased out for later deaths, but the 2001 text remains available, and its table is what Rhode Island still applies.
- Determine the net taxable estate. Generally the federal gross estate less the federal deductions, using values “as finally determined for federal estate tax purposes” under subsection (d).
- Subtract $60,000. The 2001 version of §2011(b)(3) defines the adjusted taxable estate as the taxable estate reduced by $60,000.
- Apply the table. The table is expressed as a base amount plus a percentage of the excess over a bracket floor.
- Subtract the credit. For 2026 deaths, $87,940. If the result is negative, the tax is zero.
- Apply the fraction, if any property is outside Rhode Island. Subsection (b) reduces the tax for property with a tax situs outside the state.
A worked example shows how little arithmetic is involved. Take a resident with a net taxable estate of $3,000,000. Subtracting $60,000 leaves an adjusted taxable estate of $2,940,000. That amount falls in the bracket that begins at $2,540,000, where the 2001 table charges $146,800 plus 8.8 percent of the excess over the floor. The excess is $400,000, and 8.8 percent of it is $35,200, so the schedule amount is $182,000. Subtracting the $87,940 credit leaves $94,060.
The $60,000 subtraction is easy to miss, and leaving it out moves every bracket boundary. Some published tables state their brackets in adjusted taxable estate terms and others in net taxable estate terms, which is why the highest rate is described in one source as starting above $10,040,000 and in another as starting above $10,100,000. Both are correct on their own terms: $10,040,000 of adjusted taxable estate is $10,100,000 of net taxable estate.
The starting number is also larger than many people expect, because the gross estate is a federal concept that reaches well beyond what passes under a will.
- Retirement accounts: the full balance is generally included, even though a beneficiary will also owe income tax on withdrawals.
- Life insurance: proceeds are included if the decedent held incidents of ownership at death, which is the problem an irrevocable life insurance trust is built to solve.
- Jointly held property: spouses are generally treated as owning half each, while property held with a child can be included in full unless the survivor contributed to it.
- Revocable trust assets: included in full, because the power to revoke keeps them in the gross estate.
What Are the Real Rhode Island Rates Above the Threshold?
Above the threshold, Rhode Island’s marginal rates begin at 7.2 percent and rise in steps to 16 percent above $10,100,000 of net taxable estate. Published ranges of 0.8 percent to 16 percent describe the frozen table, but the credit absorbs the lower bands, so no estate actually pays the lowest rates.
State comparison charts list Rhode Island at 0.8 to 16 percent because the 2001 table begins at 0.8 percent. That is accurate about the table and misleading about the tax. The credit removes everything up to the threshold, and the threshold sits inside the 7.2 percent bracket. The first taxable dollar is therefore taxed at 7.2 percent, not 0.8 percent.
| Net taxable estate over | But not over | Marginal Rhode Island rate |
|---|---|---|
| $1,838,056 | $2,100,000 | 7.2 percent |
| $2,100,000 | $2,600,000 | 8.0 percent |
| $2,600,000 | $3,100,000 | 8.8 percent |
| $3,100,000 | $3,600,000 | 9.6 percent |
| $3,600,000 | $4,100,000 | 10.4 percent |
| $4,100,000 | $5,100,000 | 11.2 percent |
| $5,100,000 | $6,100,000 | 12.0 percent |
| $6,100,000 | $7,100,000 | 12.8 percent |
| $7,100,000 | $8,100,000 | 13.6 percent |
| $8,100,000 | $9,100,000 | 14.4 percent |
| $9,100,000 | $10,100,000 | 15.2 percent |
| $10,100,000 | No limit | 16.0 percent |
Two planning conclusions follow from this table.
- Deductions are worth their marginal rate: a $100,000 charitable bequest from a $5,000,000 Rhode Island estate saves about $11,200, not the full amount of any supposed cliff.
- Effective rates climb slowly: even a $20,000,000 resident estate pays an effective rate near 12.9 percent, below the marginal rate.
- Bracket boundaries are not traps: crossing from one band to the next changes the rate only on the dollars above the boundary.
Why Does the Rhode Island Threshold Change Every January?
The Rhode Island credit is indexed by statute. Each January 1 it rises by the percentage increase in the Consumer Price Index for All Urban Consumers as of September 30 of the prior year, rounded up to the nearest five dollars. The threshold is the estate size at which the schedule equals that credit.
The statute started the credit at $64,400 for 2015 deaths, which corresponded to a $1,500,000 threshold. Subsection (a)(4) then requires annual compounding. What the General Assembly actually indexes is the credit, not the threshold, and the Division publishes both each December. The date of death controls, so the right figure is the one for the year the decedent died, not the year the return is filed.
| Year of death | Rhode Island credit | Threshold of net taxable estate |
|---|---|---|
| 2015 (statutory starting point) | $64,400 | $1,500,000 |
| 2021 | Not restated here | $1,595,156 |
| 2022 | Not restated here | $1,648,611 |
| 2025 | $85,375 | $1,802,431 |
| 2026 | $87,940 | $1,838,056 |
The 2021 and 2022 thresholds are drawn from a PKF O’Connor Davies summary of the Division’s filing changes. Many pages still quote an older number, so anyone reading about this tax should check the year attached to the figure. The 2027 credit will be set by the same formula and is normally announced near the end of the year. Because the rate schedule itself is frozen, only the credit moves, and a family’s exposure changes each year mostly because asset values change faster than the credit does.
Does Rhode Island Tax You After You Move to Florida?
Rhode Island can still tax a Florida domiciliary, but only on property with a Rhode Island tax situs. That means real estate and tangible personal property physically located in Rhode Island. Intangibles such as brokerage accounts, bank deposits and business interests are Rhode Island property only if the decedent was a Rhode Island resident.
Florida itself will not add a second layer. Article VII, Section 5 of the Florida Constitution prohibits a state income tax on natural persons and restricts death taxes, and Florida imposes no estate tax for current deaths, a point covered in our guide to Florida estate planning for new residents. The move changes the state that can claim the whole estate. It does not erase the claim of a state where property remains.
The statute divides the world in subsection (e). Property has a tax situs in Rhode Island “if it is real estate or tangible personal property and has actual situs within the state” or “if it is intangible personal property and the decedent was a resident.” For a person who has genuinely established domicile in Florida, only the first of those tests can apply. Our guide on how to establish Florida residency covers the steps that make the move real.
- Sold before death, proceeds in Florida: the Rhode Island house is gone, and with it the Rhode Island situs.
- House kept and owned at death: the house is Rhode Island property for a nonresident, whatever the rest of the estate looks like.
- Brokerage account at a Rhode Island firm: intangible, so outside Rhode Island for a Florida domiciliary even if the adviser is in Providence.
- Boat kept in Newport: tangible personal property with actual situs in Rhode Island, so it counts.
What Property Has a Rhode Island Tax Situs for a Florida Resident?
For a Florida domiciliary, Rhode Island property generally means land, houses, condominiums and commercial buildings in Rhode Island, plus tangible items kept there such as furniture, art, vehicles and boats. Stocks, bonds, bank accounts, life insurance and retirement accounts are intangibles and fall outside the Rhode Island numerator.
| Asset owned at death by a Florida domiciliary | Character under §44-22-1.1(e) | Counted as Rhode Island property? |
|---|---|---|
| House, condominium or land in Rhode Island | Real estate, actual situs in Rhode Island | Yes |
| Rental or commercial building in Rhode Island, owned outright | Real estate, actual situs in Rhode Island | Yes |
| Furniture, art and vehicles kept at the Rhode Island house | Tangible personal property, actual situs in Rhode Island | Yes |
| Boat moored in Newport at death | Tangible personal property, actual situs in Rhode Island | Generally yes |
| Brokerage, bank and money market accounts | Intangible personal property | No |
| Retirement accounts and annuities | Intangible personal property | No |
| Life insurance included in the gross estate | Intangible personal property | No |
| Interest in an LLC or partnership that owns Rhode Island real estate | Generally intangible on the statutory text, but see the LLC section below | Requires analysis |
| Florida home and Florida tangibles | Situs outside Rhode Island | No |
The tangible property rule is easy to overlook. The furniture left in a summer house, the car kept in the garage and the painting that never moved south all have a physical location at death. A Rhode Island boat worth $150,000 in a $9,000,000 estate would add roughly $13,835 of Rhode Island tax on its own under the fraction described below, because the tax on the whole estate is large and the boat’s share of it is real.
A move of tangibles is simple when it is a real move. Art that actually hangs in Naples has a Florida situs. Art that is shipped to Florida on paper and stays in Jamestown does not. The same discipline that supports a domicile change, covered in our guide to the Florida residency audit, applies to the location of valuable things.
How Does the Rhode Island Nonresident Fraction Work?
A nonresident’s Rhode Island estate tax equals the tax computed as if the entire estate were taxable, multiplied by a fraction. The numerator is the gross estate excluding property with a tax situs outside Rhode Island. The denominator is the entire gross estate. Deductions do not enter the fraction at all.
Subsection (b) supplies the rule: “the tax determined by this section is reduced to an amount determined by multiplying the tax by a fraction whose numerator is the gross estate excluding all property having a tax situs not within the state at the decedent’s death and whose denominator is the gross estate.” For a Florida domiciliary, the numerator is, in practice, the value of the Rhode Island real and tangible property.
Consider a hypothetical Florida resident who dies in 2026 with an $8,000,000 estate, no deductions, including a Newport house worth $1,500,000.
| Step | Computation | Result |
|---|---|---|
| Net taxable estate | Whole estate, everywhere | $8,000,000 |
| Adjusted taxable estate | $8,000,000 less $60,000 | $7,940,000 |
| Schedule amount | $650,800 plus 13.6 percent of $900,000 | $773,200 |
| Less 2026 credit | $773,200 less $87,940 | $685,260 |
| Rhode Island fraction | $1,500,000 divided by $8,000,000 | 18.75 percent |
| Rhode Island estate tax | $685,260 times 18.75 percent | $128,486 |
The order of operations matters. The credit comes off first, on the whole estate, and only then does the fraction apply. A nonresident does not get a full $87,940 credit against the Rhode Island share. The credit is effectively prorated along with the tax, which is consistent with the statute’s wording that “the tax determined by this section” is what gets reduced.
The same order also explains why a modest estate can owe nothing. A Florida resident with a total estate of $1,800,000, including a Rhode Island house worth $1,200,000, is below the line on the whole estate. The tax computed on the whole estate is zero, and any fraction of zero is zero. Our guide on nonresident state tax returns covers the separate income tax side for owners of out-of-state property.
Getting the denominator right takes as much care as getting the numerator right, because an understated denominator overstates the Rhode Island share.
- Worldwide assets: the denominator is the entire gross estate, including the Florida home and accounts held anywhere.
- Gross, not net: the denominator is measured before deductions, so a large marital or charitable bequest does not alter it.
- Same valuation date: the numerator and denominator should use the same values reported for the estate.
- Documented values: an appraisal of the Rhode Island property is the figure most likely to be questioned, because it drives the numerator directly.
Why Does a Florida Portfolio Raise the Tax on a Rhode Island House?
The Rhode Island schedule is applied to the whole estate, so assets Rhode Island cannot tax still push the estate into higher brackets. Those assets shrink the fraction, but the rising rate more than offsets it. The same Rhode Island house therefore produces more tax as the owner’s Florida wealth grows.
This is the mechanism that surprises Florida movers most. The house has not changed. Its share of the estate has fallen. Yet the bill goes up, because the rate applied to that share is higher.
| Whole estate, Florida domiciliary, no deductions | Tax on whole estate | Rhode Island fraction for a $900,000 Block Island cottage | Rhode Island estate tax |
|---|---|---|---|
| $1,800,000 | $0 | 50.00 percent | $0 |
| $2,000,000 | $11,660 | 45.00 percent | $5,247 |
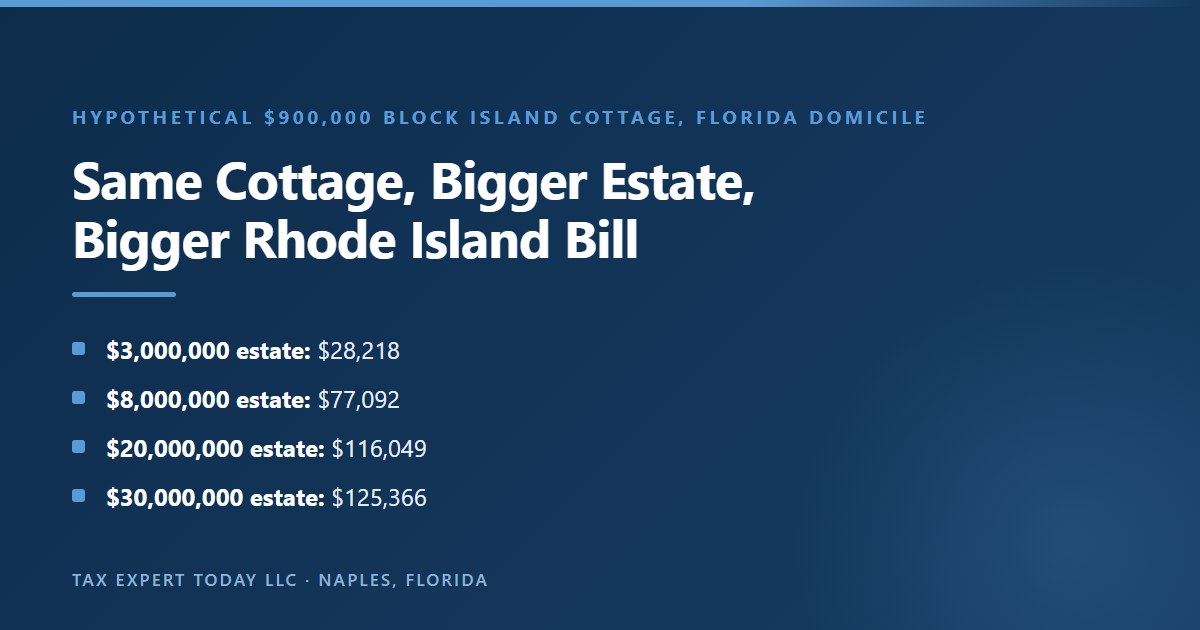
| $3,000,000 | $94,060 | 30.00 percent | $28,218 |
| $5,000,000 | $303,660 | 18.00 percent | $54,659 |
| $8,000,000 | $685,260 | 11.25 percent | $77,092 |
| $12,000,000 | $1,298,860 | 7.50 percent | $97,415 |
| $20,000,000 | $2,578,860 | 4.50 percent | $116,049 |
| $30,000,000 | $4,178,860 | 3.00 percent | $125,366 |
Stated plainly, the cottage is taxed at an effective rate of about 6.1 percent in a $5,000,000 estate and about 13.9 percent in a $30,000,000 estate. The nonresident owner is paying Rhode Island’s average rate on the whole estate, applied to the value of the Rhode Island property.
The same pattern appears in the other states with a nonresident fraction, as our guides to the Vermont estate tax, Maine estate tax and Minnesota estate tax explain. Rhode Island is unusual because its threshold is so low that the pattern begins with estates of ordinary size.
- Appreciation counts twice: growth in the Rhode Island house raises the numerator, and growth anywhere raises the rate applied.
- Spending counts too: a Florida retiree who spends down a portfolio lowers the rate applied to the house, an effect that is rarely modeled.
- Review the numbers periodically: a plan built on 2026 values may not describe an estate ten years later.
How Do Deductions and Mortgages Affect the Rhode Island Fraction?
Deductions lower the tax computed on the whole estate, but they do not change the fraction. Rhode Island’s statute says that in determining the fraction no deductions are considered, and the gross estate is not reduced by a mortgage or other debt for which the estate is not liable. A mortgage does not shrink the Rhode Island numerator.
Many owners assume that the $500,000 mortgage on the Rhode Island property reduces its Rhode Island value to the equity. For the fraction, the statute points the other way: “no deductions are considered and the gross estate is not reduced by a mortgage or other indebtedness for which the decedent’s estate is not liable.” Debt that is a true deduction can still reduce the net taxable estate, and through that the tax on the whole estate. The fraction stays where it was.
| Hypothetical Florida domiciliary, 2026 | Net taxable estate | Tax on whole estate | Fraction | Rhode Island estate tax |
|---|---|---|---|---|
| Gross $8,000,000, $1,500,000 house, no deductions | $8,000,000 | $685,260 | 18.75 percent | $128,486 |
| Same, with $500,000 of allowable deductions | $7,500,000 | $617,260 | 18.75 percent | $115,736 |
| Gross $10,000,000, $1,500,000 house, no deductions | $10,000,000 | $979,660 | 15.00 percent | $146,949 |
| Same, with a $1,000,000 charitable bequest | $9,000,000 | $828,460 | 15.00 percent | $124,269 |
In the charitable example, a $1,000,000 bequest saves $22,680 of Rhode Island tax. A charitable bequest under IRC §2055 reduces the tax on the whole estate but leaves the 15 percent fraction untouched. For a family that intends to give regardless, the saving is a benefit. It is not a reason to give on its own.
The federal deduction for state death taxes needs care too. The statute defines its terms by the Internal Revenue Code “as they were in effect as of January 1, 2001.” IRC §2058 was enacted later in 2001 and took effect for later deaths, so read literally it is not part of the Rhode Island base. It remains available on a federal return, which only matters for estates above the federal exclusion. A preparer should confirm the treatment against the current RI-706 instructions.
How Does Rhode Island Decide Whether You Are Still a Resident at Death?
The estate tax statute taxes resident and nonresident decedents differently but does not set a day count in §44-22-1.1. The question is generally domicile: where the decedent truly made a permanent home, based on conduct and intent. Rhode Island’s income tax has a separate 183 day rule, which is a different test.
The two tests are frequently confused. Rhode Island’s income tax residency rule, R.I. Gen. Laws §44-30-5, treats a person as a resident if domiciled in the state, or if the person maintains a permanent place of abode there and spends more than 183 days in the state during the year. A person could fail the income tax test for a single year and still have a Florida domicile for estate tax purposes, because statutory residency does not change domicile. Our Florida 183 day rule calculator helps track the days.
That income tax section contains a detail worth knowing. In determining domicile for income tax purposes, the location of professional advisors, including those who provide medical, financial, legal, insurance, fiduciary or investment services, and charitable contributions to Rhode Island organizations, “shall not be taken into consideration.” A Florida mover who keeps a Providence accountant is not, on that basis alone, undermining the income tax position. The provision is in the income tax chapter, so it should not be assumed to bind an estate tax examiner, but it shows how the state itself has framed the inquiry.
- Actions that support Florida domicile: a recorded declaration under Fla. Stat. §222.17, a Florida driver license, Florida voter registration and Florida homestead.
- Time and presence: where the person actually spends the year and where important events occur.
- Home comparison: size, use and contents of the Florida home against the Rhode Island home.
- Business and social ties: where the person works, belongs and is treated by others as being at home.
- Estate documents: wills and trusts that recite Florida domicile and name Florida fiduciaries.
Families who split the year between two states should also read our guide to the dual state residency trap and our piece on snowbird taxes in year one. Both explain why a move in name only rarely holds up.
What Happens if Rhode Island Challenges the Florida Domicile?
If Rhode Island successfully treats the decedent as a resident, intangible property regains a Rhode Island situs. The numerator then expands to include brokerage accounts and other intangibles, and only real and tangible property located in other states comes out. A small Rhode Island bill can become several times larger.
The exposure is easy to illustrate. Assume the same $8,000,000 estate with the $1,500,000 Newport house, a $1,200,000 Florida home and $5,300,000 of investments.
| Outcome | Rhode Island numerator | Fraction | Rhode Island estate tax |
|---|---|---|---|
| Florida domicile respected | $1,500,000 | 18.75 percent | $128,486 |
| Rhode Island domicile asserted successfully | $6,800,000 | 85.00 percent | $582,471 |
| No Florida home at all, every asset Rhode Island situs | $8,000,000 | 100.00 percent | $685,260 |
The difference between the first and second rows is $453,985. An estate tax dispute also arrives at the worst time: the person who could best explain the move has died, and the executor must reconstruct the facts from records. Statutes give the Tax Administrator authority to examine a statement considered “erroneous or incomplete” and to appraise the estate under R.I. Gen. Laws §44-23-5. The practical protection is an ordered file built while the person is alive, the same kind of file that supports a New York residency audit defense in the state next door.
- Keep dated records: calendars, travel records, medical appointments and phone data can establish where a person actually spent the year.
- Keep the story consistent: a Rhode Island voter registration or a Rhode Island return filed as a resident after the move can undercut the claim.
- Tell the executor where the file is: the record is of little use if nobody can find it after the death.
- Do not rely on the declaration alone: a Florida declaration of domicile is evidence of intent, and it carries more weight when the person’s conduct matches it.
Does Holding Rhode Island Property in an LLC or Trust Change the Result?
An LLC interest is generally intangible on the face of the statute, which points outside the Rhode Island numerator for a nonresident. That reading is not settled. A revocable trust usually does not change the result, because property in a revocable trust remains in the gross estate and keeps its physical situs.
The statutory text gives real estate and tangible property a situs by location, and gives intangible property a Rhode Island situs only for a resident. An LLC membership interest is ordinarily personal property of an intangible kind. On that basis, some advisers suggest holding Rhode Island real estate in an LLC to convert it into an intangible for a Florida owner.
Several reasons call for caution.
- No express statutory safe harbor: §44-22-1.1 does not address entities, and a Division position on a particular structure should be confirmed, not assumed.
- Substance concerns: a single member LLC holding a family’s vacation home, with no business purpose, invites the argument that the entity should be disregarded.
- Federal inclusion: a transferor who keeps the right to use the property may face inclusion under IRC §2036.
- Costs on the way in: deed transfers, title insurance, lender consent and local property tax consequences all need review.
- Income tax effects: the entity’s Rhode Island source income still has to be reported.
A family with a genuine operating rental, several owners and a real management reason for an entity is in a different position from a retiree transferring a vacation cottage shortly before death. In either case, the analysis should happen with Rhode Island counsel before a deed is signed. Revocable trusts solve a different problem: they can reduce the need for ancillary probate, but they do not remove property from the gross estate. Our guide to trust situs after moving to Florida covers how trust administration follows a move.
Trustees should also note an older procedural rule. R.I. Gen. Laws §44-23-2 calls for a sworn statement by certain trustees within 30 days after the death of the creator of a trust. How the Division applies that section today, particularly to a nonresident’s trust, is a question to raise with Rhode Island counsel early.
Can Selling or Giving Away the Rhode Island Home Reduce the Tax?
Yes, in many cases. A completed lifetime sale or gift generally removes the home from the Rhode Island numerator, and Rhode Island has no gift tax. The trade-offs are significant, though: a sale triggers capital gain that a step-up at death could have erased, and a gift carries over the original basis.
The most direct path is to stop owning Rhode Island property at death. Each route has a price, and the comparison below shows why the most obvious one is not automatically the most economical. Assume an $8,000,000 estate with a $1,500,000 house and a $500,000 tax basis, for a built-in gain of $1,000,000.
| Path | Rhode Island estate tax at death | Income tax effect | Key caution |
|---|---|---|---|
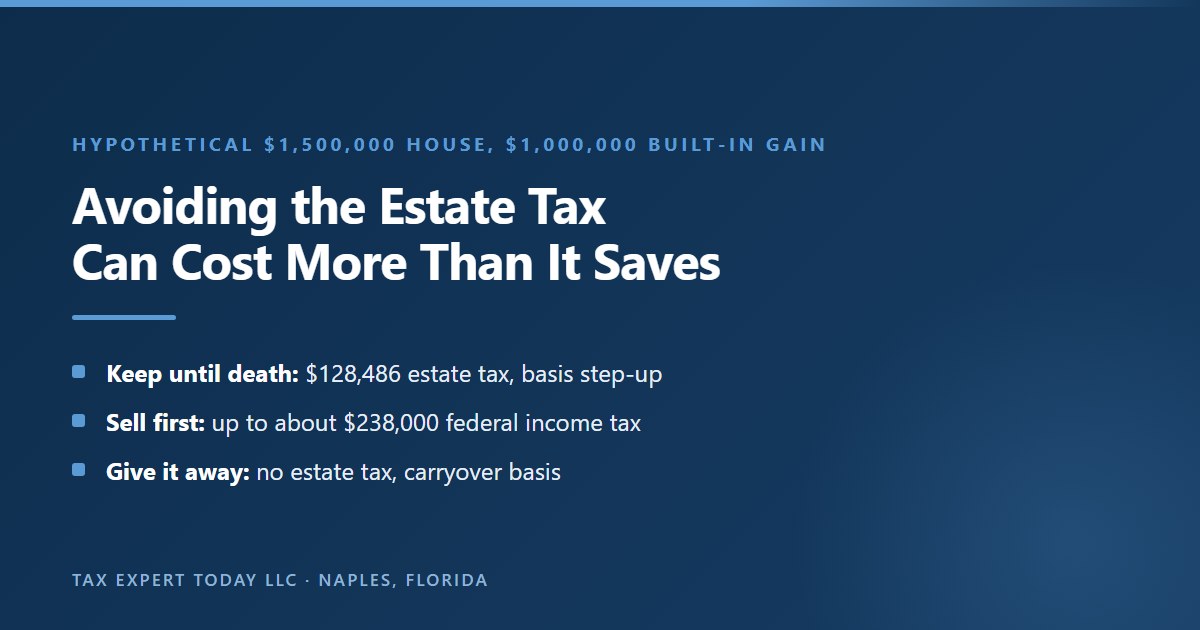
| Keep the house until death | $128,486 | Step-up under IRC §1014 can eliminate the gain | Lien and filing obligations fall on the family |
| Sell during life, proceeds held as intangibles | $0 | Up to about $238,000 of federal tax at 23.8 percent, before Rhode Island income tax on the gain | The income tax may exceed the estate tax saved |
| Give the house to children during life | $0 if fully out of the estate | Children take carryover basis and may pay the gain on a later sale | Retained use risks inclusion under IRC §2036 |
| Transfer to a qualified personal residence trust | $0 if the grantor survives the term | Carryover basis for the remainder beneficiaries | Death during the term generally brings the property back |
The sale column is often the surprise. Paying up to $238,000 of federal income tax to avoid $128,486 of estate tax is a poor exchange, unless the family wants to sell anyway. The basis step-up in IRC §1014 is frequently worth more than the Rhode Island tax it would be traded against. An owner-occupant may qualify for the principal residence exclusion, and our guide to selling your home after moving to Florida explains how that window closes after a move. Owners of rentals should see our piece on selling rental property after moving.
The gift route has its own mechanics. A qualified personal residence trust is one structured approach, and gifts of larger amounts use the federal lifetime gift tax exemption. In every version, the owner has to actually give up the property. A deed to the children, followed by continued free use of the home for life, is the kind of arrangement that invites inclusion anyway.
Before choosing a path, a family should be able to answer a short list of questions.
- Who wants the house? A property that no child intends to keep may be better sold at some point, after the basis result is compared.
- What is the basis? A long-held property with a low basis usually favors holding until death.
- Will the owner still use it? Continued use without paying fair rent is the point at which many transfers fail.
- How large is the whole estate? A small estate near the threshold may have little Rhode Island tax to save at all.
- What are the transfer costs? Deed taxes, title changes and insurance need to be compared with the expected saving.
Does Rhode Island Have a Gift Tax or Add Back Lifetime Gifts?
Rhode Island does not impose a separate gift tax. The tax base is the net taxable estate at death, and the frozen table uses the adjusted taxable estate without an add-back for lifetime taxable gifts. Gifts completed before death therefore generally reduce the Rhode Island computation, subject to federal inclusion rules.
The base in the statute is the taxable estate reduced by $60,000. Adjusted taxable gifts, which matter on a federal return, are not part of the 2001 §2011 table. That makes lifetime giving a useful lever in Rhode Island, in contrast with Vermont’s two year add-back described in our Vermont estate tax guide. Rules on gifts made near death under IRC §2035 can still pull certain property or gift tax amounts back into the federal gross estate, and the Rhode Island base follows those federal values.
Gifts of non-Rhode Island assets also change the arithmetic, in a way that needs modeling. Reducing the whole estate lowers the tax on the whole estate, but it also raises the fraction, because the Rhode Island house becomes a larger share of what is left.
| Hypothetical estate with a $1,500,000 Rhode Island house | Tax on whole estate | Fraction | Rhode Island estate tax |
|---|---|---|---|
| $8,000,000, no gifts | $685,260 | 18.75 percent | $128,486 |
| $6,000,000 after a $2,000,000 lifetime gift of securities | $422,860 | 25.00 percent | $105,715 |
| $6,500,000 after gifting only the Rhode Island house | $486,060 | 0.00 percent | $0 |
In the second row, a $2,000,000 gift of securities saves $22,771 of Rhode Island tax. In the third, a gift of the house alone eliminates the Rhode Island tax, because the numerator is zero, and it uses less of the family’s federal exemption than the $2,000,000 gift. The right choice depends on basis, on who will live in the property and on the family’s federal position. The federal annual exclusion remains $19,000 per recipient for 2026 under the IRS gift tax guidance. Our guides to the spousal lifetime access trust and the irrevocable life insurance trust cover two of the structures commonly used for larger transfers.
- Completed gifts only: a gift must actually leave the donor’s control to come out of the estate.
- Federal filing: gifts above the annual exclusion generally require Form 709, even when no federal gift tax is due.
- Basis follows the gift: a gift recipient generally takes the donor’s basis, so appreciated assets are often poor choices for giving.
- Gifts of cash or high-basis assets: these reduce the whole estate with less income tax cost to the recipient.
Can Married Couples Use Portability for the Rhode Island Estate Tax?
No. Rhode Island has no portability. The statute allows a flat credit for each estate, and federal portability was enacted long after the Code date Rhode Island uses. If the first spouse leaves everything outright to the survivor, that first spouse’s sheltered amount is lost for Rhode Island purposes.
Federal portability under IRC §2010(c) allows a surviving spouse to use a deceased spouse’s unused federal exclusion. Rhode Island’s statute refers to the Code as of January 1, 2001 and grants a dollar credit to each estate. Nothing in §44-22-1.1 transfers an unused credit from one spouse to the other. Couples who rely on federal portability alone can overpay at the state level.
A classic credit shelter design addresses this. At the first death, an amount up to the threshold passes to a trust that does not qualify for the marital deduction, and the rest passes to the survivor. What the trust holds matters a great deal for a Florida couple with Rhode Island property. Assume a married couple with $8,000,000 in total, a $1,500,000 Rhode Island house included, and no change in values.
| Plan at the first death (2026 values) | Rhode Island estate tax at the first death | Rhode Island estate tax at the second death |
|---|---|---|
| Everything outright to the survivor; survivor owns the house at death | $0 | $128,486 |
| $1,838,056 credit shelter trust funded with securities; survivor owns the house | $0 | $107,775 |
| $1,838,056 credit shelter trust that holds the house; survivor owns no Rhode Island property | $0 | $0 |
The third row depends on the house being available to fund the trust at the first death, which requires attention to how the couple holds title. Property held as tenants by the entirety passes automatically to the survivor and cannot fund a trust unless the title is changed first. It also assumes the trust is drafted so its assets stay out of the survivor’s gross estate, and it gives up the second basis step-up on the house. The illustration ignores appreciation and is a planning discussion, not a prediction.
Title is often where a good plan fails, because the way a couple holds the deed determines what is available to fund a trust.
- Tenancy by the entirety: the survivor takes the whole property by operation of law, and the will has no effect on it.
- Sole ownership by the first to die: the property can pass into a trust under the will or a revocable trust.
- Tenancy in common: each spouse’s share can pass separately, which creates flexibility and also requires coordinated documents.
- Disclaimers: a qualified disclaimer may allow a survivor to redirect property after the first death, within strict federal timing rules.
How Does the Marital Deduction Work on a Rhode Island Return?
Property passing to a surviving spouse in qualifying form is generally deductible, so a married decedent often owes no Rhode Island tax at the first death. The deduction defers the tax rather than eliminating it. The survivor’s estate then includes those assets, and Rhode Island applies its schedule at the second death.
The marital deduction in IRC §2056 carries into the Rhode Island computation because the state uses federal definitions, subject to the 2001 reference. A qualified terminable interest trust is a familiar way to provide for a spouse while controlling where the property goes afterward.
- State-only elections: whether a separate Rhode Island QTIP election is available when no federal return is required should be confirmed against the current RI-706 instructions before a plan relies on one.
- Non-citizen spouse: the federal marital deduction is limited absent a qualified domestic trust, and our guide to the nonresident alien spouse covers the related rules.
- Timing of the survivor’s move: a widowed spouse who later moves to Florida may be able to reduce the second-death exposure, because intangibles leave the numerator once domicile changes.
- Remarriage and title: a surviving spouse who adds a new spouse to the Rhode Island deed changes the analysis again.
How Does the Rhode Island Estate Tax Interact With the Federal Estate Tax?
The two taxes are computed separately. For 2026 deaths the federal basic exclusion amount is $15,000,000, so most estates subject to Rhode Island tax owe no federal estate tax. Rhode Island relies on federal definitions and final federal values, but its rate table and credit are its own and are unaffected by federal exclusion changes.
The statute anticipates this separation. It says that any scheduled increase in the unified credit “shall not apply,” which is why the rise in the federal exclusion to $15,000,000 did nothing to reduce the Rhode Island tax. It also explains the most common surprise in the estate tax conversation: a family with an $8,000,000 estate may have no federal estate tax to worry about and still have a real Rhode Island bill on a house there.
| Item | Federal estate tax, 2026 | Rhode Island estate tax, 2026 |
|---|---|---|
| Exclusion or threshold | $15,000,000 | $1,838,056 |
| Rate above the line | Up to 40 percent | 7.2 percent rising to 16 percent |
| Portability between spouses | Yes, by election | No |
| Tax on lifetime gifts | Unified with the estate tax | None |
| Inflation indexing | Exclusion indexed | Credit indexed |
| Return | Form 706, when required | Form RI-706 |
| Basic due date | Nine months after death | Nine months after death |
Values do link the two. Subsection (d) says that all values are “as finally determined for federal estate tax purposes.” When no federal return is required, the Rhode Island return still needs supportable date of death values, and a qualified appraisal of the house is usually the place to start. A federal Form 706 may still be worth filing voluntarily to make a portability election, since the federal benefit is not available without one.
- Estates under the federal line: the Rhode Island return may be the only estate tax return the family files, but it still rests on federal concepts.
- Estates over the federal line: both computations are required, and they use different schedules and credits.
- Federal law changes: because Rhode Island froze its reference date, a change in the federal exclusion will not automatically move the Rhode Island line.
When Is Rhode Island Estate Tax Due and What Happens If It Is Late?
Rhode Island estate tax is due nine months after the date of death, and the return is due on the same schedule. Interest runs from the due date whether or not an extension was granted, at no less than 12 percent annually since 2023. A late payment addition of 0.5 percent per month can apply, up to 25 percent.
R.I. Gen. Laws §44-23-1 requires every executor, administrator and heir-at-law to file a sworn statement within nine months after the death. Section 44-23-16 makes the tax due and payable at the same nine month point. Interest is set by R.I. Gen. Laws §44-1-7, computed each January as prime plus two percentage points, with a 12 percent floor and a 21 percent ceiling for periods on or after January 1, 2023. For deaths on or after January 1, 2025, the former $50 filing fee no longer applies.
| Event | Timing | Authority |
|---|---|---|
| Statement by certain trustees | Within 30 days after the creator’s death | §44-23-2 |
| Return (sworn statement) | Within nine months after death | §44-23-1 |
| Tax due and payable | Nine months after death | §44-23-16 |
| Extension of time to file | Corresponding to an approved federal Form 706 extension, on written application | §44-23-3 |
| Interest | From the due date, without regard to any extension | §44-23-16 and §44-1-7 |
| Late payment addition | 0.5 percent per month, up to 25 percent, absent reasonable cause | §44-23-16 |
| Hardship extension to pay | Up to four years, discretionary, with approval of the attorney general | §44-23-18 |
A hypothetical shows the cost of delay. On $100,000 of Rhode Island tax paid one year late with no extension, interest at the 12 percent floor would be at least $12,000, and the late payment addition could add a further $6,000. An extension to file does not extend the time to pay, so an estate that needs more time should make a payment by the nine month date.
- Tentative assessment: under §44-23-11, an executor may request a tentative assessment and pay it to prevent interest on that amount, with any difference reconciled later.
- Hardship: under §44-23-18, the Tax Administrator may extend payment for up to four years and allow installments, with or without interest, when payment would cause undue hardship.
- Contested claims: under §44-23-17, payment may be suspended, with approval, where funds must be held for a contested creditor claim.
Which Estates Must File Form RI-706?
Form RI-706 is the Rhode Island estate tax return for taxable and non-taxable estates of decedents dying after 2014. A Rhode Island return is generally needed whenever the decedent held Rhode Island property, even if no tax is due, because the filing supports the release of the Rhode Island estate tax lien.
The Division replaced Forms RI-100 and RI-100A with a single RI-706 starting in 2022, as reported at the time, and described the change as a matter of streamlining rather than a change in the law. The PKF O’Connor Davies summary indicates that smaller estates, below $1,300,000 at the time of that announcement, complete only part of the return, while larger estates complete the full form with schedules.
- Filing below the tax line: an estate between $1,300,000 and $1,838,056 can owe nothing and still have a full return to complete.
- Whole estate reporting: a Florida domiciliary’s return still needs values for the whole estate, because the tax and the fraction both depend on it.
- Federal attachment: where a federal Form 706 is filed, expect to provide it with the Rhode Island return.
- Current instructions: filing thresholds and page requirements are set in Division guidance and can change, so preparers should work from the current form.
The practical burden for a Florida family is that a modest Rhode Island property can require a full inventory of a Florida estate. It is sensible to assemble that inventory while the owner is alive.
How Does a Rhode Island Estate Tax Lien Affect a House Sale?
Rhode Island estate tax is a lien on the property transferred, and real estate can remain encumbered until the lien is discharged. A Florida family cannot usually deliver clean title on a Rhode Island house without a discharge from the Division of Taxation, even when no estate tax is actually owed.
Under R.I. Gen. Laws §44-23-13, taxes “are and remain a lien upon the property transferred,” and executors, administrators and trustees are “personally liable for any and all taxes until they are paid.” Section 44-23-12 provides for the lien to be noted in the land records where the real property is located. Section 44-23-14 allows discharge by payment of the tax due on a parcel, by transferring the lien to other real estate, or by acceptable surety, and it makes the heir or devisee personally liable for the tax on that real estate.
In practice, Rhode Island real estate professionals work with the Division’s lien discharge form, commonly identified as Form T-77, and an estate should allow time for it. The older section on securities transfers, §44-23-34, speaks to securities of a resident decedent, so it is less likely to matter to a genuine Florida domiciliary.
- Personal liability: a family member serving as Florida personal representative can have personal exposure in Rhode Island.
- Ancillary authority: a Florida representative commonly needs authority in Rhode Island to deal with the real estate, unless the property is held in a form that avoids probate there.
- Closing timeline: buyers, title companies and lenders will generally look for the discharge before closing.
- Debts of the devisee: the person inheriting the house can be asked to pay the tax on it, so the will’s tax apportionment clause deserves review.
Our guide to Florida asset protection for new residents covers how Florida’s homestead rules compare, and the two states’ rules should be read together when an estate holds homes in both.
How Does Rhode Island Compare With Other States Florida Movers Leave?
Rhode Island has the lowest threshold of the common Northeast corridor states, at $1,838,056 for 2026. Massachusetts follows at $2,000,000, while Maine, New York and Vermont set higher exclusions and Connecticut matches the federal amount. A Florida mover with property in any of them faces a similar nonresident analysis.
| State (2026 figures) | Estate tax threshold | Published rates | Our nonresident guide |
|---|---|---|---|
| Rhode Island | $1,838,056 | 0.8 to 16 percent on the table; 7.2 to 16 percent in effect | This guide |
| Massachusetts | $2,000,000 | 0.8 to 16 percent | Massachusetts |
| Minnesota | $3,000,000 | 13 to 16 percent | Minnesota |
| Maryland | $5,000,000 | 0.8 to 16 percent, plus an inheritance tax | Maryland |
| Vermont | $5,000,000 | 16 percent | Vermont |
| Maine | $7,160,000 | 8 to 12 percent | Maine |
| New York | $7,350,000 | 3.06 to 16 percent, with a cliff | New York |
| Connecticut | $15,000,000 | 12 percent | Connecticut |
Rates and thresholds in this table are from the Tax Foundation’s 2026 state survey, current as of October 1, 2026. A family with property in several of these states, such as a Rhode Island house and a Massachusetts condominium, may face a separate return and computation in each. Each state applies its own rules, and our guide to Florida wealth migration gives broader context for why these questions are becoming more common. Inheritance taxes are a separate category, as our guides to New Jersey inheritance tax and Pennsylvania inheritance tax explain.
- Do not add thresholds together: each state tests the estate under its own rules, and a low line in one state is not relieved by a high line in another.
- Whole estate in every state: most of these computations start from the whole estate, so a family with property in several states may pay on overlapping rate bases.
- Consolidating property: moving ownership of second homes into one state, or out of all of them, is a common planning conversation that deserves its own analysis.
What Do Rhode Island Movers Get Wrong About the Estate Tax?
The most common errors are assuming a cliff that no longer exists, assuming a move to Florida ends all Rhode Island exposure, measuring the tax against only the Rhode Island house, assuming a mortgage reduces the fraction, and leaving the Rhode Island return to chance because no tax appears to be due.
| Common belief | How the statute works |
|---|---|
| “One dollar over the threshold taxes the whole estate.” | That was the pre-2015 design. Today the credit produces a smooth start at 7.2 percent. |
| “I moved to Florida, so Rhode Island cannot touch me.” | Real estate and tangible property with Rhode Island situs remain subject to the fraction. |
| “The house is under the threshold, so no tax is due.” | The tax is computed on the whole estate, then apportioned. A $900,000 cottage can produce tax in a larger estate. |
| “The mortgage lowers the Rhode Island share.” | Subsection (b) says no deductions are considered in the fraction. |
| “The first spouse’s credit carries over.” | Rhode Island has no portability. |
| “No tax means no filing.” | A return is generally needed to clear the lien on Rhode Island real estate. |
| “The rate starts at 0.8 percent.” | The low table bands are absorbed by the credit. The first taxed dollar is at 7.2 percent. |
| “A sale before death is an easy fix.” | Sale can trigger more income tax than the estate tax it avoids. |
What Should a Rhode Island Mover Check Before and After the Move?
Before a move, map every asset by physical location, confirm how each Rhode Island property is titled, and model the fraction at current values. After the move, record the Florida domicile, relocate tangibles that are actually moving, and update wills, trusts and tax apportionment clauses so a future executor is not left guessing.
- Inventory: list real estate and valuable tangibles by state, and note how each is titled.
- Model: run the whole-estate computation at today’s values, then again with expected growth.
- Domicile file: record the Florida declaration of domicile, licenses, registrations and day counts.
- Documents: update wills, trusts, powers of attorney and health care documents under Florida law.
- Executor brief: tell the future representative about the Rhode Island lien, the nine month deadline and where the records are.
Business owners face further questions, because a Rhode Island company interest is treated differently from Rhode Island land. Our guides on moving to Florida before selling a business and Florida domicile for executives address timing around a liquidity event or deferred compensation, and retiring to Florida covers how pensions and retirement accounts are treated after the move.
Rhode Island Estate Tax Help in Naples & Southwest Florida
Tax Expert Today LLC works with families who have moved, or are moving, from Rhode Island to Naples, Florida and across Southwest Florida on the tax side of the relocation, including the estate tax Rhode Island can still apply to a house, a rental, a boat or the contents of a summer home. The firm is multidisciplinary, with enrolled agents, CPAs and attorneys, and it handles residency and tax matters nationwide, coordinating with Rhode Island and Florida estate counsel when documents need to change. Our office is at 11983 Tamiami Trail N, Naples, FL 34110, open Monday through Friday, 10 a.m. to 5 p.m. ET, and reachable at (239) 441-2005.
- Rhode Island estate tax help Naples: modeling of the Rhode Island fraction at current values for a house, cottage, rental or boat.
- Transfer and spouse planning: comparing a sale, a gift, a qualified personal residence trust and a credit shelter trust against the income tax cost of each.
- Domicile and filings: the residency record, the day count, and coordination of the RI-706 return and lien discharge for a Florida personal representative.
Our Naples tax planning practice and our Florida tax services page describe the wider planning work, and our estate and trust planning team handles the drafting side alongside your attorneys.
When to Engage a Professional
A Florida resident whose whole estate is comfortably under $1,838,056, or who owns nothing in Rhode Island, rarely needs Rhode Island estate tax advice beyond confirming that nothing has changed. Professional help earns its cost when the estate exceeds that line and includes a Rhode Island house, cottage, rental, commercial building or valuable tangibles; when a sale or gift of the property is being considered; when a spouse has died and the survivor holds the Rhode Island property; when an LLC or trust holds Rhode Island property among several relatives; or when a personal representative needs to file an RI-706 and clear a lien. It is also worth a conversation when the move itself is recent and the domicile record is still being built, because that record decides whether Rhode Island taxes a share of the estate or nearly all of it. Tax Expert Today LLC’s enrolled agents, CPAs and attorneys can model the computation, coordinate with counsel in both states, and help document the change of domicile. Call (239) 441-2005 to schedule a consultation.
Frequently Asked Questions
What is the Rhode Island estate tax threshold for 2026?
For decedents dying on or after January 1, 2026, the Rhode Island credit is $87,940, which corresponds to a net taxable estate of $1,838,056. The figure is indexed each January, so the year of death determines which amount applies.
Is the Rhode Island estate tax a cliff?
No. Since 2015 the tax has been computed as a schedule amount minus a fixed credit. An estate at the threshold owes nothing, and the first dollar above it is taxed at 7.2 percent. The cliff in Rhode Island law applied to deaths before 2015.
Does Rhode Island tax a Florida resident on a Rhode Island house?
Yes, if the whole estate is large enough to produce a tax. A nonresident’s Rhode Island tax is the tax on the whole estate multiplied by the Rhode Island share of the gross estate. Brokerage accounts and other intangibles are outside that share for a genuine Florida domiciliary.
Does Rhode Island have portability for married couples?
No. The statute allows a credit for each estate and does not let a survivor use a deceased spouse’s unused amount. Couples who want to use both credits generally plan through a credit shelter trust, with attention to which assets fund it.
When is a Rhode Island estate tax return due?
The return and the tax are both due nine months after the date of death under R.I. Gen. Laws sections 44-23-1 and 44-23-16. An extension to file does not stop interest, which has run at no less than 12 percent per year since 2023.
Can a Naples, Florida firm help with a Rhode Island estate tax filing?
Yes. A Naples, Florida tax firm can model the Rhode Island computation, gather the whole estate inventory and coordinate with Rhode Island counsel on the return, the lien discharge and any ancillary probate. Tax Expert Today LLC can be reached at (239) 441-2005.
Published November 8, 2026 by Dr. Pellumb Kabashi « Back to Learning Center
Have a question this article touches on?
Tax Expert Today LLC, based in Naples, Florida and serving clients across the United States.
Schedule a Consultation (239) 441-2005