
By Dr. Pellumb Kabashi, DBA, MBA, CES, CFE, EA
Founder, Tax Expert Today LLC · Tax advisors, enrolled agents, CPAs, and attorneys · Serving clients in all 50 states
Quick Answer: The SEP IRA contribution deadline for 2026 is the business return due date, including extensions: March 15, 2027 for S corporations and partnerships, or September 15, 2027 if extended, and April 15, 2027 for sole proprietors, or October 15, 2027 if extended. The extension must actually be filed, and an IRA deadline does not move. Call (239) 441-2005 for a free consultation.
What is the SEP IRA contribution deadline?
The SEP IRA contribution deadline is the due date of the employer’s federal income tax return for the year, including extensions. For the 2026 tax year that means March 15, 2027 for S corporations and partnerships and April 15, 2027 for sole proprietors and calendar year C corporations, or later with a valid extension.
- Statute: IRC section 404(h)(1)(B) treats a contribution as made for the year if it is made by the return due date, including extensions.
- Plan setup: a SEP for 2026 can also be adopted as late as that same extended due date.
- Extension effect: an extension that was actually obtained moves the deposit date, even if the return is filed earlier.
- Missed date: a deposit after the deadline counts for the following year instead.
The rule comes from IRC section 404(h)(1)(B), which treats employer contributions to a simplified employee pension as made for a taxable year when they are made on account of that year and are made no later than the time prescribed by law for filing the return for that year, including extensions. The IRS repeats the rule on its SEP plan page and in its SEP frequently asked questions, where it states that contributions for a year must be deposited by the due date, including extensions, for filing the federal income tax return for that year.
Owners searching for the SEP IRA contribution deadline usually want one date. The honest answer is that there is a different date for each kind of business, and a second date for each kind of business that files an extension. A sole proprietor and an S corporation owner who sit next to each other at the same seminar can have deadlines six months apart. This guide lays out every one of those dates for the 2026 tax year, shows how the extension actually works, and explains the custodian paperwork that decides whether a late deposit lands in the right year.
This guide is written for self-employed owners, single member LLC owners, partners, and S corporation shareholders who fund their own retirement through the business. It is part of the planning material used by our Naples, Florida tax planning team, and our tax planning services page describes the broader work. All dollar examples are hypothetical.
| Business type | Return | Deadline without extension | Deadline with a valid extension |
|---|---|---|---|
| Sole proprietor or single member LLC | Form 1040 with Schedule C | Thursday, April 15, 2027 | Friday, October 15, 2027 |
| S corporation | Form 1120-S | Monday, March 15, 2027 | Wednesday, September 15, 2027 |
| Partnership or multi member LLC | Form 1065 | Monday, March 15, 2027 | Wednesday, September 15, 2027 |
| C corporation | Form 1120 | Thursday, April 15, 2027 | Friday, October 15, 2027 |
| Authority | IRC 404(h)(1)(B) | IRS SEP FAQ | Publication 560 |
What are the exact 2026 tax year SEP deadlines for each business type?
For a calendar year business, the 2026 SEP deadlines are March 15, 2027 for S corporations and partnerships, extended to September 15, 2027, and April 15, 2027 for sole proprietors and C corporations, extended to October 15, 2027. None of these dates falls on a weekend, so no weekend shift applies for 2027.
- S corporation and partnership: Monday, March 15, 2027, or Wednesday, September 15, 2027 with Form 7004.
- Sole proprietor: Thursday, April 15, 2027, or Friday, October 15, 2027 with Form 4868.
- C corporation, calendar year: Thursday, April 15, 2027, or Friday, October 15, 2027 with Form 7004.
- Fiscal year business: the dates follow that entity’s own return due date.
The weekday matters because IRC section 7503 moves a deadline that falls on a Saturday, Sunday, or legal holiday to the next business day. For the 2026 tax year, each of the four standard dates lands on a weekday, so the printed date is the real date. Owners who remember a deadline from a prior year, when a date slid to a Monday, should not assume the same slide applies again.
The extensions come from two different forms. A business return uses Form 7004, which grants an automatic extension of time to file. An individual return uses Form 4868. Each form extends only the return it covers. A Form 4868 filed by an S corporation owner extends the owner’s personal return and does nothing for the S corporation’s SEP deadline, which is tied to Form 1120-S.
Fiscal year businesses follow the same logic on a different calendar. The deadline is the due date of the return for the fiscal year in which the contribution is deducted, plus any extension obtained for that return. A business on a fiscal year should compute its own dates rather than rely on the calendar year table.
| Event | Date | Weekday | Applies to |
|---|---|---|---|
| Last day of the 2026 tax year | December 31, 2026 | Thursday | All calendar year businesses |
| Unextended deadline, pass-through entities | March 15, 2027 | Monday | S corporations and partnerships |
| Unextended deadline, individuals and C corporations | April 15, 2027 | Thursday | Sole proprietors and C corporations |
| Extended deadline, pass-through entities | September 15, 2027 | Wednesday | S corporations and partnerships with Form 7004 |
| Extended deadline, individuals and C corporations | October 15, 2027 | Friday | Sole proprietors with Form 4868, C corporations with Form 7004 |
Does the tax extension actually have to be filed to use the later SEP deadline?
Yes. The IRS states that if you did not request an extension and did not deposit the SEP contribution by the original filing due date, you cannot deduct it on that year’s return. An owner who plans to fund after March 15 or April 15 needs a timely extension on file for the business return that controls the deadline.
- IRS position: no extension requested and no deposit by the original date means no deduction for that year.
- What saves it: a valid extension filed by the original due date.
- Which form: the extension for the return tied to the deduction, not the owner’s personal return in every case.
- Fallback: the late contribution may be deducted on the following year’s return.
The IRS SEP frequently asked questions address this directly. The IRS writes that if you did not request an extension to file your tax return and did not deposit the SEP plan contributions by the filing due date for that return, you are not allowed to deduct any SEP plan contributions on that year’s return, and that the contributions may be deducted on the following year’s return. The statute reaches the same place, because section 404(h)(1)(B) refers to the time prescribed for filing the return including extensions, and an extension that was never requested does not extend anything.
Many of the pages that rank for this topic describe the October 15 date as if it were automatic. It is automatic only in the sense that the extension request itself is automatic once filed. The request still has to be made on time. An owner who misses March 15 or April 15 without an extension cannot recover the prior year deduction by depositing in May.
The extension only extends time to file, not time to pay. An owner who files Form 4868 to keep the SEP window open still owes any balance due by April 15, and interest and a late payment penalty can apply to unpaid tax. Our guide to tax extension payment options explains how that balance is handled while the return is still open.
| Facts | Deposit date | Extension filed by April 15, 2027? | Year the deduction generally belongs to |
|---|---|---|---|
| Funds before the original date | April 1, 2027 | Not needed | 2026 |
| Files Form 4868, funds in summer | July 20, 2027 | Yes | 2026 |
| Files Form 4868, funds at the end | October 15, 2027 | Yes | 2026 |
| No extension, funds in May | May 10, 2027 | No | 2027, not 2026 |
| Extension filed late, funds in June | June 1, 2027 | No valid extension | Generally 2027, not 2026 |
Can I file my return early and still make the SEP contribution later?
Generally yes, if a valid extension was obtained. The IRS says that once you obtain an extension, you have until the end of the extension period to deposit the contribution, regardless of when you actually file the return. The return must still claim the deduction, which means the planned amount is reported before the cash is deposited.
- IRS language: the deposit window runs to the end of the extension period regardless of the filing date.
- Reporting: the return claims the deduction for an amount that has not yet been deposited.
- Risk: if the deposit never happens, the return overstates the deduction and needs correction.
- Practical use: an owner can file in April and fund from summer cash flow.
This is one of the most useful and least discussed parts of the rule. The IRS SEP FAQ states that if you obtain an extension for filing your tax return, you have until the end of that extension period to deposit the contribution, regardless of when you actually file the return. An owner can therefore file Form 4868 in April, file the completed return in May, and deposit the SEP contribution in September, as long as the deposit is made before the extended due date.
The approach carries a discipline problem. The return reports a deduction that is still only a promise. If the business has a weak summer and the deposit is never made, the return claimed a deduction it was not entitled to, and the IRS FAQ says an improperly deducted SEP contribution requires an amended return. A preparer will usually want written confirmation of the planned amount, and many prefer to file after the deposit clears for that reason.
The same timing question applies to the self-employment math. A SEP deduction does not reduce self-employment tax, so the Schedule SE figures do not change, but income tax does change. Our self-employment tax calculator shows the self-employment tax side on its own.
| Step | Date | What happens | Status of the deduction |
|---|---|---|---|
| Extension filed | April 12, 2027 | Form 4868 filed and estimated balance paid | Window open to October 15, 2027 |
| Return filed | May 20, 2027 | Return claims a $33,457 SEP deduction | Claimed, not yet funded |
| Deposit made | September 8, 2027 | $33,457 deposited and designated for 2026 | Funded within the window |
| Form 5498 issued | By May 31, 2028 | Custodian reports the 2027 deposit | Reported in the deposit year |
| If no deposit by October 15, 2027 | October 16, 2027 | Deduction was overstated | Amended return generally needed |
What happens if a SEP contribution misses the deadline?
A SEP contribution deposited after the deadline, including any extension, is not deductible for the earlier year. The IRS says it may be deducted on the following year’s return instead. It also counts toward that following year’s limit, so a late deposit can crowd out part of the next year’s planned contribution for the same person.
- Deduction year: the late deposit moves to the year in which it was deposited.
- Limit effect: it uses part of the following year’s $72,000 or 25 percent ceiling.
- Employee effect: a late deposit for staff still has to satisfy the plan’s uniform allocation rules.
- Correction: an improper deduction on the earlier return requires an amended return.
The IRS FAQ language is plain: contributions not deposited by the filing due date may be deducted on the following year’s return. That follows from section 404(h)(1)(A), which deducts SEP contributions in the taxable year with or within which the calendar year for which they are made ends, and from subsection (h)(1)(B), which supplies the grace period. Once the grace period passes, the money is simply a contribution for the year in which it was deposited.
The practical cost is that the late deposit competes with the next year. An owner who deposits $40,000 in November 2027, meaning it for 2026, has made a 2027 contribution of $40,000 in the eyes of the deduction rules. If the same owner then plans another full contribution for 2027, the combined amount can exceed the 2027 limit. The excess becomes a problem that is covered later in this guide.
A missed deadline is also a signal to review the plan calendar. Owners who miss the SEP date often miss the quarterly estimated tax dates for the same reason, which is that the business has no fixed year end routine. A short written calendar, built around the business’s own return due date, avoids both.
| Deposit date | Within the 2026 window? | Deduction year | Effect on the 2027 limit |
|---|---|---|---|
| March 30, 2027 | Yes | 2026 | None |
| October 14, 2027 | Yes | 2026 | None |
| October 18, 2027 | No | 2027 | Uses $40,000 of the 2027 limit |
| January 5, 2028 | No | Could be designated for 2027 if within the 2027 window | Counts for 2027 if so designated |
| Never deposited | Not applicable | No deduction | None |
What is the deadline to set up a SEP IRA plan for 2026?
A SEP for 2026 can be set up as late as the due date of the business’s 2026 income tax return, including extensions. The IRS states this on its SEP plan page and in Publication 560. Adopting the plan document and opening the account are separate steps, and both have to be complete before the contribution can be deposited.
- Plan document: Form 5305-SEP, a pre-approved prototype, or an individually designed SEP.
- Account: a SEP IRA opened for each eligible person, including the owner.
- Filing: Form 5305-SEP is kept in the business records and is not filed with the IRS.
- Same window: setup and funding both run to the extended due date.
The IRS SEP plan page states that you can set up a SEP for a year as late as the due date, including extensions, of your business income tax return for the year you want to establish the plan, and Publication 560 says the same thing. This is very different from a 401(k) plan, where elective deferrals generally require a plan in place before the year ends, with a narrow exception for new sole proprietor plans discussed later.
The plan document is usually the model Form 5305-SEP, which the instructions say is not filed with the IRS. The employer signs it, gives each eligible employee a copy with the required information, and keeps it. The form cannot be used by an employer that already maintains another qualified retirement plan, and in that case a prototype or individually designed SEP is needed. An owner who already has a profit sharing plan or a safe harbor 401(k) should review the combination before adopting a SEP.
The account step is where late adoptions usually stall. Custodians need identity verification, beneficiary forms, and sometimes a waiting period before money can move. An owner who decides on October 12 to adopt and fund a SEP by October 15 is taking a real risk that the account will not be open in time.
| Step | Who does it | Latest date for 2026 | Authority |
|---|---|---|---|
| Sign the plan document | Employer | October 15, 2027 | IRS SEP page |
| Give eligible employees the plan information | Employer | When the plan is adopted | Form 5305-SEP instructions |
| Open a SEP IRA for each eligible person | Employee or employer with the custodian | Before the deposit | Publication 560 |
| Deposit the contribution | Employer | October 15, 2027 | IRC 404(h)(1)(B) |
| Claim the deduction | Owner on the return | On the 2026 return | Publication 560 |
How do I tell the custodian that a deposit is for the prior year?
Tell the custodian in writing, on its contribution form or online screen, that the deposit is a SEP employer contribution for the 2026 tax year. Custodians report SEP deposits by the year received, but the business needs a record showing the year for which each deposit was made, because that record supports the deduction on the return.
- Contribution type: employer SEP contribution, not a traditional IRA contribution by the owner.
- Tax year: the year for which the contribution is made, here 2026.
- Record: keep the confirmation with the business return workpapers.
- Separate deposits: one deposit per tax year avoids allocation questions.
Custodian screens often default to the current year or to an individual IRA contribution. A SEP deposit entered as a regular traditional IRA contribution can be capped at the $7,500 IRA limit for 2026, coded under the wrong rules, or rejected. The owner, or the bookkeeper making the transfer, should select the employer SEP option and the prior tax year if the screen offers one, and keep a copy of the confirmation.
The record matters more for a SEP than for an ordinary IRA because the custodian’s own tax reporting will not show the tax year. The deduction rests on the business’s records and the timing rule in section 404(h)(1)(B). An owner who deposits in March 2027 without any note may later struggle to show that the deposit was meant for 2026 rather than 2027, particularly if a second deposit for 2027 follows in December.
A short written memo works well. It should state the employer, the plan, the contribution amount, the tax year, the deposit date, and the employees who received contributions, with the uniform percentage used. That memo also helps if a later review asks whether each eligible employee received the same percentage.
| Field | Example entry |
|---|---|
| Employer | Hypothetical Design Studio LLC, sole proprietor |
| Plan | SEP adopted on Form 5305-SEP |
| Tax year of contribution | 2026 |
| Deposit date | March 30, 2027 |
| Amount | $33,457 to the owner’s SEP IRA |
| Contribution rate | 25 percent plan rate, 20 percent effective rate for the owner |
| Extension status | Not needed, deposited before April 15, 2027 |
Why does Form 5498 show the SEP contribution in the wrong year?
Form 5498 reports SEP contributions in the calendar year they are deposited, not the year they are for. The IRS explains that this is required regardless of the year for which the contribution is made. A 2026 contribution deposited in March 2027 therefore appears on the 2027 Form 5498, and that is correct rather than an error.
- Reporting year: the year the custodian received the money.
- Deduction year: the year for which the contribution was made and timely deposited.
- Common mismatch: a March deposit for the prior year appears on the next year’s form.
- No correction needed: the custodian is following the reporting rule.
The IRS SEP FAQ answers this exact question. It asks why last year’s contribution that was made this year is shown on this year’s Form 5498, and the IRS answer is that contributions to a SEP IRA must be reported on the Form 5498 for the year they are actually deposited, regardless of the year for which they are made. This is different from regular traditional and Roth IRA contributions made between January 1 and April 15, which custodians report for the prior year when the owner designates them that way.
The mismatch confuses owners and sometimes software. An owner who reads a 2027 Form 5498 showing a SEP contribution may think the contribution belongs to 2027 and try to deduct it again. A preparer who sees the 2026 deduction but no matching 2026 form may ask for proof. The deposit memo described above answers both questions. The Form 5498 page at the IRS lists the current instructions for custodians.
Because the form is not the source of the deduction, owners should not wait for it. The return is filed from the business’s records of what was deposited and when, and the Form 5498 that arrives in May of the following year is a later confirmation, not a prerequisite.
| Deposit date | Tax year of the contribution | Form 5498 year | Return that claims the deduction |
|---|---|---|---|
| December 15, 2026 | 2026 | 2026 | 2026 return |
| March 30, 2027 | 2026 | 2027 | 2026 return |
| October 14, 2027, with extension | 2026 | 2027 | 2026 return |
| December 20, 2027 | 2027 | 2027 | 2027 return |
| February 10, 2028 | 2027 | 2028 | 2027 return |
Is the SEP contribution 20 percent or 25 percent?
Both numbers are right for different people. An employer can contribute up to 25 percent of an employee’s compensation. A self-employed owner’s own maximum works out to 20 percent of net earnings after the half self-employment tax deduction, because the contribution reduces the compensation it is measured against. Publication 560 has the conversion table.
- Common law employees: up to 25 percent of W-2 compensation.
- S corporation owner: up to 25 percent of W-2 wages from the S corporation.
- Sole proprietor or partner: effectively 20 percent of net earnings from self-employment.
- Ceiling for 2026: $72,000 per person, with compensation capped at $360,000.
The 25 percent figure comes from section 404(h)(1)(C), which limits the deduction to 25 percent of the compensation paid to employees, and from the annual additions limit in section 415(c). For a self-employed person, compensation means net earnings from self-employment reduced by the deduction for one half of self-employment tax and by the SEP contribution itself. That circular definition is why Publication 560 provides a rate table for the self-employed, and the table converts a 25 percent plan rate to a 20 percent rate applied before the contribution is subtracted.
The arithmetic is simple once it is written out. If C is the contribution and N is net earnings after the half self-employment tax deduction, the rule says C equals 25 percent of N minus C. Solving gives C equal to N times 0.25 divided by 1.25, which is 20 percent of N. The same shortcut applies to any plan rate: a 10 percent plan rate becomes about 9.09 percent, and a 15 percent plan rate becomes about 13.04 percent.
S corporation owners do not use the rate table. They are employees of their corporation, so their contribution is up to 25 percent of the W-2 wages the corporation paid them, as discussed below.
| Plan contribution rate | Self-employed rate applied to net earnings | Hypothetical net earnings of $100,000 | Resulting owner contribution |
|---|---|---|---|
| 5 percent | 4.7619 percent | $100,000 | $4,762 |
| 10 percent | 9.0909 percent | $100,000 | $9,091 |
| 15 percent | 13.0435 percent | $100,000 | $13,043 |
| 20 percent | 16.6667 percent | $100,000 | $16,667 |
| 25 percent | 20.0000 percent | $100,000 | $20,000 |
How is a sole proprietor’s maximum SEP contribution calculated step by step?
Start with net profit, compute self-employment tax on 92.35 percent of it, subtract half of that tax to reach net earnings, and multiply by 20 percent. For a hypothetical sole proprietor with $180,000 of 2026 net profit, that produces a maximum SEP contribution of about $33,457, which fits easily under the $72,000 limit.
- Step 1: net profit from Schedule C, here $180,000.
- Step 2: self-employment tax on 92.35 percent of profit, here about $25,433.
- Step 3: subtract half of that tax, here about $12,717, leaving about $167,283.
- Step 4: multiply by 20 percent, giving about $33,457.
The computation follows IRC section 1402(a)(12), which allows the 92.35 percent factor, and the 2026 Social Security wage base of $184,500 confirmed on IRS Topic 751. Social Security tax at 12.4 percent applies to the first $184,500 of net earnings from self-employment, and Medicare tax at 2.9 percent applies to all of it. The additional 0.9 percent Medicare tax is not part of the deductible half and is ignored here.
The table below shows each line for the hypothetical owner. The figures are rounded to whole dollars. A real computation also accounts for other wages the owner earned, which share the Social Security wage base, and for losses from other businesses, which can reduce net earnings. Publication 560 contains the official worksheet.
The same owner could contribute considerably more through a solo 401(k), because the employee deferral sits on top of the 20 percent employer amount. Our comparison of the SEP IRA vs solo 401k works that choice through at many income levels, and this guide limits itself to the deadlines that apply to each.
| Line | Computation | Amount |
|---|---|---|
| Net profit | From Schedule C | $180,000 |
| Net earnings subject to SE tax | $180,000 times 92.35 percent | $166,230 |
| Social Security portion | 12.4 percent of $166,230 | $20,613 |
| Medicare portion | 2.9 percent of $166,230 | $4,821 |
| Self-employment tax | Sum of the two | $25,433 |
| Deduction for half of SE tax | $25,433 divided by 2 | $12,717 |
| Net earnings for the SEP | $180,000 minus $12,717 | $167,283 |
| Maximum SEP contribution | 20 percent of $167,283 | $33,457 |
How much can an S corporation owner contribute to a SEP IRA?
An S corporation owner can receive a SEP contribution of up to 25 percent of the W-2 wages the corporation paid them for the year, capped at $72,000 for 2026. Shareholder distributions and K-1 income do not count. A hypothetical owner paid $120,000 of wages for 2026 could receive up to $30,000, deposited by the corporation’s deadline.
- Compensation base: Form W-2 wages from the S corporation for 2026.
- Rate: up to 25 percent, applied uniformly to all eligible employees.
- Deadline: the Form 1120-S due date, March 15, 2027, or September 15, 2027 with an extension.
- Wages to reach $72,000: $288,000 of W-2 pay.
An S corporation shareholder who works in the business is an employee of the corporation, so the SEP contribution is an employer contribution measured against W-2 wages, under section 404(h)(1)(C). The corporation deducts it on line 17 of Form 1120-S, according to the Form 1120-S instructions, and it flows through to the shareholders as a reduction of ordinary business income rather than as a deduction on the owner’s personal return.
The deadline that matters is the corporation’s, not the owner’s. The owner’s personal extension to October 15 does not reach the SEP. An S corporation owner who first thinks about the SEP while preparing a personal return in April has already passed March 15, and if the corporation did not file Form 7004 by March 15, the 2026 window has closed.
The wage level that drives the contribution is set by December 31, because wages for 2026 have to be paid in 2026. That makes the reasonable compensation decision and the SEP decision the same decision, made before year end. Our guide to S corporation reasonable compensation explains how that salary figure is supported.
| 2026 W-2 wages | 25 percent of wages | SEP maximum | Deadline without extension | Deadline with Form 7004 |
|---|---|---|---|---|
| $60,000 | $15,000 | $15,000 | March 15, 2027 | September 15, 2027 |
| $80,000 | $20,000 | $20,000 | March 15, 2027 | September 15, 2027 |
| $100,000 | $25,000 | $25,000 | March 15, 2027 | September 15, 2027 |
| $120,000 | $30,000 | $30,000 | March 15, 2027 | September 15, 2027 |
| $150,000 | $37,500 | $37,500 | March 15, 2027 | September 15, 2027 |
| $288,000 | $72,000 | $72,000 | March 15, 2027 | September 15, 2027 |
Why does K-1 income not count toward an S corporation owner’s SEP?
SEP contributions are measured against compensation, and S corporation distributions and the shareholder’s share of ordinary business income are not compensation. Only W-2 wages count. A hypothetical owner with $120,000 of wages and $150,000 of K-1 income has a SEP base of $120,000, not $270,000, and raising it requires wages paid during 2026.
- Counts: W-2 wages paid by the S corporation during the year.
- Does not count: Schedule K-1 ordinary income and cash distributions.
- Timing: wages for 2026 cannot be added after December 31, 2026.
- Trade-off: higher wages raise payroll tax as well as the SEP base.
The difference between an S corporation and a sole proprietorship is the reason. A sole proprietor’s net earnings from self-employment include all business profit, so the profit is the base. An S corporation shareholder has no self-employment income from the corporation. The shareholder’s share of profit passes through on Schedule K-1 and is not earned income for retirement plan purposes, so it cannot support a SEP contribution.
Owners who learn this in March are often surprised that nothing can be done for the prior year. The corporation cannot issue a corrected W-2 to increase 2026 wages that were never paid in 2026. The planning point is earlier: if the owner wants a larger 2026 SEP contribution, the corporation has to pay the larger salary through payroll before the year closes, with the matching payroll taxes.
The same rule shapes the qualified business income deduction in the other direction, because W-2 wages paid by the corporation can matter for the wage limitation that applies to higher income owners. A salary decision therefore moves the SEP, payroll tax, and the deduction at the same time.
| Item | Amount | Counts toward the SEP base? |
|---|---|---|
| W-2 wages | $120,000 | Yes |
| Schedule K-1 ordinary business income | $150,000 | No |
| Cash distributions | $100,000 | No |
| SEP base | $120,000 | Wages only |
| Maximum SEP contribution | $30,000 | 25 percent of wages |
| SEP if K-1 income counted (it does not) | $67,500 | Not available |
How do partnerships handle SEP deadlines and deductions?
A partnership sets the SEP deadline through Form 1065, due March 15, 2027 for 2026, or September 15, 2027 with Form 7004. Contributions for common law employees are deducted by the partnership. Contributions for partners are reported on Schedule K-1 in box 13 with code R and deducted by each partner on their own return.
- Plan sponsor: the partnership, not each partner separately.
- Employees: deducted on Form 1065, line 18.
- Partners: reported on Schedule K-1, box 13, code R, and deducted personally.
- Deadline: tied to the partnership’s return, not the partners’ returns.
The Form 1065 instructions say not to deduct payments for partners to retirement plans, including SEP and SIMPLE IRA plans, on line 18. Those amounts are reported in box 13 of Schedule K-1 using code R and are deducted by the partners on their own returns. Each partner’s contribution is figured on that partner’s net earnings from self-employment from the partnership, using the self-employed rate.
The IRS SEP FAQ adds that partners cannot each maintain a separate SEP. Only an employer can maintain a SEP, and for partners the employer is the partnership. A partner who opens an individual SEP for partnership income, separate from any plan the partnership adopted, has not established a plan the statute recognizes.
Partnership timing creates a pinch. The partnership’s deadline is March 15, but each partner’s net earnings figure often is not final until the partnership return is prepared. Many partnerships file Form 7004 for that reason, which also preserves the September 15 SEP date.
| Item | Where it is reported | Who deducts it | Deadline that controls |
|---|---|---|---|
| Contribution for a common law employee | Form 1065, line 18 | Partnership | Form 1065 due date with extensions |
| Contribution for a partner | Schedule K-1, box 13, code R | Partner, on Schedule 1 of Form 1040 | Form 1065 due date with extensions |
| Plan adoption | Partnership records | Not applicable | Form 1065 due date with extensions |
| Authority | Form 1065 instructions | Publication 560 | IRC 404(h)(1)(B) |
What is the SEP deadline for a C corporation?
A calendar year C corporation has until its Form 1120 due date, April 15, 2027 for the 2026 tax year, or October 15, 2027 with a Form 7004 extension, to deposit a SEP contribution. The corporation deducts the contribution on line 23 of Form 1120, and contributions for owner employees are based on their W-2 wages.
- Return: Form 1120, due the 15th day of the fourth month after year end.
- Extension: Form 7004, generally six months.
- Deduction line: line 23, pension, profit-sharing, and similar plans.
- Base: W-2 wages for owner employees and staff alike.
The Form 1120 instructions direct the deduction for contributions to qualified pension, profit-sharing, or other funded deferred compensation plans to line 23. A SEP contribution belongs there. The timing rule is the same section 404(h)(1)(B) rule that applies to every other employer, so the deadline is the corporation’s return due date including any extension it actually obtained.
C corporations with a fiscal year need extra care. The SEP limit is figured on compensation paid during the calendar year ending with or within the taxable year, so a corporation with a June 30 year end measures compensation over a different period than its fiscal year. Publication 560 describes the fiscal year rule, and fiscal year SEPs are uncommon enough that the plan document and the custodian’s forms should be checked carefully.
C corporation owners often pair the SEP with other benefits and with salary planning, since the corporation pays its own income tax. Our business advisory services page describes how those compensation decisions are coordinated.
| Tax year | Form 1120 due date | Extended due date with Form 7004 | Deduction line |
|---|---|---|---|
| Calendar year 2026 | April 15, 2027 | October 15, 2027 | Line 23 |
| Fiscal year corporation | Generally the 15th day of the fourth month after year end | Generally six months later; confirm in the instructions | Line 23 |
| Authority | Form 1120 instructions | Form 7004 instructions | Form 1120 instructions |
What are the 2026 SEP IRA contribution limits?
For 2026, a SEP contribution for any one person cannot exceed the lesser of 25 percent of compensation or $72,000, and compensation above $360,000 is ignored. An employee must be covered once they earn at least $800 from the employer in 2026. The figures come from IRS Notice 2025-67 and were checked on the publication date of this guide.
- Dollar limit: $72,000, up from $70,000 for 2025.
- Compensation cap: $360,000, up from $350,000.
- Coverage pay floor: $800, up from $750.
- No catch-up: a SEP has no age 50 catch-up of its own.
IRS Notice 2025-67 raised the section 415(c) limit on annual additions to $72,000 for 2026, the section 401(a)(17) compensation limit to $360,000, and the section 408(k)(2)(C) minimum compensation amount for simplified employee pensions to $800. The IRS cost of living adjustment table shows the same figures. These are the limits that apply to a contribution made for 2026, even though the deposit itself may happen in 2027.
That last point matters during the overlap months. Between January 1 and the 2025 deadline, an owner could make deposits for 2025 under the 2025 limits and for 2026 under the 2026 limits into the same account. The custodian reports both on the form for the deposit year, so the business records have to keep the two years apart. For deposits made in 2027 for 2026, the 2026 limits apply.
The limits are per person, not per plan, when the same employer maintains more than one defined contribution plan. An owner who has both a SEP and a profit sharing plan with the same business shares one $72,000 ceiling across them.
| Item | 2026 amount | 2025 amount | Authority |
|---|---|---|---|
| Annual additions limit, section 415(c) | $72,000 | $70,000 | Notice 2025-67 |
| Compensation limit, section 401(a)(17) | $360,000 | $350,000 | Notice 2025-67 |
| SEP minimum compensation, section 408(k)(2)(C) | $800 | $750 | Notice 2025-67 |
| Percentage limit | 25 percent of compensation | 25 percent of compensation | IRC 404(h)(1)(C) |
| Self-employed effective rate | 20 percent of net earnings | 20 percent of net earnings | Publication 560 |
| Traditional or Roth IRA limit, for comparison | $7,500 | $7,000 | Notice 2025-67 |
Can I still contribute to a SEP IRA for 2025?
Generally no, not as of November 2026. For calendar year businesses, the latest 2025 SEP deadlines were September 15, 2026 for extended S corporations and partnerships and October 15, 2026 for extended sole proprietors and C corporations. A deposit made now counts for 2026 instead, unless a federal disaster postponement covering the business still applies.
- Pass-through entities: March 16, 2026, or September 15, 2026 with an extension.
- Individuals and C corporations: April 15, 2026, or October 15, 2026 with an extension.
- Exception: a disaster postponement under section 7508A can extend the date.
- Now: any SEP deposit made in late 2026 is a 2026 contribution.
The 2025 deadlines followed the same pattern as the 2026 deadlines, with one weekend shift. March 15, 2026 fell on a Sunday, so section 7503 moved the unextended pass-through date to Monday, March 16, 2026. The other dates fell on weekdays. Each of those dates has now passed, so an owner who missed the 2025 window cannot reopen it by depositing late.
The one real exception is a federal disaster declaration. When the IRS grants relief under section 7508A, the postponement can cover acts that include making contributions under section 404(h)(1)(B), according to Treasury Regulation section 301.7508A-1(c)(1)(iii). Southwest Florida owners have seen this relief after recent hurricanes. Whether a postponement still applies depends on the specific IRS announcement, the county, and the dates in it.
A deposit made now is not wasted. It counts toward the 2026 limit and is deductible on the 2026 return, which simply means the owner has started the 2026 contribution early.
| Business type | Original deadline | Extended deadline | Status on November 12, 2026 |
|---|---|---|---|
| S corporation or partnership | Monday, March 16, 2026 | Tuesday, September 15, 2026 | Passed |
| Sole proprietor | Wednesday, April 15, 2026 | Thursday, October 15, 2026 | Passed |
| C corporation | Wednesday, April 15, 2026 | Thursday, October 15, 2026 | Passed |
| Business in a disaster area with an active postponement | Per the IRS announcement | Per the IRS announcement | Check the specific relief |
What is the solo 401(k) contribution deadline?
A solo 401(k) has two deadlines. The employer contribution follows the SEP IRA contribution deadline rule, the business return due date including extensions. The employee deferral is different: for an existing plan, the owner must elect it by December 31, 2026, and deposit timing depends on how the owner is paid.
- Employer contribution: by the return due date, including extensions.
- Deferral election, existing plan: by the last day of the tax year.
- Deferral deposit, S corporation owner: through payroll, with wages paid in 2026.
- Deferral, new sole proprietor plan: special first-year rule, covered next.
The employer side of a solo 401(k) is a profit sharing contribution, and section 404(a)(6) treats it as made on the last day of the year if it is paid on account of that year by the time prescribed for filing the return, including extensions. Publication 560 says the same thing for qualified plans generally: deductible contributions for a tax year can be made up to the due date of the return plus extensions.
The employee side is tighter. A deferral is a choice to put compensation into the plan instead of receiving it, and the choice has to be made before the compensation is available. Under Treasury Regulation section 1.401(k)-1(a)(6)(iii), a sole proprietor’s compensation is deemed currently available on the last day of the tax year, and a partner’s on the last day of the partnership’s year, so the election for 2026 has to be made by December 31, 2026. The deposit can follow later, but the election cannot.
An S corporation owner defers through payroll, like any employee. The deferral comes out of a 2026 paycheck, which means it has to be withheld from wages paid in 2026. For that owner there is no post year end deferral at all, only the employer contribution.
| Contribution | Sole proprietor | S corporation owner | Authority |
|---|---|---|---|
| Deferral election | By December 31, 2026 | Before the 2026 wages are paid | Reg. 1.401(k)-1(a)(6)(iii) |
| Deferral deposit | Generally soon after; plan terms and the return timing apply | Withheld from 2026 payroll | IRS one-participant page |
| Employer contribution | By April 15, 2027, or October 15, 2027 with an extension | By March 15, 2027, or September 15, 2027 with an extension | IRC 404(a)(6) |
| Form 5500-EZ | If plan assets exceed $250,000 at year end | Same | IRS one-participant page |
Can I open a solo 401(k) after December 31 and still contribute for 2026?
Yes, with limits. Under section 401(b)(2), a plan adopted by the extended return due date can receive 2026 employer contributions. A sole proprietor who is the plan’s only employee can also make 2026 first-year deferrals before the unextended due date, April 15, 2027. S corporation owners do not get that deferral rule.
- Late adoption: allowed through the extended due date for employer contributions.
- First-year deferral: sole proprietors only, by the unextended due date.
- S corporation owners: no post year end deferral, because wages already closed.
- Source: SECURE Act section 201 and SECURE 2.0 section 317.
The SECURE Act amended section 401(b)(2) to let an employer that adopts a qualified plan after the close of a taxable year, but before the time for filing its return including extensions, elect to treat the plan as adopted on the last day of that year. That rule covers employer contributions. It did not solve the deferral problem, because a deferral election normally has to precede the year end.
SECURE 2.0 section 317 then added a sentence for one group. An individual who owns the entire interest in an unincorporated business, and who is its only employee, can make elective deferrals for the first plan year before the time for filing the individual’s return for that year, determined without regard to extensions, and they are treated as made before the end of the first plan year. Publication 560 repeats that the deferral must be paid to the plan before the unextended filing date.
The practical result is a split calendar for a new sole proprietor plan adopted in early 2027. The deferral has to reach the plan by April 15, 2027, while the employer contribution can wait until October 15, 2027 if an extension is filed. An S corporation owner who adopts a solo 401(k) in 2027 can receive an employer contribution for 2026 but no 2026 deferral.
| Owner | 2026 employer contribution | 2026 deferral | Last date for the deferral |
|---|---|---|---|
| Sole proprietor, only employee | Yes, by the extended due date | Yes, first-year rule | April 15, 2027 |
| Single member LLC taxed as a sole proprietor | Yes | Yes, first-year rule | April 15, 2027 |
| S corporation owner | Yes, based on 2026 wages | No | Not available |
| Two partner partnership | Yes | Generally no, rule requires sole ownership | Not available |
| Sole proprietor with an eligible employee | Solo design unavailable | Not available | Not available |
How does a hypothetical Schedule C owner compare a SEP and a solo 401(k) at the deadline?
For a hypothetical sole proprietor with $180,000 of 2026 net profit, the SEP maximum is about $33,457, deposited by April 15, 2027 or October 15, 2027 with an extension. An existing solo 401(k) could hold about $57,957, but $24,500 of that is a deferral that must be elected by December 31, 2026 unless the first-year rule applies.
- SEP IRA: about $33,457, all of it available after year end.
- Existing solo 401(k): about $57,957, with the deferral elected by year end.
- New solo 401(k) in early 2027: about $57,957, with the deferral by April 15, 2027.
- Missing the election: leaves only the $33,457 employer amount.
The figures come from the worksheet earlier in this guide. Net earnings after the half self-employment tax deduction are about $167,283, and 20 percent of that is about $33,457. The solo 401(k) adds the $24,500 deferral for an owner under age 50, for about $57,957 in total, well under the $72,000 limit. An owner age 50 or older could add the $8,000 catch-up in the solo 401(k) only.
The deadline column is what changes the choice in practice. An owner reading this in November 2026 still has time to adopt and elect deferrals under a solo 401(k) before year end, or to rely on the first-year rule for a plan adopted in early 2027. An owner reading it in May 2027 without an extension has neither option for 2026 and can only look at a SEP, and only if an extension was filed.
The SEP IRA vs solo 401k comparison covers the other differences, including the pro rata issue a SEP balance creates for a backdoor Roth IRA.
| Plan | Maximum contribution | Part available after December 31, 2026 | Last date for the 2026 contribution |
|---|---|---|---|
| SEP IRA | $33,457 | $33,457 | April 15, 2027, or October 15, 2027 with an extension |
| Existing solo 401(k), deferral elected by year end | $57,957 | $33,457 employer; deferral deposit per plan terms | Employer by October 15, 2027 with an extension |
| Existing solo 401(k), no deferral election | $33,457 | $33,457 | October 15, 2027 with an extension |
| New solo 401(k) adopted in 2027 | $57,957 | $57,957 | Deferral by April 15, 2027; employer by October 15, 2027 with an extension |
How does a hypothetical S corporation owner compare the two plans at the deadline?
For a hypothetical S corporation owner with $120,000 of 2026 W-2 wages, a SEP allows up to $30,000, deposited by March 15, 2027 or September 15, 2027 with an extension. A solo 401(k) in place during 2026 could add a $24,500 deferral withheld from 2026 payroll, for $54,500, but no deferral can be added after the year closes.
- SEP IRA: $30,000, available until the corporation’s extended due date.
- Solo 401(k) with 2026 payroll deferrals: up to $54,500.
- Solo 401(k) adopted in 2027: $30,000 employer only for 2026.
- Fixed point: the wage base is locked on December 31, 2026.
The S corporation case is the strongest argument for planning in the fourth quarter. Every number for 2026 depends on the W-2 wages paid in 2026, and the deferral has to come out of those same paychecks. By January, the owner’s choices for 2026 have narrowed to the employer contribution, at 25 percent of wages that are already fixed.
The deadline for the employer contribution is the corporation’s, under section 404. If the corporation will not finish its return by March 15, filing Form 7004 by that date preserves the September 15 deposit date for both a SEP and the employer side of a solo 401(k).
Owners who want more room than 25 percent of wages sometimes add a cash balance plan, which has its own funding calendar discussed later. That is a larger design decision with ongoing costs, and it usually starts with the same wage figure.
| Plan | 2026 maximum | Deadline for the employer part | Deadline for the deferral |
|---|---|---|---|
| SEP IRA | $30,000 | March 15, 2027, or September 15, 2027 with Form 7004 | Not applicable |
| Solo 401(k) in place during 2026 | $54,500 | March 15, 2027, or September 15, 2027 with Form 7004 | 2026 payroll |
| Solo 401(k) adopted in 2027 | $30,000 | September 15, 2027 with Form 7004 | Not available for 2026 |
| Wages needed for $72,000 in a SEP | $288,000 | Paid during 2026 | Not applicable |
Does a tax extension move the IRA contribution deadline?
No. A traditional or Roth IRA contribution for 2026 must be made by April 15, 2027, even if the owner files an extension. That is the main difference from the SEP IRA contribution deadline, which follows the business return including extensions. The 2026 IRA limit is $7,500, plus $1,100 at age 50 or older.
- IRA statute: section 219(f)(3) uses the due date not including extensions.
- SEP statute: section 404(h)(1)(B) uses the due date including extensions.
- Same account, different rules: a SEP IRA can also accept a regular IRA contribution, under the IRA deadline.
- 2026 IRA limits: $7,500, and $8,600 at age 50 or older.
IRC section 219(f)(3) treats an IRA contribution as made on the last day of the prior year only if it is made by the time prescribed for filing the return, not including extensions. Publication 590-A restates the rule: contributions for a year can be made by the due date, not including extensions, for filing the return for that year. Compare the SEP rule in section 404(h)(1)(B), which says including extensions. The two statutes differ by a single word.
The difference trips up owners who hear that they have until October to fund retirement. That is true for the SEP and for the employer side of a qualified plan, and false for the owner’s own traditional or Roth IRA. An owner who files Form 4868 and plans to fund both in September will find that the IRA contribution for 2026 is no longer available.
The 2026 IRA limit of $7,500 and the catch-up of $1,100 come from IRS Notice 2025-67. An owner who uses the IRA for a backdoor Roth should also remember that SEP IRA balances count in the pro rata calculation, and that the Roth conversion ladder has its own year end timing.
| Contribution | Deadline | Does Form 4868 move it? | Authority |
|---|---|---|---|
| Traditional IRA contribution | April 15, 2027 | No | IRC 219(f)(3) |
| Roth IRA contribution | April 15, 2027 | No | Publication 590-A |
| SEP employer contribution | April 15, 2027, or October 15, 2027 | Yes | IRC 404(h)(1)(B) |
| SEP plan adoption | April 15, 2027, or October 15, 2027 | Yes | IRS SEP page |
| Roth conversion | December 31, 2026 | No, conversions follow the calendar year | IRC 408A |
Can I contribute to both a SEP IRA and a regular IRA for the same year?
Yes. A SEP contribution is an employer contribution and does not reduce the $7,500 IRA limit for 2026. The owner can also make a regular traditional or Roth IRA contribution, subject to income rules. Because a SEP makes the owner an active plan participant, a traditional IRA deduction may be reduced at higher incomes.
- Separate limits: $72,000 for the SEP and $7,500 for the regular IRA in 2026.
- Active participant: a SEP makes the owner an active participant for the IRA deduction rules.
- Roth IRA: subject to its own income limits, not to the SEP.
- Deadlines: April 15, 2027 for the IRA, the extended business date for the SEP.
Publication 590-A explains that a person covered by an employer retirement plan, which includes a SEP, may have the traditional IRA deduction reduced or eliminated depending on modified adjusted gross income and filing status. The contribution can still be made on a nondeductible basis, which creates basis tracked on Form 8606. The SEP itself is not reduced.
Owners sometimes deposit both amounts into the same SEP IRA. Many custodians allow it, and the account then holds employer money and the owner’s regular contribution together. The custodian’s form needs to show which deposit is which, since the regular IRA deposit is reported for the year designated and the SEP deposit for the year received.
A nondeductible traditional IRA contribution sitting next to a large SEP balance is the setup that makes a later Roth conversion mostly taxable under the pro rata rule. Our guide to the mega backdoor Roth describes a different route that uses a 401(k) instead.
| Account | Amount | Deadline | Notes |
|---|---|---|---|
| SEP IRA, employer contribution | $33,457 | October 15, 2027 with an extension | Deductible on Schedule 1 |
| Traditional IRA, regular contribution | $7,500 | April 15, 2027 | Deduction may be limited by active participation |
| Roth IRA, regular contribution | Instead of the traditional IRA, if eligible | April 15, 2027 | Shares the $7,500 IRA limit |
| Combined retirement savings | $40,957 | Two different dates | Hypothetical |
What is the SIMPLE IRA contribution deadline?
A SIMPLE IRA has split deadlines. Employee salary deferrals must reach the SIMPLE IRAs within 30 days after the end of the month in which the pay would otherwise have been received. Employer matching or nonelective contributions can be made by the return due date, including extensions. For an owner, that makes the SIMPLE a mostly current year plan.
- Employee deferrals: within 30 days after the end of the month they were withheld.
- Employer match or nonelective: by the return due date, including extensions.
- Plan setup: generally by October 1 of the year for a new plan.
- 2026 deferral limit: $17,000, or $18,100 for some employers.
Publication 560 states that the employer must make salary reduction contributions to the SIMPLE IRA within 30 days after the end of the month in which the amounts would otherwise have been payable in cash, and must make matching or nonelective contributions by the due date, including extensions, for filing the federal return for the year. It also notes that plans subject to Department of Labor rules may have an earlier date for salary reduction contributions.
That makes the SIMPLE quite different from a SEP for deadline planning. Most of a SIMPLE’s value comes from the deferral, and the deferral cannot be made after the fact. An owner who wants a plan that can be decided entirely after the year closes will find that only a SEP works that way.
The 2026 SIMPLE deferral limit is $17,000, or $18,100 for employers that qualify for the higher limit, and the age 50 catch-up is $4,000, all from IRS Notice 2025-67. Owners with staff often compare a SIMPLE with a safe harbor 401(k).
| Plan | Employee or owner deferral | Employer contribution | Latest plan adoption for 2026 |
|---|---|---|---|
| SEP IRA | Not available for a new SEP | Extended return due date | Extended return due date |
| SIMPLE IRA | Within 30 days after the end of the month withheld | Extended return due date | Generally October 1, 2026 for a new plan |
| Solo 401(k), existing | Elected by December 31, 2026 | Extended return due date | Already in place |
| Solo 401(k), new, sole proprietor | By April 15, 2027 under the first-year rule | Extended return due date | Extended return due date |
What are the deadlines for a cash balance or defined benefit plan?
A defined benefit plan, including a cash balance plan, has two separate dates. The deduction deadline under section 404(a)(6) is the return due date, including extensions. The minimum funding deadline under section 430(j) is eight and a half months after the end of the plan year, which is September 15, 2027 for a 2026 calendar plan year.
- Deduction timing: by the business return due date, including extensions.
- Minimum funding: within 8 and a half months after the plan year ends.
- Calendar 2026 plan year: September 15, 2027 for minimum funding.
- Adoption: a new plan for 2026 may be adopted by the extended due date under section 401(b)(2).
IRC section 430(j)(1) requires the minimum required contribution for a plan year to be paid no later than 8 and a half months after the close of the plan year. That is a funding requirement, enforced separately from the deduction. The deduction rule in section 404(a)(6) treats a contribution as made on the last day of the year when it is made by the return due date, including extensions.
For a sole proprietor with an October 15 extended due date, the two dates can diverge, because the funding date for a calendar plan year arrives on September 15. An owner who relies on the October date for a defined benefit plan risks missing the funding requirement even though the deduction would still have been timely. Actuaries generally set the contribution schedule, and the owner should treat their dates as controlling.
Our guide to cash balance plans for business owners covers the design and the annual cost. This guide includes the plan only to show that its deadline is not the same as a SEP’s.
| Plan or contribution | Deadline | Authority |
|---|---|---|
| Defined benefit minimum required contribution | September 15, 2027 | IRC 430(j) |
| Defined benefit deduction | Return due date, including extensions | IRC 404(a)(6) |
| 401(k) deferral election, self-employed | December 31, 2026 | Reg. 1.401(k)-1(a)(6)(iii) |
| Traditional or Roth IRA | April 15, 2027 | IRC 219(f)(3) |
| Roth conversion | December 31, 2026 | IRC 408A |
What happens when a SEP deadline falls on a weekend or holiday?
Under section 7503, a deadline that falls on a Saturday, Sunday, or legal holiday moves to the next business day. For the 2026 tax year, the SEP dates in 2027 all fall on weekdays, so no shift applies. For the 2025 tax year, March 15, 2026 was a Sunday, so the pass-through deadline moved to Monday, March 16, 2026.
- Rule: the next day that is not a Saturday, Sunday, or legal holiday.
- 2027 dates: March 15 Monday, April 15 Thursday, September 15 Wednesday, October 15 Friday.
- Holiday note: a District of Columbia holiday can also move a federal date.
- Practical margin: custodians may need several business days to settle a deposit.
IRC section 7503 provides that when the last day prescribed for performing an act falls on a Saturday, Sunday, or legal holiday, the act is timely if performed on the next succeeding day that is not one of those days. The SEP deposit is an act prescribed by the internal revenue laws, so the rule reaches it.
The statute protects the date, not the settlement time. A custodian may need the money in the account by its own cutoff on the deadline, and a transfer initiated after the cutoff may post the next day. Owners who deposit near the deadline should ask the custodian what counts as received and keep the confirmation showing the date.
Mailed checks raise the same question. A check mailed on the deadline may not reach the custodian until later, and the custodian dates the deposit when it is received. An electronic transfer started a few days early is usually the safer approach.
| Date | Weekday | Effect |
|---|---|---|
| March 15, 2026 | Sunday | Moved to Monday, March 16, 2026 |
| April 15, 2026 | Wednesday | No change |
| September 15, 2026 | Tuesday | No change |
| October 15, 2026 | Thursday | No change |
| March 15, 2027 | Monday | No change |
| April 15, 2027 | Thursday | No change |
| September 15, 2027 | Wednesday | No change |
| October 15, 2027 | Friday | No change |
Do hurricane disaster postponements extend the SEP deadline?
They can. Treasury Regulation section 301.7508A-1 lists making contributions under section 404(h)(1)(B) among the acts the IRS may postpone after a federally declared disaster. When the IRS announces relief for Florida counties after a hurricane, the announcement sets the postponed date, and a SEP deposit due inside the relief window can generally be made by that later date.
- Authority: section 7508A and Reg. 301.7508A-1(c)(1)(iii).
- Covered acts: contributions under sections 219(f)(3), 404(a)(6), 404(h)(1)(B), and 404(m)(2).
- Scope: set by each IRS announcement, by county and by date.
- Check first: the relief applies only to affected taxpayers in covered areas.
IRC section 7508A lets the IRS postpone deadlines for taxpayers affected by a federally declared disaster. The regulation at section 301.7508A-1(c)(1)(iii) lists, among the acts that can be postponed, making contributions to a qualified retirement plan under sections 219(f)(3), 404(a)(6), 404(h)(1)(B), or 404(m)(2). Revenue Procedure 2018-58 contains the IRS list of time sensitive acts that may be postponed, including IRA contributions.
Southwest Florida has had several of these announcements in recent years. Each one names counties and a postponement date, and the IRS publishes them on its disaster relief page. An owner in a covered county whose SEP deadline fell inside the window may have had more time than the standard calendar shows.
Relief is not automatic in every case. It depends on where the business or its records are located, on the dates in the specific notice, and sometimes on contacting the IRS. Owners should not assume relief applies without checking the announcement that covers their county.
| Situation | Standard SEP deadline | If an IRS postponement covers it | What to check |
|---|---|---|---|
| Sole proprietor, deadline inside the relief window | April 15 | Postponed date in the IRS announcement | County, dates, and affected taxpayer status |
| S corporation, deadline inside the window | March 15 | Postponed date in the announcement | Business location and records location |
| Deadline outside the window | Standard date | No change | Window start and end dates |
| IRA contribution in a covered area | April 15 | May be postponed under Rev. Proc. 2018-58 | Announcement wording |
What is the 3-year rule for SEP IRA eligibility?
A SEP must cover every employee who is at least 21, has worked for the employer in at least 3 of the last 5 years, and has received at least $800 of 2026 compensation. The 3 year rule is a maximum waiting period. An employer may use a shorter period but not a longer one.
- Age: 21 or older.
- Service: worked for the employer in at least 3 of the immediately preceding 5 years.
- Pay: at least $800 of compensation in 2026.
- Flexibility: less restrictive rules are allowed, stricter rules are not.
The rule comes from IRC section 408(k)(2), and Publication 560 lists the same three conditions. Any day of work in a year counts as service for that year, which is why a part-time employee who worked a few weeks in each of three years can qualify. Certain union employees and nonresident aliens with no United States source earned income may be excluded.
The rule matters to deadlines because coverage is decided for the year the contribution is for. An owner who decides in September 2027 to make a 2026 SEP contribution has to look back at who was eligible during 2026 and contribute the same percentage for each of them by the same deadline. A former employee who left in 2026 can still be owed a contribution.
Owners with no employees can skip this analysis, but should revisit it when they hire. A first employee who meets the conditions changes a SEP from a one person plan into a plan that has to cover staff at the same rate as the owner.
| Worker | Age in 2026 | Years worked in 2021 through 2025 | 2026 pay | Must be covered? |
|---|---|---|---|---|
| Owner | 48 | 5 | Net earnings of $167,283 | Yes |
| Office manager | 39 | 4 | $52,000 | Yes |
| Part-time assistant | 24 | 3 | $9,500 | Yes |
| Seasonal helper | 19 | 2 | $4,200 | No, under age 21 |
| New hire in 2026 | 33 | 0 | $28,000 | No, under 3 years |
Do I have to contribute for employees if I make a SEP contribution for myself?
Yes. A SEP contribution has to be made for every eligible employee as a uniform percentage of compensation, using the same rate the owner receives, and it is due by the same deadline. An owner who contributes 25 percent for an S corporation salary must generally contribute 25 percent of each eligible employee’s pay for the same year.
- Uniform rate: the same percentage of compensation for every eligible participant.
- Same deadline: employee contributions follow the owner’s deadline.
- Self-employed owner: the 25 percent plan rate becomes about 20 percent for the owner, while staff receive the full 25 percent.
- Optional each year: the employer can choose 0 percent for everyone.
IRC section 408(k)(3) requires that SEP contributions not discriminate in favor of highly compensated employees, and contributions are treated as meeting that requirement when they bear a uniform relationship to compensation, up to the compensation limit. The IRS SEP page explains that employer contributions must be based only on the first $360,000 of compensation for 2026 and must be uniform for all eligible employees.
The flexibility is in the amount, not in who receives it. An employer can contribute 25 percent one year, 5 percent the next, and nothing the year after, but whatever it does applies to every eligible person. For deadline planning, that means the cash needed by March 15 or April 15 is the owner’s contribution plus the contributions for staff, not the owner’s amount alone.
The rate difference for a self-employed owner surprises many employers. A 25 percent plan rate produces about 20 percent of the owner’s net earnings, but staff on W-2 pay receive the full 25 percent of wages. Owners who want a different structure often look at a profit sharing plan with a different allocation formula.
| Participant | Compensation base | Rate applied | 2026 contribution | Deadline |
|---|---|---|---|---|
| Owner | Net earnings of $167,283 | 20 percent effective | $33,457 | April 15, 2027 or October 15, 2027 with an extension |
| Office manager | $52,000 wages | 25 percent | $13,000 | Same |
| Part-time assistant | $9,500 wages | 25 percent | $2,375 | Same |
| Total cash needed | Not applicable | Not applicable | $48,832 | Same |
When must employees be told about SEP contributions?
An employer using Form 5305-SEP must give each eligible employee a copy of the form, its instructions, and the other required information when the plan is adopted, and must tell each participant about employer contributions made to their SEP IRA by January 31 of the following year, or 30 days after the contribution if later.
- At adoption: a copy of Form 5305-SEP and the required plan information.
- Annual notice: contributions made for the year, by January 31 or within 30 days after the deposit.
- Late deposits: a September deposit for the prior year triggers the 30 day notice.
- Prototype plans: similar information is required.
The IRS SEP plan page states that the employer must inform each participant of employer contributions made to the participant’s IRA by January 31 of the following year, or if later, 30 days after the contribution is made. The Form 5305-SEP instructions describe the information to be given at adoption. The IRS SEP FAQ adds that a prototype or individually designed SEP requires similar information.
For an owner with no employees the notice is a formality. For an employer with staff, the notice follows the deposit, so a business that funds its 2026 SEP in September 2027 owes the notices about 30 days later. A payroll provider or the plan custodian may prepare them, but the obligation stays with the employer.
These notices are also a useful internal check. Writing down each employee’s compensation and contribution forces the uniform percentage calculation, which is where most SEP corrections begin.
| Deposit date | Notice deadline | Rule applied |
|---|---|---|
| December 15, 2026 | January 31, 2027 | January 31 of the following year |
| March 30, 2027 | April 29, 2027 | 30 days after the contribution |
| September 10, 2027 | October 10, 2027 | 30 days after the contribution |
| At plan adoption | When adopted | Copy of Form 5305-SEP and required information |
What happens if I contribute too much to a SEP IRA?
Excess SEP contributions are included in the employee’s gross income. The IRS says an employee who withdraws the excess plus earnings by the due date of their return, including extensions, avoids the 6 percent excise tax on excess IRA contributions. The employer may also face a 10 percent excise tax on nondeductible contributions under section 4972.
- Employee side: excess included in income, and 6 percent a year under section 4973 if left in the IRA.
- Correction window: withdraw the excess and earnings by the employee’s extended due date.
- Employer side: a possible 10 percent tax under section 4972 on nondeductible amounts.
- Common cause: a deposit for the wrong year stacked on the right year’s contribution.
The IRS SEP FAQ explains that excess contributions are included in employees’ gross income, and that employees who withdraw the excess contribution plus earnings before the due date of their federal return, including extensions, avoid the 6 percent excise tax imposed by section 4973. Excess amounts left in the account after that date are subject to the 6 percent tax for each year they remain. On the employer side, section 4972 imposes a 10 percent tax on nondeductible contributions to a qualified employer plan, and SEP contributions in excess of the deduction limit can be treated as nondeductible.
Deadline confusion is a common source of excess contributions. An owner who deposits $40,000 in November 2027 for 2026, after the 2026 window closed, has made a 2027 contribution. If the owner then makes a full 2027 contribution in 2028, the total can exceed the 2027 limit. The fix starts with the deposit records, which show what was deposited, when, and for which year.
Correction is a technical process with reporting consequences on Forms 1099-R and 5498. The IRS publishes correction guidance for SEP plans, and the employer, custodian, and preparer usually need to coordinate.
| Deposit | Date | Treated as a contribution for | Running 2027 total |
|---|---|---|---|
| Intended for 2026, deposited after the window | November 3, 2027 | 2027 | $40,000 |
| 2027 contribution | April 12, 2028 | 2027 | $75,000 |
| 2027 maximum | Not applicable | Not applicable | $35,000 |
| Excess for 2027 | Not applicable | Not applicable | $40,000 |
Where is the SEP deduction reported on each type of return?
A sole proprietor deducts their own SEP contribution on Schedule 1 of Form 1040, line 16, and deducts employees’ contributions on Schedule C. An S corporation uses Form 1120-S, line 17. A partnership uses Form 1065, line 18, for employees and Schedule K-1, box 13, code R, for partners. A C corporation uses Form 1120, line 23.
- Sole proprietor, own contribution: Schedule 1 of Form 1040, line 16.
- Sole proprietor, employees: Schedule C, pension and profit-sharing plans line.
- S corporation: Form 1120-S, line 17.
- Partnership: line 18 for employees, K-1 code R for partners; C corporation: line 23.
The line references come from the current instructions. The Form 1120-S instructions list line 17 for pension, profit-sharing, and similar plans; the Form 1065 instructions list line 18 for retirement plans and send partners’ amounts to box 13 code R; and the Form 1120 instructions list line 23. Publication 560 describes the sole proprietor’s own deduction on Schedule 1. Line numbers can change from year to year, so the year’s form should be checked before filing.
The reporting location matters for the deadline because it shows whose return controls. For a sole proprietor, the deduction is on the personal return, so Form 4868 extends the SEP date. For a partner, the partnership’s return reports the amount, and the partnership’s extension controls. For an S corporation owner, the corporation’s Form 7004 controls.
A sole proprietor’s own SEP deduction is an adjustment to income, not a business expense on Schedule C, which is why it does not reduce self-employment tax, as the next section explains.
| Entity | Owner’s contribution | Employees’ contributions | Extension that controls the SEP deadline |
|---|---|---|---|
| Sole proprietor | Schedule 1 of Form 1040 | Schedule C | Form 4868 |
| Partnership | Schedule K-1, box 13, code R | Form 1065, line 18 | Partnership Form 7004 |
| S corporation | Form 1120-S, line 17 | Form 1120-S, line 17 | Corporation Form 7004 |
| C corporation | Form 1120, line 23 | Form 1120, line 23 | Corporation Form 7004 |
Does a SEP contribution reduce self-employment tax?
No, not for a sole proprietor or partner. A self-employed owner’s own SEP contribution is deducted on Schedule 1 as an adjustment to income, after self-employment tax has been figured on Schedule SE. It reduces income tax only. For an S corporation owner, the contribution is not wages, so it is not subject to Social Security or Medicare tax either.
- Sole proprietor: income tax savings only, no SE tax change.
- Partner: same treatment as a sole proprietor.
- S corporation owner: employer contribution, not wages, so no FICA on it.
- Employees: contributions for staff reduce the business’s profit and its SE tax base.
Self-employment tax is computed on net earnings from self-employment under section 1402, which are figured before the owner’s own retirement plan deduction. Publication 560 places the deduction for the owner’s own SEP on Schedule 1, and the deduction for employees’ contributions on the business schedule. That is why a sole proprietor with $180,000 of net profit owes the same self-employment tax whether or not a SEP contribution is made.
Contributions made for employees are different. They are a business expense on Schedule C, so they reduce net profit, which reduces the owner’s self-employment tax base. A sole proprietor with staff therefore sees a partial self-employment tax effect from the employees’ share.
The income tax saving for the owner depends on the marginal bracket and on the effect on other items, including the qualified business income deduction, covered next.
| Item | Without the SEP | With the SEP | Change |
|---|---|---|---|
| Self-employment tax | $25,433 | $25,433 | $0 |
| Adjusted gross income before other items | $167,283 | $133,826 | Down $33,457 |
| Income tax | Depends on the full return | Lower | Depends on the bracket and other deductions |
| Qualified business income | $167,283 before other reductions | $133,826 before other reductions | Down $33,457 |
How does a SEP contribution affect the qualified business income deduction?
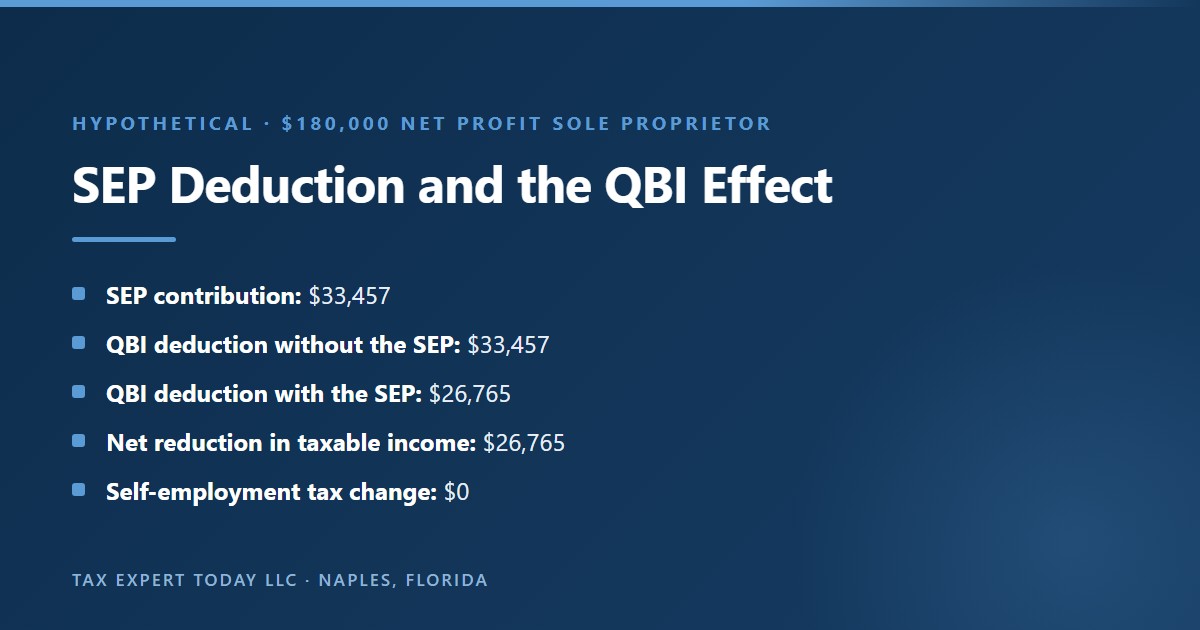
For a self-employed owner, the SEP deduction generally reduces qualified business income, because Treasury Regulation section 1.199A-3(b)(1)(vi) treats deductions for qualified retirement plan contributions as attributable to the business. A hypothetical $33,457 contribution therefore lowers the base for the 20 percent deduction by the same amount, which trims part of the income tax benefit.
- Regulation: deductions under section 404 reduce QBI proportionately to the business income.
- Effect: a $33,457 SEP can reduce the QBI deduction by about $6,692.
- S corporation owner: the corporation’s deduction already reduces the pass-through income.
- Planning: compare the after-QBI saving, not the gross deduction.
Treasury Regulation section 1.199A-3(b)(1)(vi) provides that, for purposes of section 199A only, deductions such as the deductible part of self-employment tax, the self-employed health insurance deduction, and the deduction for contributions to qualified retirement plans under section 404 are considered attributable to a trade or business, to the extent the individual’s gross income from that business is taken into account in calculating the deduction. IRC section 199A supplies the deduction itself.
The result is that a SEP contribution does two things at once. It lowers taxable income by the contribution, and it lowers qualified business income by the contribution, which lowers the deduction that would otherwise be 20 percent of it. For an owner below the income thresholds, the net effect is a deduction worth about 80 percent of the contribution, multiplied by the marginal rate.
This interaction does not change the deadline, but it changes what the deadline is worth. An owner deciding in September whether to fund the full amount should compare the after-QBI income tax effect with the cash available. The SEP IRA vs solo 401k guide shows how a Roth deferral in a solo 401(k) can change this result.
| Item | No SEP | SEP of $33,457 |
|---|---|---|
| Qualified business income after the half SE tax deduction | $167,283 | $133,826 |
| Tentative QBI deduction at 20 percent | $33,457 | $26,765 |
| Reduction in the QBI deduction | Not applicable | $6,692 |
| Net reduction in taxable income | Not applicable | $26,765 |
| Note | Other limits ignored | Hypothetical, before other deductions |
Can a SEP deposit made after the deadline still be useful?
Yes. A deposit made after the 2026 SEP IRA contribution deadline is a contribution for the year in which it is made, so it can be deducted on the 2027 return if it fits the 2027 limits and covers eligible employees uniformly. It is not lost, only moved to a different year.
- Late for 2026: becomes a 2027 contribution.
- Limit check: counts against 2027 limits for each participant.
- Employees: the 2027 uniform rate applies, based on 2027 compensation.
- Documentation: label it clearly as a 2027 contribution.
The IRS SEP FAQ confirms that contributions not deposited by the filing due date may be deducted on the following year’s return. The deposit still has to meet all of the following year’s rules. That includes the uniform percentage for every employee eligible in 2027, which can differ from the 2026 group, and the 2027 compensation of each person.
Owners sometimes use the late deposit deliberately. An owner who missed the 2026 window but expects a strong 2027 can deposit early in 2027, start tax deferred growth sooner, and treat the deposit as a 2027 contribution. That is a legitimate use of the rule, as long as the records do not describe it as a 2026 contribution.
The worst outcome is an unlabeled deposit claimed on the 2026 return after the window closed. That overstates 2026 deductions and can also create an excess for 2027. A clear record avoids both problems.
| Question | Answer |
|---|---|
| Deductible on the 2026 return? | No |
| Deductible on the 2027 return? | Generally yes, within 2027 limits |
| Uses the 2027 limit? | Yes, $25,000 of it |
| Employees covered? | Those eligible for 2027, at a uniform rate |
| Form 5498 year | 2027 |
| Record label | 2027 employer SEP contribution |
What is a year end SEP deadline checklist for 2026?
Before December 31, 2026, decide on S corporation wages, any solo 401(k) deferral election, and Roth conversions. Before March 15 or April 15, 2027, file the extension that controls the SEP if the deposit will be late. Before the extended due date, adopt the SEP if needed, deposit, designate the tax year, and send employee notices.
- By December 31, 2026: wages, deferral elections, conversions.
- By March 15, 2027: S corporation and partnership extensions.
- By April 15, 2027: individual and C corporation extensions, and any IRA contribution.
- By the extended date: SEP adoption, deposit, and records.
The checklist turns the statutes into a calendar. Some decisions close at year end and cannot be repaired later, such as S corporation wages and solo 401(k) deferral elections. Others close on the unextended due date unless an extension is filed, which is a cheap step that preserves the SEP window. The rest close on the extended due date.
Owners who make estimated payments should line those dates up with the same calendar. The fourth quarter 2026 estimate is due January 15, 2027, and the cash needed for a large SEP contribution often competes with that payment. Our quarterly estimated tax calculator gives a rough figure.
A business that also funds health coverage for staff, such as a QSEHRA, or reimburses owner expenses through an accountable plan, usually reviews those items at the same year end meeting.
| Date | Task | Who it applies to |
|---|---|---|
| December 31, 2026 | Pay final 2026 wages and payroll deferrals | S corporation and C corporation owners |
| December 31, 2026 | Elect solo 401(k) deferrals for an existing plan | Sole proprietors and partners |
| December 31, 2026 | Complete any 2026 Roth conversion | All owners |
| January 15, 2027 | Fourth quarter estimated tax payment | Owners who pay estimates |
| March 15, 2027 | File Form 7004 or deposit the SEP | S corporations and partnerships |
| April 15, 2027 | File Form 4868 or Form 7004, or deposit the SEP; make any 2026 IRA contribution | Sole proprietors and C corporations |
| April 15, 2027 | First-year solo 401(k) deferral deadline for a new plan | Sole proprietors |
| September 15, 2027 | Extended SEP deadline; defined benefit funding deadline | Pass-through entities; defined benefit sponsors |
| October 15, 2027 | Extended SEP deadline | Sole proprietors and C corporations |
Should an owner fund the SEP before filing the return or after?
Either can work. Funding before filing removes the risk of claiming a deduction that is never deposited and keeps the records simple. Funding after filing, within a valid extension period, gives the owner more months of business cash flow. The IRS allows the later deposit, but the return must still show the planned amount accurately.
- Before filing: deduction matches a completed deposit.
- After filing: more time to see how the year develops.
- Risk of waiting: an unfunded deduction requires an amended return.
- Common middle path: extend, then file and fund together.
The IRS SEP FAQ makes the later deposit possible by stating that with an extension the deposit window runs to the end of the extension period regardless of the filing date. That does not change the accounting. The return claims a deduction for an amount the owner has committed to contribute, and the deposit has to follow before the extended due date.
Many preparers prefer a middle path. The owner files the extension by the original date, pays the estimated balance, and then files the return and makes the deposit together once the cash is available. That keeps the deposit and the deduction in step and still uses the extra months.
Owners with uneven cash flow, including seasonal Southwest Florida businesses whose strongest months are January through April, sometimes find that funding in summer is easier than funding in April. The extension makes that timing available for the SEP but not for the IRA.
| Approach | Extension needed? | Deposit date | Main risk |
|---|---|---|---|
| Fund, then file by April 15 | No | Before April 15, 2027 | Cash needed early in the season |
| Extend, fund, then file | Yes | Before the return is filed | Interest on any unpaid tax |
| Extend, file, then fund | Yes | After filing, by October 15, 2027 | Deduction claimed before funding |
| No extension, fund late | Not filed | After April 15, 2027 | Contribution moves to 2027 |
When can you take money out of a SEP IRA without a penalty?
SEP IRA withdrawals follow the ordinary IRA rules. Distributions after age 59 and a half avoid the 10 percent additional tax, and earlier distributions avoid it only if an exception in section 72(t) applies, such as disability or a series of substantially equal periodic payments. Distributions of pretax money are taxable as ordinary income in either case.
- Age: 59 and a half for the 10 percent additional tax.
- Exceptions: listed in section 72(t), including death, disability, and periodic payments.
- Income tax: pretax SEP money is taxable when distributed.
- No early lock: a SEP IRA has no plan-level restriction on withdrawals.
A SEP IRA is a traditional IRA, so IRC section 72(t) governs the 10 percent additional tax on early distributions. Publication 560 explains that SEP participants are subject to the same distribution rules as other traditional IRA owners, including required minimum distributions. A SEP cannot lock the money in the way some employer plans restrict in-service withdrawals, so the owner has access to the account at any age.
The question connects to the deadline in an unexpected way. An owner who contributes on October 14 and withdraws in November has not saved anything for retirement, and the distribution is taxable and possibly subject to the additional tax. The deadline lets an owner fund late, but the contribution still needs to be money the owner can leave invested.
Owners who are planning an early retirement schedule sometimes look at a Roth conversion ladder for access before 59 and a half. That is a separate strategy with its own five year clocks.
| Situation | 10 percent additional tax? | Income tax on pretax amounts? | Authority |
|---|---|---|---|
| Age 59 and a half or older | No | Yes | IRC 72(t) |
| Under 59 and a half, no exception | Yes | Yes | IRC 72(t) |
| Disability | No | Yes | IRC 72(t)(2)(A)(iii) |
| Substantially equal periodic payments | No, if the rules are followed | Yes | IRC 72(t)(2)(A)(iv) |
| Required minimum distributions | Not applicable | Yes | Publication 560 |
Do Roth SEP contributions follow the same deadline?
Yes. Since SECURE 2.0, an employer may let employees treat SEP contributions as Roth contributions if the custodian offers it, and the deposit deadline is still the return due date including extensions. A Roth SEP contribution is included in the participant’s income for the year, so it does not produce the deduction a pretax SEP contribution does.
- Availability: depends on the plan document and the custodian.
- Deadline: the same extended return due date.
- Tax effect: included in income rather than deducted.
- Records: the Roth designation must be made with the custodian.
The IRS SEP plan page notes that an employer may choose to accept Roth contributions but is not required to. The statutory change came in SECURE 2.0 section 601, which amended section 408 to allow Roth treatment for SEP contributions. Custodians adopted the option at different speeds, so an owner should confirm that the custodian supports it before planning around it.
The deadline does not change because the contribution is still an employer contribution to a SEP. What changes is the tax result. A pretax SEP contribution reduces taxable income, while a Roth SEP contribution is included in income and grows tax free if the Roth rules are later met. An owner deciding near the deadline is therefore choosing between a deduction now and tax free growth later, and the QBI interaction described earlier works differently.
Roth treatment also avoids adding pretax money to the pro rata calculation for a later backdoor Roth IRA, because a Roth SEP balance is not pretax IRA money.
| Feature | Pretax SEP | Roth SEP |
|---|---|---|
| Deadline | Extended return due date | Extended return due date |
| Income effect in 2026 | Deducted, lowers taxable income by $30,000 | Included in income |
| Growth | Tax deferred | Tax free if Roth rules are met |
| Counts in the pro rata rule | Yes | No |
| Availability | All SEPs | If the custodian and plan offer it |
Can a business started in 2026 still set up a SEP for 2026?
Yes. A business that began during 2026 can adopt a SEP for 2026 in 2027, up to its 2026 return due date including extensions, and contribute based on 2026 compensation or net earnings. Because eligibility looks back at prior service, most employees of a new business will not yet meet the 3 of 5 years test.
- Adoption: by the 2026 extended due date.
- Base: 2026 net earnings or 2026 W-2 wages only.
- Employees: usually not yet eligible under the 3 of 5 years test.
- Short first year: a partial year still uses the full dollar limit.
The adoption rule on the IRS SEP plan page does not depend on how long the business has existed. A first year business has the same window as an established one. The contribution is measured against the compensation the business actually generated in 2026, so a business that opened in September with a small profit has a correspondingly small SEP.
The eligibility rule usually helps new businesses. Under section 408(k)(2), an employee must have performed service in at least 3 of the immediately preceding 5 years, so a worker hired in 2026 is generally not eligible for a 2026 contribution, unless the employer chose a shorter period in its plan document. The owner can contribute for themselves while staff build service.
New owners often have a larger question about entity choice. Our guide to S corporation reasonable compensation explains how an S election changes the base for the SEP.
| Item | Amount or date |
|---|---|
| 2026 net profit | $40,000 |
| Half of self-employment tax | $2,826 |
| Net earnings for the SEP | $37,174 |
| Maximum SEP contribution | $7,435 |
| Latest adoption and deposit | April 15, 2027, or October 15, 2027 with an extension |
| Employees eligible for 2026 | Generally none, under the 3 of 5 years test |
How do the deadlines work for an owner with a W-2 job and a side business?
The SEP IRA contribution deadline for a side business follows its return, so a sole proprietor uses April 15, 2027, or October 15, 2027 with Form 4868. The contribution is based only on side business net earnings. W-2 wages do not increase it, though they share the Social Security wage base.
- Deadline: the owner’s Form 1040 due date for a Schedule C business.
- Base: side business net earnings only.
- Employer plan at the day job: does not prevent a SEP for the side business.
- Limit sharing: the day job 401(k) deferral and a side business solo 401(k) deferral share one limit.
The IRS SEP FAQ confirms that a person can set up a SEP for a self-employed business even if they participate in their employer’s retirement plan at a second job. The SEP limit for the side business is separate from the day job’s plan, because the two employers are unrelated. That differs from elective deferrals, which are limited per person across all plans.
The wage base point affects the computation. Social Security tax on self-employment income applies only to the extent the owner’s combined wages and self-employment earnings stay below the $184,500 wage base for 2026, so an owner with high W-2 wages may owe little Social Security tax on the side business. That increases net earnings slightly and therefore the SEP maximum.
Side business owners are often deciding late in the year whether the business is a hobby or a business. A SEP requires real net earnings from a trade or business, so that question comes first.
| Item | Amount |
|---|---|
| Side business net profit | $40,000 |
| Net earnings subject to SE tax | $36,940 |
| Social Security base remaining after wages | $34,500 |
| Self-employment tax | $5,349 |
| Half of SE tax | $2,675 |
| Net earnings for the SEP | $37,325 |
| Maximum SEP contribution | $7,465 |
| Deadline | April 15, 2027, or October 15, 2027 with Form 4868 |
What is the SEP deadline when a business closes during 2026?
A business that closes during 2026 can still make a SEP contribution for its final year, by the due date of its final return including extensions. The contribution is based on compensation or net earnings for the final year. Employees who were eligible during that year still need the same uniform percentage, even though they have since left.
- Final year: the SEP rules apply to the year of closing.
- Deadline: the final return’s due date, including extensions.
- Former employees: still entitled to a uniform contribution if eligible.
- No ongoing filing: a SEP generally has no termination filing with the IRS.
Corporations and partnerships that close during the year usually file a final return due earlier than the calendar year dates, because the tax year ends on the closing date. The SEP deadline follows that final return, so the window can close months before the dates in the main table. The Form 1120-S instructions and Form 1065 instructions explain the final return timing.
A sole proprietor who stops operating mid-year still files on the calendar year, so the April 15, 2027 date, or October 15 with an extension, still applies to the final year’s SEP. The base is the net earnings for the months the business operated.
The IRS SEP FAQ says that SEPs can be terminated at any time, that it is a good idea to notify employees and the financial institution, and that the IRS itself should not be notified of the termination.
| Entity | Final tax year ends | Final return due date drives the SEP deadline | Former employees covered? |
|---|---|---|---|
| Sole proprietor | December 31, 2026 | Yes, April 15, 2027 or October 15, 2027 | Yes, if eligible in 2026 |
| S corporation | Date of closing | Yes, generally earlier than the calendar date | Yes, if eligible in 2026 |
| Partnership | Date of closing | Yes, generally earlier than the calendar date | Yes, if eligible in 2026 |
| C corporation | Date of closing | Yes, generally earlier than the calendar date | Yes, if eligible in 2026 |
Does Florida have its own SEP contribution deadline?
No. Florida has no personal income tax, so there is no separate Florida SEP IRA contribution deadline. The federal deadline is the only one that matters for a Florida sole proprietor or S corporation owner. A Florida C corporation files a state corporate income tax return, but its SEP deadline is still the federal one.
- Florida individuals: no state income tax return.
- Florida S corporations: generally no state income tax.
- Florida C corporations: state corporate return, same federal SEP rule.
- Movers: a former state may still tax income earned before the move.
The federal deadline rules in section 404(h)(1)(B) apply in every state. Florida simply adds nothing on top of them for individuals. Owners who moved to Florida from a state with an income tax, and who still file a part-year return in that state, may find that the other state treats the SEP deduction under its own conformity rules for the period before the move.
Florida does have one practical deadline issue that many other states do not: hurricanes. As explained earlier, IRS disaster postponements under section 7508A can move SEP and IRA deadlines for affected Florida counties. The postponed date comes from the federal announcement, not from Florida.
Owners who relocated from a high tax state and are still settling the move should look at our guide to moving from California to Florida, which covers the last year in the former state.
| Owner | Federal SEP deadline applies? | Separate Florida deadline? | Other state issue |
|---|---|---|---|
| Florida sole proprietor | Yes | No | None if a full year resident |
| Florida S corporation owner | Yes, the corporation’s date | No | None in most cases |
| Florida C corporation | Yes | No, the state return does not change the SEP date | Florida corporate return |
| Part-year Florida resident | Yes | No | Former state’s conformity rules |
SEP IRA Contribution Deadline Help in Naples & Southwest Florida
Tax Expert Today LLC works with self-employed owners, partners, and S corporation shareholders in Naples, Florida and across Southwest Florida on retirement contribution timing. That work can include computing the maximum contribution, filing the extension that controls the deadline, and matching the deposit to the return. Results depend on each owner’s facts and plan.
- SEP IRA deadline help Naples: contribution timing and extension planning for owners in Collier and Lee counties.
- Coordination: working with the custodian or plan provider the owner has chosen.
- Scope: tax planning and return treatment, with plan documents supplied by the provider.
- Service area: an office in Naples, with clients served in all 50 states.
Our office is at 11983 Tamiami Trail N, Naples FL 34110. Call (239) 441-2005, Monday through Friday, 10 a.m. to 5 p.m. ET. Our Naples tax planning page and our tax planning services page describe how the firm works with business owners, and our business advisory services page covers the compensation and entity questions that often decide the contribution base.
Where can I get help with a SEP IRA contribution deadline in Naples, FL? Tax Expert Today LLC is based at 11983 Tamiami Trail N in Naples and works with owners on computing SEP contributions, filing the extension that keeps the deposit window open, and reporting the deduction on the right return. The firm does not recommend any particular custodian or promise any particular tax result, and results depend on the facts of each business.
| Season | Typical activity | SEP related step |
|---|---|---|
| November and December 2026 | Year end review | Set wages, elect deferrals, estimate the SEP |
| January to April 2027 | Peak season for many local businesses | File the extension if the deposit will be late |
| Hurricane season, June to November | Possible IRS disaster relief | Check any postponement announcement for Collier or Lee County |
| Summer 2027 | Slower months for many seasonal businesses | Fund the SEP within the extension window |
When to Engage a Professional
Consider professional help when the deposit will be made after the original due date, when the business has any eligible employee, when an S corporation salary decision is still open before December 31, or when a disaster postponement may apply. A missed extension or a misdated deposit can move a deduction to the wrong year.
- Before year end: wages, deferral elections, and plan choice.
- Before the original due date: the extension that controls the SEP.
- Before funding: the contribution computed on the correct base for every participant.
- After funding: the deposit record, employee notices, and return reporting.
Tax Expert Today LLC is a Naples, Florida firm of tax advisors, enrolled agents, CPAs, and attorneys serving clients in all 50 states. To discuss a SEP IRA contribution deadline, an extension, or how retirement contributions fit a broader plan for your business, contact our Naples, Florida tax planning team, review our tax planning services, or call (239) 441-2005. Readers may also find our guides to the SEP IRA vs solo 401k, profit sharing plan, safe harbor 401(k), cash balance plan for business owners, self-employed health insurance deduction, excess business loss limitation, and tax gain harvesting useful, along with the full learning center.
| Situation | Why it matters for the deadline |
|---|---|
| Deposit planned after March 15 or April 15 | Requires a timely extension for the right return |
| Business with eligible employees | Uniform contributions and notices follow the same deadline |
| S corporation owner | The wage base closes on December 31 |
| New solo 401(k) in early 2027 | Deferral and employer amounts have different dates |
| Possible disaster postponement | The announcement controls the date |
This article is general information about federal retirement plan contribution deadlines and is not tax, legal, or investment advice for any specific business or person. It does not recommend any plan provider, custodian, or investment. Statutory and regulatory references were checked against the text of IRC sections 72, 199A, 219, 401, 404, 408, 415, 430, 1402, 4972, 4973, 7503, and 7508A, Treasury Regulation sections 1.199A-3, 1.401(k)-1, and 301.7508A-1, SECURE 2.0 sections 317 and 601, IRS Notice 2025-67, Revenue Procedure 2018-58, IRS Publications 560 and 590-A, the Form 5305-SEP, Form 1065, Form 1120-S, Form 1120, and Form 7004 instructions, and published IRS guidance on November 12, 2026. Publication 560 on IRS.gov was the 2025 edition on that date, so line numbers and examples should be confirmed against the edition in effect when a return is prepared. All dollar examples, including ages, income, wages, and contribution amounts, are hypothetical illustrations prepared for this guide and are not client outcomes or predictions for any taxpayer. Tax laws apply differently to each person’s facts. Consult a qualified professional about your situation before taking any action.
Published November 12, 2026 by Dr. Pellumb Kabashi « Back to Learning Center
Have a question this article touches on?
Tax Expert Today LLC, based in Naples, Florida and serving clients across the United States.
Schedule a Consultation (239) 441-2005