
By Dr. Pellumb Kabashi, DBA, MBA, EA, CFE, CES
Founder, Tax Expert Today LLC · Tax advisors, enrolled agents, CPAs, and attorneys · Serving clients in all 50 states
Quick Answer: Georgia lottery tax is ordinary Georgia income tax, charged at the 2026 flat rate of 4.99 percent on the full prize. On prizes over $5,000 the Georgia Lottery withholds 4.99 percent for Georgia and 24 percent for federal tax, but withholding is only a deposit. Large winners often owe more federal tax, and nonresidents, groups, and annuity winners have extra filing steps. Call (239) 441-2005 for a free consultation.
What Is the Georgia Lottery Tax?
There is no separate Georgia lottery tax. A Georgia lottery prize is income, taxed by Georgia at the same 4.99 percent flat rate that applies to wages and interest in 2026, and taxed federally at ordinary rates. What most winners call the Georgia lottery tax is really the withholding taken when the prize is paid.
- State tax: Georgia income tax at the 2026 flat rate of 4.99 percent on taxable income.
- Federal tax: ordinary income tax at the winner’s own bracket, up to 37 percent.
- Withholding: a deposit against both taxes, taken only on prizes over $5,000.
- The return: where the real tax is computed and the deposit is settled.
Georgia law treats lottery proceeds like any other income. The Department of Revenue’s withholding rule, Rule 560-7-8-.39, opens by pointing to O.C.G.A. 50-27-24(a), which gives Georgia the authority to tax all proceeds of any lottery prize regardless of the amount. That phrase matters. A $600 scratcher prize is just as taxable as a jackpot. The only difference is that nothing is withheld from the small prize, so the winner has to remember it at filing time.
The rate itself comes from the general income tax statute. The Department’s Important Tax Updates page states that the Georgia income tax rate has been reduced to a flat 4.99 percent for 2026, and that the standard deduction is $15,000 for single filers, heads of household, and married people filing separately, or $30,000 for married couples filing jointly. A lottery prize is simply added to the rest of the winner’s income on a Georgia return.
This is also why several pages that rank for this question are out of date. Georgia has cut its rate on a rolling basis, from 5.49 percent to 5.39 percent, then 5.19 percent, and now 4.99 percent. A calculator still using 5.49 or 5.75 percent will overstate the Georgia withholding and the Georgia tax. On publish day for this guide, the Department’s own page and the Georgia Lottery’s FAQ both show 4.99 percent.
The federal side works the same way. The IRS says in Topic 419 that gambling winnings are fully taxable and include winnings from lotteries, raffles, and the fair market value of prizes such as cars and trips. The prize is reported as other income and taxed at the winner’s marginal rate, which can climb well above the 24 percent the Lottery withholds.
How Much Does the Georgia Lottery Withhold From a Prize?
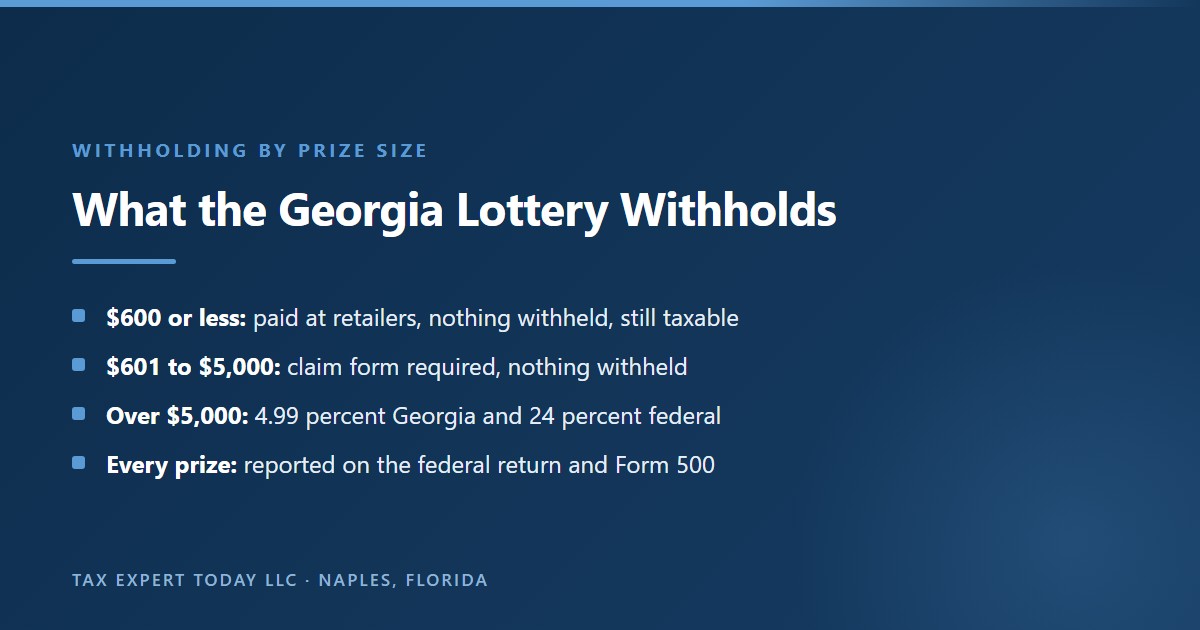
For a prize over $5,000, the Georgia Lottery withholds 4.99 percent for Georgia income tax and 24 percent for federal income tax, a combined 28.99 percent of the prize net of the ticket cost. Prizes of $5,000 or less are paid without income tax withholding, although they remain fully taxable on both returns.
- Georgia withholding: 4.99 percent, tied by rule to the maximum rate in O.C.G.A. 48-7-20.
- Federal withholding: 24 percent under IRC 3402(q) on proceeds over $5,000.
- Threshold: more than $5,000, measured after subtracting the wager.
- Applies to everyone: residents and nonresidents alike, under the Georgia rule.
The Georgia figure is not set by the Lottery. Rule 560-7-8-.39(4) says that for prize proceeds of more than $5,000 from a play with any lottery conducted by the Georgia Lottery Corporation, all such proceeds are subject to withholding in an amount equal to the maximum marginal rate in O.C.G.A. 48-7-20 multiplied by the proceeds. Because Georgia now has a single flat rate, the maximum marginal rate and the flat rate are the same number. When the General Assembly cuts the rate, the withholding follows automatically.
The federal figure comes from IRC 3402(q). Subparagraph (3)(B) covers proceeds of more than $5,000 from a wager placed in a lottery conducted by an agency of a state. Paragraph (1) sets withholding at the third lowest rate in the tax table, which is 24 percent. The IRS confirms the rate in the 2026 instructions for Form W-2G and adds a detail that surprises people: the 24 percent is figured on the whole net prize, not only on the part above $5,000.
| Net prize (after ticket cost) | Georgia withholding | Federal withholding | Still taxable? |
|---|---|---|---|
| $600 or less | None | None, unless backup withholding applies | Yes, on both returns |
| $601 to $5,000 | None | None, unless backup withholding applies | Yes, on both returns |
| $5,001 to $249,999 | 4.99 percent of the whole prize | 24 percent of the whole prize | Yes; withholding is a deposit |
| $250,000 and above, cash or annuity | 4.99 percent of each payment | 24 percent of each payment | Yes; a federal balance is common |
The Georgia Lottery’s Player FAQs state the same numbers in plain terms: Georgia state income tax of 4.99 percent and federal income tax of 24 percent are withheld from prizes of more than $5,000 at the time the prize is claimed. Its How to Claim page adds a sentence that every winner should read twice: a winner’s final tax liability may be greater or lesser than the amounts withheld.
The ticket price is subtracted first. IRC 3402(q)(4)(A) says proceeds from a wager are determined by reducing the amount received by the amount of the wager, and the Lottery’s FAQ refers to prizes net of wager or ticket cost. A $5,002 prize on a $2 ticket is $5,000 of proceeds, which is not more than $5,000, so it falls under the threshold. That edge case rarely matters in dollars, but it explains why two winners of similar prizes can see different paperwork.
Why Is Georgia Lottery Tax Withholding Only a Deposit?
Withholding is a prepayment credited against the tax computed on the annual return. The final Georgia lottery tax and federal tax depend on the winner’s total income, filing status, deductions, residency, and credits for the whole year. The Georgia Lottery says it directly: the final liability may be greater or lesser than what was withheld.
- Federal rates climb: income above the 24 percent bracket is taxed at 32, 35, or 37 percent.
- Other income stacks: wages and investment income push the prize into higher brackets.
- Deductions differ: the standard deduction or itemized deductions reduce taxable income once.
- Residency changes the answer: a nonresident’s home state may tax the prize too.
Think of the W-2G as a receipt for a deposit, not a bill. On the federal return, the prize is added to every other item of income, and the tax is computed on the total using the brackets for that year. The 24 percent withheld is then credited, along with wage withholding and any estimated payments. If the computed tax is larger, the winner pays the balance. If it is smaller, the winner receives a refund.
On the Georgia return, the same logic applies, but the gap behaves differently because Georgia has one flat rate. Withholding at 4.99 percent on a prize that is taxed at 4.99 percent tends to land close to the Georgia tax on that prize. The Georgia side can still be off when the prize is $5,000 or less and nothing was withheld, when a nonresident’s Georgia computation is prorated, or when deductions and credits change the result.
Withholding is the place where most winners stop reading, and it is exactly where most of the ranking calculators stop too. The rest of this guide covers what happens after the deposit: the forms, the two returns, estimated payments, residency, state debt set off, groups, sales of installments, losses, and what to do if the balance due is larger than expected. If you are weighing Georgia filing questions more broadly, our Georgia tax services page explains how Georgia matters are handled.
Which Georgia Lottery Prizes Have No Withholding at All?
Prizes of $5,000 or less net of the ticket cost are paid without Georgia or federal income tax withholding. That includes every prize cashed at a retailer, which is limited to $600 or less, and prizes from $601 to $5,000 claimed at a Lottery office. All of them remain taxable income on both returns.
- Retailer prizes: $600 or less, paid in cash, check, or money order with nothing withheld.
- Office prizes up to $5,000: a claim form and identification, but no income tax withheld.
- Online prizes up to $600: credited to the player’s account automatically.
- Backup withholding: 24 percent federal can apply when no correct taxpayer number is given.
The Lottery’s How to Claim page explains the tiers. Prizes of $600 or less can be claimed at any retailer, Lottery office, or by mail. Prizes over $601 must be claimed at Lottery headquarters or a district office, or mailed in with a Winner Claim Form, a government issued photo identification, and proof of Social Security number. Prizes up to $25,000 can also be claimed at the Lottery kiosks at Hartsfield-Jackson Atlanta International Airport.
Because nothing is withheld on these smaller prizes, they are the ones most often left off a return. A player who hits several $1,000 or $3,000 instant prizes in one year can accumulate a meaningful amount of untaxed income. The Lottery’s FAQ says it reports to the IRS and the Georgia Department of Revenue the names of winners of prizes above $600, so the agencies may already know about prizes that the winner has forgotten.
On the federal side, the 2026 instructions for Form W-2G note that the general reporting floor for certain information returns, including the W-2G, becomes inflation adjusted for calendar years after 2025, and they give $2,000 as the threshold for payments made in 2026. Whatever the paperwork threshold, the income rule does not change. Topic 419 says gambling winnings are fully taxable, and Georgia’s rule says all prizes are taxable regardless of the amount. A prize with no form is still income.
Backup withholding is the exception that can catch a winner off guard. The IRS instructions say a payer should backup withhold 24 percent when the winner does not furnish a correct taxpayer identification number and regular gambling withholding has not been taken. Claiming with a valid Social Security number avoids it. If it does occur, the amount is credited on the federal return like any other withholding.
What Tax Forms Does a Georgia Lottery Winner Receive?
A winner who meets the reporting threshold receives Form W-2G from the Georgia Lottery Corporation, showing the prize, the federal tax withheld, and the Georgia tax withheld. Copies go to the IRS and the Department of Revenue. Group members may complete Form 5754 so each person receives a separate W-2G for their share.
- Form W-2G: the gross prize, federal withholding, and state withholding with the payer’s state number.
- Form 5754: lists each person entitled to a share so the Lottery can issue separate forms.
- Winner Claim Form: the Lottery’s own intake form for prizes of $601 or more.
- Form G2-LP: only when a winner sells future installments to a buyer under court order.
Rule 560-7-8-.39(4) requires the Georgia Lottery Corporation to issue to the recipient a W-2G showing the amount of the lottery prize proceeds and the amount of income tax withheld, and to remit the Georgia withholding to the Commissioner of Revenue. That is why the Georgia withholding appears on the federal form. The W-2G carries both the federal amount and the state amount, along with the payer’s state identification number.
| Document | Who issues it | What it shows | Where it is used |
|---|---|---|---|
| Form W-2G | Georgia Lottery Corporation | Gross prize, federal tax withheld, Georgia tax withheld | Federal Form 1040 and Georgia Form 500 |
| Form 5754 | Completed by the person claiming for a group | Each person entitled to a share and their taxpayer number | Given to the Lottery so it can issue separate W-2Gs |
| Winner Claim Form | Georgia Lottery Corporation | Claimant identity, address, Social Security number | Required for prizes of $601 or more |
| Form G2-LP | Buyer of lottery installments | Purchase price and Georgia tax withheld on the sale | Attached to the seller’s Georgia return |
Keep the W-2G with the tax file for the year, together with the ticket copy, the claim receipt, and the bank deposit record. For an annuity prize, a new W-2G is issued for each annual payment, so a 30 payment jackpot creates a stack of forms over the years. Each one belongs to the year the payment is received.
The IRS describes Form 5754 in the About Form 5754 page as the statement used when the person receiving gambling winnings is not the actual winner or is a member of a group of winners. It lets the payer issue a W-2G to each person, which keeps each share on the right person’s return. Group claims are covered in their own section below.
How Is a Georgia Lottery Prize Reported on the Federal Return?
The full prize is reported as gambling income on the federal return, the 24 percent withheld is claimed as a payment, and the tax is computed at the winner’s own brackets. Losses can be deducted only by itemizing, only up to winnings, and from 2026 only at 90 percent of the losses under IRC 165(d).
- Income: the gross prize, plus the fair market value of any noncash prize.
- Payments: the federal amount from each W-2G, credited against the year’s tax.
- Losses: itemized only, capped at winnings, and 90 percent deductible from 2026.
- Records: a diary or similar record plus tickets and statements to support losses.
The federal treatment is the starting point for Georgia because Georgia begins its computation with federal adjusted gross income. If the prize is missing or misstated on the federal return, the Georgia return will be wrong in the same way. That is why a winner should settle the federal reporting first, then build the Georgia return from it.
Topic 419 explains the rules for casual gamblers who are not in the trade or business of gambling. Gambling losses can be deducted only on Schedule A as itemized deductions, and the amount deducted cannot exceed the gambling income reported. A winner who takes the standard deduction gets no deduction for losing tickets at all, which is a common misunderstanding among people who bought many tickets before the winning one.
From 2026, the cap tightened. The current text of IRC 165(d) says the deduction for losses from wagering transactions is equal to 90 percent of the losses for the year and is allowed only to the extent of the gains. A person who wins and loses the same amount can therefore still have taxable gambling income. The loss section later in this guide works through a hypothetical example and the Georgia conformity question.
| Federal item | Rule | Authority |
|---|---|---|
| Prize included in income | Fully taxable, including noncash prizes at fair market value | IRS Topic 419 |
| Withholding rate | 24 percent of net proceeds over $5,000 from a state lottery | IRC 3402(q)(1) and (3)(B) |
| Backup withholding | 24 percent when no correct taxpayer number is furnished | Instructions for Form W-2G |
| Loss deduction | Itemized only, 90 percent of losses, limited to gains | IRC 165(d), Topic 419 |
| Withholding timing for penalties | Treated as paid in equal parts on each installment date unless actual dates are shown | IRC 6654(g)(1) |
The last row in that table is a planning point most winners never hear about, and it is covered in the estimated tax section below. Federal reporting is outside the Georgia Department of Revenue’s reach, but it drives every Georgia number, so it is worth getting right before the Georgia return is prepared.
How Is a Georgia Lottery Prize Reported on Georgia Form 500?
A Georgia resident reports the prize through federal adjusted gross income on Form 500, applies the standard or itemized deduction, computes tax at 4.99 percent, and claims the Georgia withholding shown on the W-2G. A nonresident uses Schedule 3 of Form 500 to tax only Georgia source income, which includes Georgia lottery winnings.
- Starting point: federal adjusted gross income, which already includes the prize.
- Deduction: $15,000 single or $30,000 joint for 2026, or itemized amounts from federal Schedule A.
- Withholding credit: the Georgia amount and the Lottery’s state payer number from the W-2G.
- Nonresidents: Schedule 3 allocates income so Georgia taxes only its share.
Georgia does not have a separate lottery schedule. The prize flows from the federal return into Form 500 as part of federal adjusted gross income, and the Georgia computation runs from there. Georgia then subtracts either the Georgia standard deduction or Georgia itemized deductions. The Department’s form instructions tie Georgia itemized deductions to the itemized deductions used in computing federal taxable income, with Georgia specific adjustments, so a winner who takes the federal standard deduction generally has no gambling loss deduction to carry to Georgia either.
The Georgia withholding is reported in the withholding section of Form 500, using the state amount and the payer’s Georgia identification number from the W-2G. Leaving it off is a common way to overpay. Entering it without the matching W-2G data is a common way to trigger a Department letter asking for support.
| Step on Form 500 | Resident winner | Nonresident winner |
|---|---|---|
| Income | Federal adjusted gross income, which includes the prize | Federal adjusted gross income, then Schedule 3 to isolate Georgia source income |
| Lottery prize | Taxed in full | Taxed as Georgia source income |
| Deduction | Georgia standard or itemized deduction | Deductions prorated by the Schedule 3 ratio |
| Tax | 4.99 percent for 2026 | 4.99 percent on the Georgia share |
| Withholding | Georgia amount from the W-2G | Georgia amount from the W-2G |
The Department’s Residency Filing Requirements page lists Georgia lottery winnings by name as an example of Georgia source income, next to wages, rents, and flow through income. Nonresidents who receive income from Georgia sources and are required to file a federal return must file Form 500. The nonresident computation is explained in more detail below and in our guide to the Georgia part year resident tax return, which uses the same Schedule 3 mechanics.
Timing follows the federal return. Form 500 is generally due on the federal due date, and a Georgia extension extends the time to file but not the time to pay, as our guide to Georgia Form IT-303 explains. A winner who expects a Georgia balance should pay it by the original due date even when the return itself is extended.
How Large Is the Federal Gap Between Withholding and Tax?
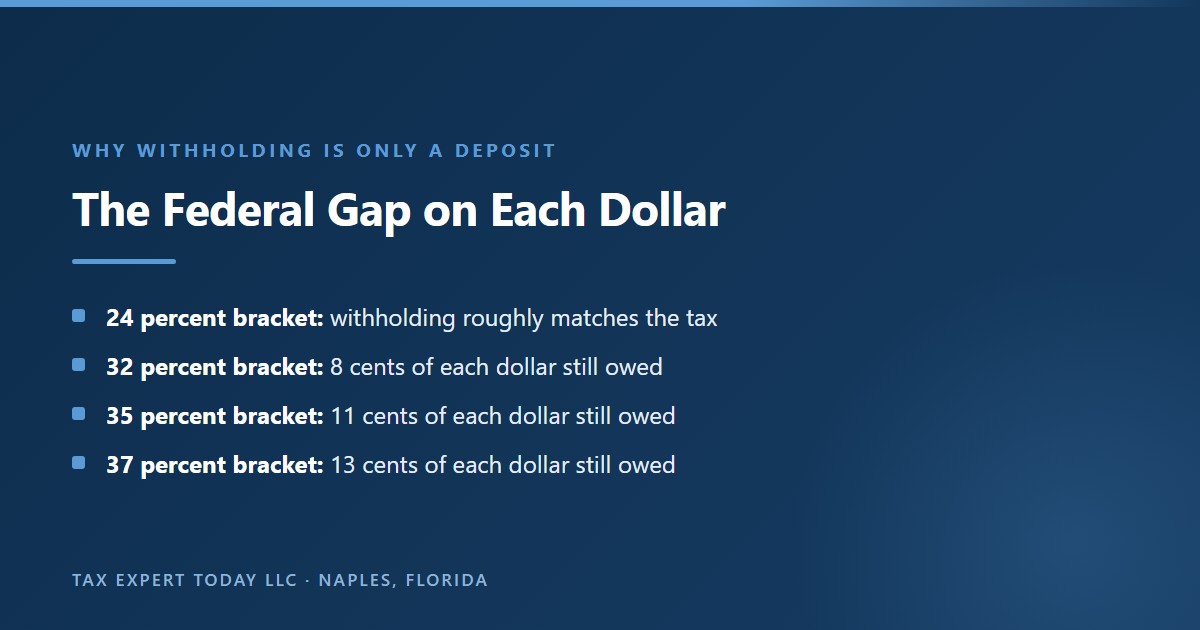
The federal gap is the difference between the 24 percent withheld and the winner’s actual marginal rate on the prize. Income taxed in the 32, 35, or 37 percent brackets leaves 8, 11, or 13 cents of every such dollar unpaid. On a large prize, that difference can be substantial and is due with the return.
- 24 percent bracket: withholding roughly matches the tax on that slice of income.
- 32 percent bracket: 8 cents of each dollar remains unpaid.
- 35 percent bracket: 11 cents of each dollar remains unpaid.
- 37 percent bracket: 13 cents of each dollar remains unpaid.
The gap is easiest to see one bracket at a time. The table below shows the shortfall per $100,000 of prize income that lands in each federal bracket. It is hypothetical math, not a computation of any person’s tax, and the bracket thresholds for a given year come from the IRS inflation adjustments for that year.
| Federal bracket the prize income falls in | Tax on $100,000 in that bracket | Withheld at 24 percent | Hypothetical shortfall |
|---|---|---|---|
| 24 percent | $24,000 | $24,000 | $0 |
| 32 percent | $32,000 | $24,000 | $8,000 |
| 35 percent | $35,000 | $24,000 | $11,000 |
| 37 percent | $37,000 | $24,000 | $13,000 |
Consider a hypothetical single filer who takes a $1,000,000 cash prize. The Lottery withholds $240,000 for federal tax and $49,900 for Georgia tax. Most of a prize that size will be taxed in the 35 and 37 percent brackets, so the federal tax on the prize will be well above $240,000. The exact figure depends on the year’s brackets, the winner’s other income, and deductions, but a six figure federal balance at filing time would not be unusual on a prize of that size.
The gap shrinks or grows with the rest of the return. A retiree with modest income who wins $20,000 may find the 24 percent withholding exceeds the tax on the prize and receive a federal refund. A high earner who wins the same $20,000 may owe more, because the prize is added to a salary already taxed at 32 or 35 percent. Withholding does not know about the winner’s other income. The return does.
The money to pay the balance should be set aside the day the prize is deposited. Many large winners place the estimated federal shortfall in a separate account before spending anything. The estimated tax section below explains when the balance must be paid to avoid an underpayment penalty, which is often earlier than the April filing deadline.
Does Georgia Lottery Tax Withholding Cover the Georgia Tax?
Often it comes close, because Georgia withholds 4.99 percent and taxes income at a flat 4.99 percent in 2026. The Georgia lottery tax can still come out higher or lower than the amount withheld when the prize was $5,000 or less, the winner is a nonresident, other income or deductions change taxable income, or credits apply.
- Small prizes: nothing withheld, so the full 4.99 percent is due with the return.
- Deductions: the standard deduction is applied once, against all income combined.
- Nonresidents: Schedule 3 proration can change the Georgia tax on the prize.
- Rate changes: an installment paid in a year with a different rate follows that year’s rate.
Unlike the federal side, Georgia has no higher brackets for a large prize to climb into. A $1,000,000 prize and a $10,000 prize are both taxed at 4.99 percent. That is why the Georgia withholding is a reasonable approximation for many winners. The table below shows where the Georgia figure tends to land.
| Situation | Georgia withheld | Likely Georgia result on the prize |
|---|---|---|
| Resident, prize over $5,000, other income already uses the standard deduction | 4.99 percent | Close to the withholding |
| Resident, prize of $5,000 or less | None | Up to 4.99 percent of the prize due with the return |
| Resident with little other income, prize over $5,000 | 4.99 percent | Possible refund, because the standard deduction reduces taxable income |
| Nonresident, prize over $5,000 | 4.99 percent | Depends on the Schedule 3 computation; refund or balance possible |
| Annuity installment in a later year | The rate in effect when paid | Taxed at that year’s rate |
The case that catches people is the string of mid sized prizes. A player who wins $4,000, $3,000, and $2,500 in one year has $9,500 of income with no Georgia withholding at all, because none of the prizes crossed $5,000. At 4.99 percent, that is roughly $474 of Georgia tax that has to come from somewhere. Add the federal tax on the same prizes, and the balance is a surprise at filing time.
The Georgia Lottery reports winners above $600 to the Department, so an omitted prize may produce a proposed assessment later. If that happens, the cleanest fix is usually an amended return, discussed near the end of this guide. For winners who want to see how Georgia withholding fits into the broader employer and payer system, our guide to Georgia withholding tax covers the payer side.
Do Large Winners Need to Make Estimated Tax Payments?
Often yes, on the federal side. When withholding will not cover the year’s tax, the IRS expects quarterly estimated payments, and a penalty can apply to the shortfall. A safe harbor based on the prior year’s tax, 110 percent when prior year adjusted gross income exceeded $150,000, can prevent the penalty even if a balance remains.
- Federal installments: 25 percent of the required annual payment, four times a year.
- Required annual payment: the lesser of 90 percent of this year’s tax or the prior year safe harbor.
- Higher income safe harbor: 110 percent of last year’s tax when prior AGI exceeded $150,000.
- Withholding timing: treated as paid evenly through the year unless actual dates are shown.
The rules are in IRC 6654. Under subsection (d), each required installment is 25 percent of the required annual payment, which is the lesser of 90 percent of the tax shown on the return for the year or 100 percent of the tax shown on the prior year’s return. If the prior year’s adjusted gross income exceeded $150,000, or $75,000 for married filing separately, the prior year figure becomes 110 percent.
The prior year safe harbor is the most useful tool for a winner. Because last year’s tax was computed before the prize, paying 100 or 110 percent of it through withholding and estimated payments can avoid the federal underpayment penalty for the prize year, even though a large balance is still due in April. The balance itself is not forgiven, only the penalty.
Subsection (g)(1) adds a timing rule that works in a winner’s favor. Federal income tax withheld is deemed a payment of estimated tax, and an equal part of it is deemed paid on each due date for the year, unless the taxpayer shows the actual withholding dates. A winner who claims a prize in November and has 24 percent withheld is treated, by default, as though that withholding had been paid in four equal parts across the year. That can cover earlier installments that would otherwise look late.
The IRS Publication 505 walks through the worksheets. Because the penalty is computed installment by installment, a winner who claims a prize early in the year may need to make larger payments for the remaining quarters, while a winner who claims late in the year may rely on the withholding rule above. A professional can run both the regular and the annualized methods before choosing.
What Are the Georgia Estimated Tax Rules for a Lottery Winner?
Georgia requires estimated payments on Form 500-ES when expected gross income exceeds exemptions and deductions plus $1,000 of income not subject to withholding. A prize over $5,000 already has Georgia tax withheld, but smaller prizes, other income, and installments may still trigger the requirement. Underpayments are measured on Form 500-UET.
- Who must pay: those expecting over $1,000 of income not subject to Georgia withholding, beyond deductions.
- Due dates: April 15, June 15, September 15, and January 15 of the next year.
- Penalty form: Form 500-UET, Underpayment of Estimated Tax by Individual or Fiduciary.
- Exception: additional withholding arranged with an employer can replace estimated payments.
The instructions printed with the 2025 Form 500-ES say each individual subject to Georgia income tax who reasonably expects gross income for the year to exceed applicable exemptions, plus estimated deductions, plus $1,000 of income not subject to withholding, must file estimated tax. Payment in full can be made with the first installment or in equal installments on April 15, June 15, September 15, and the following January 15.
For a resident who wins a single prize over $5,000, Georgia withholding at 4.99 percent usually takes care of most of the Georgia tax on that prize, so a separate Georgia estimate may not be needed. The requirement becomes relevant when the winner has several prizes under the $5,000 threshold, sells a winning ticket share or installments in a way that is not fully withheld, or has investment income from the prize money in later years.
| Estimated tax item | Federal | Georgia |
|---|---|---|
| Form | Form 1040-ES | Form 500-ES |
| Due dates | April 15, June 15, September 15, January 15 | April 15, June 15, September 15, January 15 |
| Trigger | Tax not covered by withholding and credits | More than $1,000 of income not subject to withholding, beyond exemptions and deductions |
| Penalty computation | Form 2210 under IRC 6654 | Form 500-UET |
| Prize withholding counts? | Yes, deemed paid evenly unless actual dates are used | Yes, Georgia withholding is credited on Form 500 |
The Department posts the current Form 500-UET for tax years beginning on or after January 1, 2025. The 500-ES instructions warn that failure to pay installments may result in additional charges as a penalty. Our detailed guide to Georgia Form 500-ES covers the Georgia worksheets, and the Georgia estimated tax penalty calculator can help estimate the penalty exposure for a given payment pattern.
How Does the Cash Option Compare With the Annuity for Georgia Lottery Tax?
The cash option puts the whole prize into one tax year, which pushes much of it into the 37 percent federal bracket. The annuity spreads income over 30 payments, so each year’s payment is taxed in that year at that year’s rates. Georgia taxes both at its flat rate, so the federal brackets drive most of the difference.
- Cash option: one payment, one tax year, one large federal balance risk.
- Annuity: 30 payments over 29 years, each taxed when received.
- Georgia: 4.99 percent in 2026 on either choice, with later rates applying to later payments.
- Election window: 60 days from filing the claim to choose cash or annuity.
The Lottery’s FAQ explains the mechanics. Jackpots for Mega Millions and Powerball are advertised at the estimated 30 year annuity value. If the winner chooses the annuity, the Lottery buys United States Treasury securities that mature annually and pays the prize in 30 payments over 29 years. If the winner chooses the cash option, the Lottery pays the amount it would have invested in one payment. Both options have federal and state taxes deducted.
From a federal tax view, the trade off is between brackets and certainty. A cash winner pays most of the tax at the highest federal rate in one year, but knows the rules that apply. An annuity winner spreads income across many years, which can keep more of each payment in lower brackets, but each payment is exposed to whatever federal and Georgia rates apply in its year. Georgia’s rate has fallen several times in recent years, but nobody can promise the direction of future rates.
| Factor | Cash option | Annuity |
|---|---|---|
| Tax year of income | The year the lump sum is received | Each year a payment is received |
| Federal bracket exposure | Most of the prize in the highest bracket | Each payment stacked on that year’s other income |
| Georgia rate | 4.99 percent in 2026 | The rate in effect in each payment year |
| Residency | Fixed at the year of receipt | Georgia source income every year, even after a move |
| Withholding | 24 percent federal and 4.99 percent Georgia on the lump sum | The same rates on each payment |
| Estate planning | Cash is in the estate at death | The remaining payments have a value that can be included in the estate |
The residency row is the one most winners miss. An annuity winner who moves out of Georgia does not leave the Georgia lottery tax behind, because Georgia lottery winnings are Georgia source income. That issue has its own section below. The estate row also deserves attention. Georgia has no estate or inheritance tax, as our guide to Georgia inheritance tax explains, but the federal estate tax can reach a large prize, and the value of unpaid annuity installments can be part of a federal estate.
The choice is personal and fact dependent. Age, health, other income, spending discipline, investment plans, and a possible move all matter. This guide does not recommend either option; it explains the tax mechanics that should be part of the decision.
When Is a Georgia Lottery Prize Taxed: the Drawing, the Claim, or the Payment?
For a cash basis individual, the prize is generally income when it is received. Federal law also says that a qualified cash option exercisable within 60 days does not, by itself, make the whole prize taxable at once. Georgia gives 180 days to claim draw game prizes, so the claim date can affect the tax year.
- Annuity payments: taxed in the year each payment is received.
- Cash option rule: IRC 451(j) disregards an option exercisable within 60 days.
- Claim deadline: 180 days after the draw for draw games; 90 days after the game ends for instant tickets.
- Timing caution: constructive receipt questions are fact specific and should be reviewed first.
Section 451(j) of the Internal Revenue Code, redesignated from 451(h), deals with cash options for qualified prizes. For an individual on the cash method, a qualified prize option is disregarded in determining the tax year in which any portion of the prize is includible. A qualified prize option is one that entitles the person to a single cash payment instead of the prize and is exercisable not later than 60 days after the person becomes entitled to the prize.
The Georgia Lottery’s rules line up with that window. Its FAQ says Mega Millions, Powerball, and Millionaire for Life players do not choose cash or annuity at purchase; jackpot winners have 60 days from filing a claim to elect cash or annuity. Choosing the annuity within that window does not cause the winner to be taxed on the whole cash value in the first year. Choosing the cash option means the lump sum is income in the year it is received.
The claim date itself is a separate question. Draw game tickets are valid for 180 days after the draw date and instant tickets for 90 days after the game ends, according to the Lottery’s How to Claim page. A ticket won in late December could be claimed in January. Whether that moves the income into the next year depends on the facts, because the doctrine of constructive receipt looks at whether the money was available without substantial restriction. A winner who wants to rely on timing should have the facts reviewed before claiming, not afterward.
Timing also affects Georgia. Each year’s Georgia rate applies to the income of that year. A prize received in 2026 is taxed at 4.99 percent; a prize received in a later year is taxed at the rate for that year. The Georgia withholding at claim follows the rate in effect at that time.
Do Nonresidents Owe Georgia Lottery Tax?
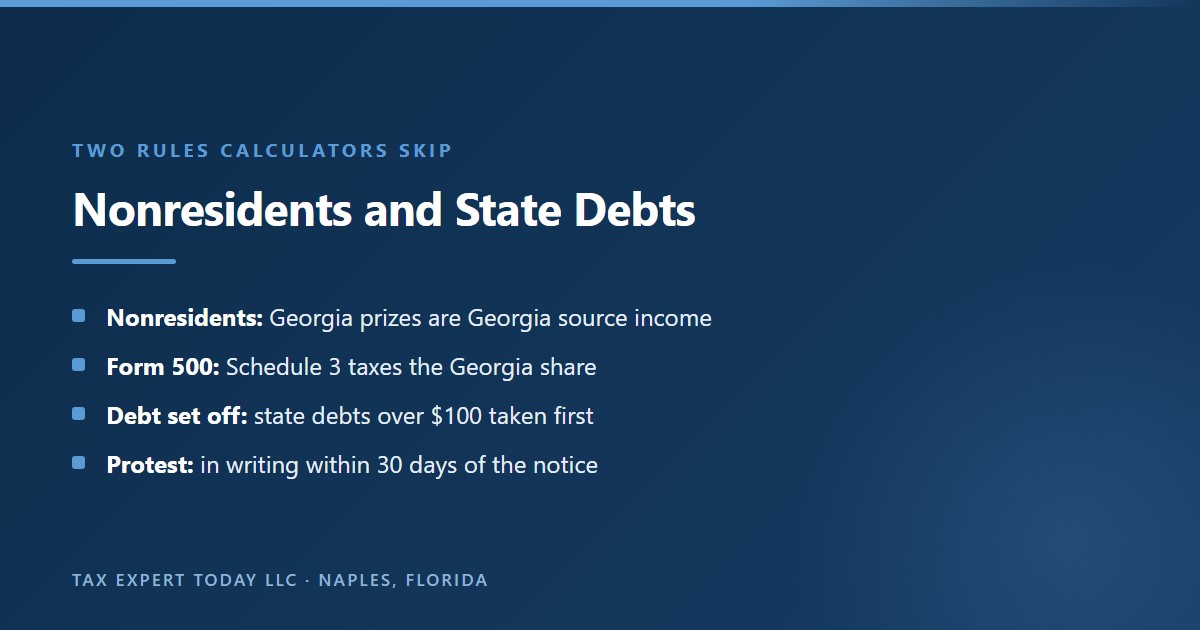
Yes. The Department of Revenue lists Georgia lottery winnings as Georgia source income, and a nonresident with Georgia source income who must file a federal return must also file Georgia Form 500. The Lottery withholds 4.99 percent from a nonresident’s prize over $5,000, and the nonresident’s home state may also tax it.
- Georgia filing: Form 500 with Schedule 3, reporting the prize as Georgia source income.
- Withholding: the same 4.99 percent and 24 percent as residents, under the same rule.
- Home state: may tax the prize as resident income and may credit the Georgia tax.
- No income tax states: residents of Florida, Tennessee, or Texas owe only Georgia and federal tax.
The Department’s FAQ for residents, nonresidents, and part year residents says nonresidents who work in Georgia or receive income from Georgia sources and are required to file a federal income tax return must file a Georgia income tax return, and it gives Georgia lottery winnings as an example of Georgia source income. The small employee exception in the same FAQ applies only to wages, not to lottery winnings.
Rule 560-7-8-.39 is written for both residents and nonresidents. Its heading for paragraph (4) is withholding from the proceeds paid to a Georgia resident or nonresident, and the withholding is the same. On the nonresident’s Georgia return, Schedule 3 separates Georgia source income from income from everywhere, and the Georgia tax is computed on the Georgia portion. The Georgia withholding from the W-2G is then credited.
| Winner’s situation | Georgia return | Home state return |
|---|---|---|
| Georgia resident, Georgia Lottery prize | Form 500, taxed in full | Not applicable |
| Florida resident, Georgia Lottery prize | Form 500 with Schedule 3, prize taxed as Georgia source income | Florida has no personal income tax |
| Resident of a state with an income tax, Georgia Lottery prize | Form 500 with Schedule 3 | Prize usually taxed as resident income; a credit for Georgia tax may be available under that state’s rules |
| Georgia resident, another state’s lottery prize | Form 500, taxed in full, with a possible credit for the other state’s tax | Nonresident return in the state that paid the prize, if that state taxes it |
| Part year resident | Form 500 with Schedule 3, allocation by residency period and source | The other state’s part year rules apply |
The Lottery’s FAQ also notes that online play through the Georgia Lottery’s website or app is limited to players located within Georgia. A nonresident who wins online therefore played from inside Georgia, and the prize is a Georgia Lottery prize like any other.
Does a Florida Resident Owe Georgia Tax on a Georgia Lottery Prize?
Yes. A Florida resident who buys a winning Georgia Lottery ticket on a trip north owes Georgia income tax on the prize as Georgia source income and must file Georgia Form 500. Florida has no personal income tax, so the Georgia lottery tax and federal tax are the only income taxes on the prize.
- Georgia: 4.99 percent withheld on a prize over $5,000; Form 500 with Schedule 3 settles it.
- Federal: the prize is reported on the federal return like any other winner’s.
- Florida: no state personal income tax return is required for the prize.
- Small prizes: nothing withheld under $5,000, but Georgia still taxes the prize.
This is the question Southwest Florida residents ask us most often about Georgia lottery tax. Many Naples and Fort Myers residents spend summers in the North Georgia mountains or drive through Georgia on the way to family, and lottery tickets are a common impulse purchase on those trips. The Department of Revenue treats the winnings as Georgia source income without any exception for visitors.
The nonresident computation usually works out simply for a Florida resident. Because Florida has no income tax, there is no credit for taxes paid to another state to coordinate. The Georgia return taxes the Georgia source portion of income, and the 4.99 percent withholding is credited against it. Whether the final Georgia figure comes out above or below the withholding depends on the Schedule 3 proration of deductions and the rest of the return.
Two practical points matter. First, a prize under $5,000 has no Georgia withholding, so a Florida resident who wins $3,000 on a scratcher in Blue Ridge still owes Georgia tax on it and is still required to file Form 500 if a federal return is required. Second, the Georgia return should be filed even if the Georgia withholding seems to cover the tax, because filing is how the withholding is credited and how any refund is claimed. For more on how a Florida residence interacts with state filing, see our Naples tax planning page.
What Happens if a Georgia Lottery Annuity Winner Moves Out of Georgia?
The move does not end the Georgia lottery tax. The Department lists Georgia lottery winnings as Georgia source income with no residency exception, so each annual installment paid by the Georgia Lottery after the move should be expected to remain reportable to Georgia on a nonresident Form 500, with Georgia withholding continuing on each payment over $5,000.
- Georgia: nonresident Form 500 each year an installment is received.
- New home state: may also tax the installment as resident income.
- Credits: the new state’s own rules decide whether Georgia tax is credited.
- Florida move: leaves only Georgia and federal tax on the installments.
Some winners assume that moving to a state without an income tax will eliminate state tax on the remaining payments. For a Georgia Lottery prize, the source rule points the other way. The prize comes from a Georgia lottery and is listed by the Department as Georgia source income, so the installment remains Georgia income even after the winner becomes a Florida or Tennessee resident.
The year of the move is a part year year. The winner files Form 500 as a part year resident, allocating income between the Georgia residency period and the nonresident period, and the installment received in that year is Georgia source income either way. Our guide to the Georgia part year resident tax return covers the allocation.
For a move to a state that does tax income, the outcome depends on that state’s rules. Most income tax states tax their residents on all income and give a credit for income tax paid to another state on income sourced there, but the details vary. A winner planning a move should have the expected tax in both states computed for at least one installment year before the move, not after.
How Does a Georgia Resident Report a Prize From Another State’s Lottery?
A Georgia resident is taxed by Georgia on income from all sources, so a prize from another state’s lottery is taxable on the Georgia return. If the paying state also taxed the prize, Georgia generally allows a credit for income tax paid to another state on that income, subject to limits computed on Form 500.
- Georgia: the prize is included in federal adjusted gross income and taxed at 4.99 percent.
- Other state: may require a nonresident return and withhold its own tax.
- Credit: Georgia’s credit for tax paid to another state, limited to the Georgia tax on that income.
- Multistate games: a ticket bought in another state is that state’s prize, even for Powerball.
Georgia taxes residents on worldwide income. The credit for taxes paid to other states, found in O.C.G.A. 48-7-28, is designed to prevent the same income from being fully taxed twice. As a general matter it cannot exceed the Georgia tax attributable to the income taxed by the other state, and the IT-511 booklet explains the computation and the documentation the Department expects with the claim.
Multistate games add one wrinkle. Powerball and Mega Millions are sold in many states, but each prize is paid by the lottery of the state where the ticket was bought. A Georgia resident who buys a Powerball ticket in South Carolina while traveling has a South Carolina lottery prize, paid and withheld under South Carolina’s rules. The Georgia return then picks up the prize, and the credit coordinates the two states.
The reverse case is covered by the residency table above. A resident of another income tax state who wins in Georgia files a Georgia nonresident return and looks to the home state’s credit rules. In every combination, the federal return comes first, and both state returns build from it.
How Are Foreign Nationals Taxed on a Georgia Lottery Prize?
A nonresident alien who wins a Georgia Lottery prize is generally subject to 30 percent federal withholding under IRC 1441 instead of the 24 percent rate, unless a tax treaty provides otherwise. Georgia withholds its 4.99 percent under the same rule as for other winners, and a Georgia nonresident return may still be required.
- Federal rate: generally 30 percent on gambling winnings of nonresident aliens.
- Federal return: Form 1040-NR with Schedule NEC, according to IRS Topic 419.
- Losses: nonresident aliens other than residents of Canada generally cannot deduct gambling losses.
- Georgia: 4.99 percent withheld on a prize over $5,000; Form 500 may be required.
IRC 3402(q)(2) says the 24 percent regular gambling withholding does not apply to a payment to a nonresident alien that is subject to withholding under IRC 1441. Instead, the payer applies the nonresident alien withholding rules, generally 30 percent unless a treaty reduces the rate. Topic 419 says nonresident aliens report United States source gambling winnings on Form 1040-NR with Schedule NEC and generally cannot deduct gambling losses unless they are residents of Canada.
Residency for federal purposes is its own test. A green card holder or a person who meets the substantial presence test is a resident alien for federal purposes and is treated like a citizen. A visitor on a short trip is usually a nonresident alien. The Georgia definitions in O.C.G.A. 48-7-1 are separate, and a person can be a nonresident for both systems or a resident for one and not the other.
Because treaties, visa status, and identification requirements interact here, a foreign national winner should have the federal and Georgia filings reviewed before claiming a large prize. The Lottery requires a Social Security number or other proof of identity at claim, and the federal withholding that applies depends on the documentation provided.
Can Georgia Take Part of a Lottery Prize for Debts Owed to the State?
Yes. Under O.C.G.A. 50-27-53, state agencies can list people who owe them more than $100, and the Georgia Lottery must withhold those debts from the prize. State taxes come first, delinquent child support second, and other judgments and liens after that. The full debt can be taken, not just a garnishment sized portion.
- Debt floor: debts of more than $100 owed to a claimant agency.
- Lien: the agency list is a valid lien on the debtor’s lottery winnings.
- Order: state taxes, then delinquent child support, then other judgments and liens by date.
- Retailer prizes: the Lottery is not required to deduct debts from prizes paid by retailers.
The statute is direct. O.C.G.A. 50-27-53(a) lets any claimant agency submit a list of persons owing debts in excess of $100, and the full amount of the debt is collectable from any lottery winnings without regard to the limits that apply to garnishment. The list is a valid lien on the winnings of every debtor named in it. Subsection (c) ranks the liens: taxes due the state first, delinquent child support second, and all other judgments and liens in order of the date entered or perfected.
The Lottery’s own pages describe how the checks work in practice. Its How to Claim page says state owed debts in excess of $100 for Child Support Services, the Department of Education, and the Department of Revenue are deducted from prizes under the Lottery for Education Act. Its FAQ adds that the Lottery is required to check for outstanding child support on prizes of $2,500 and above, and for student loans and state taxes on prizes of $5,000 and above, net of the ticket cost.
| Debt type | Lien rank under 50-27-53(c) | Prize level checked, per the Lottery’s FAQ |
|---|---|---|
| Taxes due the State of Georgia | First | Prizes of $5,000 and above |
| Delinquent child support | Second | Prizes of $2,500 and above |
| Student loans owed to a state agency | With other debts, by date | Prizes of $5,000 and above |
| Other judgments and liens of claimant agencies | Third, in date order | As listed by the agency |
The tax effect of a set off is easy to misread. When the Lottery sends part of a prize to the Department of Revenue for an old tax debt, the winner still received the whole prize for income tax purposes. The W-2G shows the gross prize, and the full amount is income. The set off simply paid a debt with part of it. A winner who expected cash and instead received a reduced check should still report the full prize.
A set off for Georgia tax also changes the old balance. A winner with an older Georgia assessment or a payment plan should confirm with the Department how the set off was applied, by year and by type, before the next payment is due. Our guide to the Georgia Department of Revenue payment plan explains how existing plans and balances are tracked.
How Do You Protest a Lottery Debt Set Off in Georgia?
The Georgia Lottery must notify the winner of the withholding and the reason. If the winner protests in writing within 30 days of the notice, the Lottery files an interpleader action in the superior court of the county where the debtor lives and pays the disputed sum into the court. Without a timely protest, the funds go to the agency.
- Notice: by certified mail or statutory overnight delivery, or by hand at an in person claim.
- Deadline: a written protest within 30 days of the notice.
- Court: interpleader in the superior court of the debtor’s county of residence.
- No protest: the Lottery pays the withheld funds to the claimant agency.
Subsection (b) of 50-27-53 sets the procedure. The Lottery withholds the winnings subject to the lien and sends notice of the action and the reason. If the winner claims in person, the notice is given by hand at that time. If the debtor does not protest in writing within 30 days of the notice, the Lottery pays the funds to the claimant agency. If the debtor does protest within 30 days, the Lottery files an action in interpleader in the superior court of the county in which the debtor resides, pays the disputed sum into the registry of the court, and notifies the agency and the debtor.
A protest makes sense when the debt is wrong, already paid, belongs to someone else with a similar name, or is the subject of an open appeal. For a disputed Georgia tax debt, the underlying question is whether the assessment itself is correct. That is decided under the Georgia tax appeal rules, not by the Lottery. Our guide to the Georgia Tax Court, which replaced the Georgia Tax Tribunal, explains the protest and petition deadlines for Georgia tax assessments.
The 30 day clock is short, and it starts with the notice, not with the end of the claim process. A winner who receives a reduced prize with a set off notice should calendar the 30th day at once. Child support disputes run through the Division of Child Support Services and the courts that issued the order, and those questions belong with a family law attorney.
How Should a Group or Office Pool Claim a Georgia Lottery Prize?
The Georgia Lottery lets a group designate one person or legal entity to receive the prize, or, for prizes of $5,001 or more, pay individual shares of $601 or more to up to 25 members. Paying each member directly, with Form 5754 behind it, keeps each share on the right person’s tax return from the start.
- Option 1: one designated individual or a legal entity claims the whole prize.
- Option 2: individual payments to up to 25 members on prizes of $5,001 or more.
- Federal paperwork: Form 5754 lists each person so each receives a W-2G.
- Agreement: the Lottery does not structure pools; members should document shares in advance.
The Lottery’s FAQ describes both paths. It says it cannot advise on structuring lottery pools because they are arrangements between private parties. Prizes may be claimed by a single legal entity, such as a corporation, partnership, or trust. Groups, families, clubs, or organizations can designate one individual or legal entity to receive a prize payment, or if the prize is $5,001 or greater, individual prize payments of $601 or greater can be made to each group member, up to 25 members.
| Claim method | Who receives the W-2G | Main tax risk |
|---|---|---|
| Individual payments to each member, up to 25 | Each member, for their share | Low, if the shares match the written pool agreement |
| One member claims, Form 5754 filed | Each person listed on Form 5754 | Low to moderate; depends on accurate shares and taxpayer numbers |
| One member claims, no Form 5754 | The claimant, for the whole prize | High; the claimant reports the whole prize and transfers may look like gifts |
| A partnership, LLC, or trust claims | The entity | Depends on the entity’s tax classification and its agreement |
The IRS instructions for Form W-2G explain that if the person receiving the winnings is not the actual winner or is a member of a group of winners, Form 5754 is used so the payer can issue a W-2G to each person entitled to a share. The form asks for each person’s name, address, taxpayer identification number, and share. Withholding is then applied to each share.
The weak point in most office pools is documentation. A short written pool agreement signed before the drawing, listing each member and their share, is strong evidence that the prize belonged to the group from the start. Without it, a single claimant who later pays coworkers may have a hard time showing that those payments were their shares and not gifts.
What Happens if One Person Claims for a Group and Then Shares the Money?
If one person claims the whole prize without Form 5754, that person receives the W-2G for the entire amount and reports it. Later payments to other members may be treated as gifts unless the person can show the others owned their shares before the claim. A federal gift tax return may then be required, although Georgia has no gift tax.
- Income: reported by whoever receives the W-2G, unless corrected with proof of ownership.
- Gifts: transfers to others above the annual exclusion may require federal Form 709.
- Georgia: no Georgia gift tax and no Georgia estate or inheritance tax.
- Evidence: a signed pool agreement predating the drawing is the strongest support.
The problem arises after the fact. A family member claims a jackpot alone because it seemed simpler, then distributes shares to siblings. If there was no agreement before the drawing, the transfers can look like gifts from the claimant, who has already been taxed on the whole prize. Each transfer above the federal annual gift exclusion may require a federal gift tax return, and large transfers use up part of the claimant’s lifetime exemption.
Where a valid pool agreement did exist, the claimant may be able to show that they received the other members’ shares as an agent, not as owner. Form 5754 is the routine way to document that at claim. When it was not used, correcting the reporting later is possible in some cases, but it requires evidence and careful handling on several returns.
Georgia does not add a separate layer here. Georgia has no gift tax, and as our guide to Georgia inheritance tax explains, no estate or inheritance tax either. The Georgia question is simply who reports the lottery income on Form 500, and that follows the federal answer.
Can a Trust or LLC Claim a Georgia Lottery Prize?
The Georgia Lottery’s FAQ says prizes may be claimed by a single legal entity, such as a corporation, partnership, or trust. The entity’s tax classification decides who pays the Georgia lottery tax. A revocable grantor trust or a single member LLC usually leaves the tax with the individual, while a partnership passes shares to its partners.
- Revocable trust: generally a grantor trust, so the grantor reports the prize.
- Single member LLC: generally disregarded, so the owner reports the prize.
- Multi member LLC or partnership: files its own return and allocates shares to partners.
- Timing: the entity should exist and own the ticket before the claim is made.
Claiming through an entity is usually about privacy, management, or group ownership more than tax. For income tax purposes, many common structures do not change who is taxed. A revocable living trust is generally treated as owned by its grantor, so the prize is reported on the grantor’s own returns. A single member LLC is generally disregarded for federal income tax purposes, and Georgia follows the federal classification.
A multi member LLC taxed as a partnership is different. The partnership reports the prize and allocates it to the members under the operating agreement, and each member reports their share. A Georgia partnership return may be required, and nonresident members can raise Georgia withholding or composite return questions. Our guides to the Georgia composite return and the Georgia pass through entity tax election cover those entity level rules.
The order of events matters. An entity that is formed after the claim, and then receives the prize from the winner, raises the same gift and transfer questions as a group claim by one person. Anyone considering an entity claim should have the entity formed, the ticket assigned in writing where appropriate, and the tax classification confirmed before visiting a Lottery office.
What Happens When a Winner Sells Future Lottery Installments?
Georgia allows a winner to assign future installment payments for consideration only under a court order. The buyer must withhold Georgia income tax from the purchase price and remit it with Form G2-LP within 10 days. The Department’s 2018 policy statement and the form still print 5.75 percent, so confirm the current rate first.
- Court order: required under O.C.G.A. 50-27-24.1 for a voluntary assignment for consideration.
- Buyer withholds: Georgia income tax on a purchase price over $5,000.
- Form and deadline: Form G2-LP with payment within 10 days of closing.
- Income timing: follows the federal treatment, lump sum or installment sale.
The Department’s Policy Statement IT-2010-1-27 explains the procedure. It quotes the statute’s requirement that in a voluntary assignment for consideration made under a judicial order, the assignee withholds federal and state income taxes from the purchase price in a manner consistent with the Lottery’s procedures. For Georgia, the assignee withholds a percentage of the purchase price if the total payment exceeds $5,000, sends it to the Department within 10 days of closing, and the seller claims the withholding on their Georgia return.
The rate printed in that policy statement deserves care. It says 6 percent, or 5.75 percent for purchases or installment payments on or after January 1, 2019, and the Form G2-LP (Rev. 08/29/18) prints the same figures. The policy statement was last updated September 19, 2018, before Georgia’s rate cuts. Because the statute ties withholding to the Lottery’s procedures, and the Lottery now withholds 4.99 percent, the buyer and seller should confirm the current rate with the Department’s Withholding Review Unit before closing.
For income timing, the policy statement says Georgia follows the federal treatment. If the sale is treated as an installment sale for federal purposes, Georgia recognizes income in the years payments are received. If all proceeds are recognized in one year federally, Georgia recognizes them in the same year. Both the buyer and the seller keep a copy of Form G2-LP, and the seller attaches it to the Georgia return.
Selling installments usually means accepting a discounted price for future payments. The federal character of the proceeds has been litigated, and the result is generally ordinary income. Anyone considering a sale should have the after tax result of both choices computed before asking a court to approve it.
Can Gambling Losses Reduce Georgia Lottery Tax?
Only for winners who itemize, only up to their gambling winnings, and from 2026 only at 90 percent of the losses under IRC 165(d). Georgia itemized deductions begin with the federal Schedule A amounts, and Georgia’s 2026 conformity bill did not list the 90 percent rule among its exceptions in the summaries reviewed. Records are essential.
- Itemizing required: no loss deduction with the standard deduction on either return.
- Cap: losses deductible only to the extent of gambling gains for the year.
- 90 percent rule: from 2026, only 90 percent of losses count, even within the cap.
- Proof: a diary plus tickets, statements, and account histories.
The current text of IRC 165(d)(1) allows a deduction equal to 90 percent of losses from wagering transactions, and only to the extent of the gains from such transactions during the year. The IRS has explained the record keeping in Topic 419: a casual gambler must keep an accurate diary or similar record of winnings and losses and be able to provide receipts, tickets, statements, or other records.
| Hypothetical, 2026 | Winnings | Losses | Deductible losses | Net gambling income taxed |
|---|---|---|---|---|
| Losses below winnings | $50,000 | $20,000 | $18,000 (90 percent) | $32,000 |
| Break even year | $50,000 | $50,000 | $45,000 (90 percent) | $5,000 |
| Losses above winnings | $50,000 | $80,000 | $50,000 (capped at winnings) | $0 |
| Standard deduction taken | $50,000 | $20,000 | $0 | $50,000 |
For Georgia, the question is conformity. Georgia’s House Bill 1199, signed March 20, 2026, moved Georgia’s conformity date to the Internal Revenue Code as enacted on or before January 1, 2026, for tax years beginning on or after January 1, 2025, with listed exceptions. A KPMG summary of HB 1199 lists decoupling from section 174A, section 179(e), bonus depreciation, and the federal deductions for car loan interest, tips, and overtime. It does not list section 165(d). On that reading, the 90 percent rule flows into Georgia through the federal itemized deduction figures, but the 2026 IT-511 instructions should be checked when they are released.
For a lottery player, losing tickets are wagering losses. Online purchases through the Georgia Lottery’s Players Club leave a transaction history that can support a diary. Cash purchases at retailers leave little, so a player who buys regularly and itemizes should keep losing tickets or a dated log. A loss deduction claimed without records is a frequent adjustment in a federal examination.
Does the Georgia Retirement Income Exclusion Apply to Lottery Winnings?
No. The Department’s list of retirement income that qualifies for the exclusion covers pensions and annuities, interest, dividends, net rental income, capital gains, royalties, and up to $5,000 of earned income. Lottery and gambling winnings are not on the list, so a retiree’s prize is fully taxed by Georgia even if the exclusion has room left.
- Qualifying items: pensions, annuities, interest, dividends, net rents, capital gains, royalties.
- Earned income: up to $5,000 counts toward the exclusion.
- Not listed: lottery and gambling winnings.
- Later years: interest and dividends earned on invested prize money can qualify.
Georgia’s retirement income exclusion is one of the most valuable features of the Georgia return for people aged 62 and older, and many retirees assume it covers any income they receive. The Department’s Retirement Income Exclusion page lists exactly what counts: income from pensions and annuities, interest income, dividend income, net income from rental property, capital gains income, income from royalties, and up to $5,000 of earned income. Gambling and lottery winnings are not included.
The word annuity on that list does not reach a lottery annuity. A lottery prize paid in installments is a prize, not a retirement annuity, and it is reported as gambling income. The exclusion applies to the retirement categories the Department lists, and the prize is not one of them.
The exclusion can still matter in the years after a win. Once the prize is invested, the interest, dividends, and capital gains it produces are retirement income for a qualifying retiree. Our guide to the Georgia retirement income exclusion explains the $35,000 and $65,000 limits by age and how married couples apply them. Our guide to the Georgia capital gains tax covers how gains on investments bought with prize money are taxed.
Are Noncash Prizes and Second Chance Prizes Taxed in Georgia?
Yes. A car, trip, or other merchandise prize is income at its fair market value, and second chance promotion prizes are prizes like any other. For federal withholding on a noncash prize over $5,000, the winner either pays 24 percent of the value to the payer, or the payer covers the tax at a 31.58 percent rate.
- Value: fair market value, reduced by the wager, for reporting and withholding.
- Winner pays: 24 percent of the value, paid to the payer before release.
- Payer pays: 31.58 percent, and the tax paid is added to the reported prize.
- Georgia: the value is income on Form 500 at 4.99 percent.
The IRS instructions for Form W-2G explain the two methods. A payer must take the fair market value of a noncash payment into account. If the value exceeds $5,000 after deducting the wager, the winnings are subject to 24 percent withholding. Under the first method, the winner pays the 24 percent to the payer. Under the second, the payer pays the tax at 31.58 percent, and the reported prize includes both the item and the tax paid on the winner’s behalf.
The fair market value of a prize can be debated. A car with a sticker price is usually valued at what a buyer would actually pay, which may be less than the advertised figure. A winner who believes the value on the W-2G is overstated should keep evidence, such as dealer quotes, to support a different figure on the return.
The Lottery’s FAQ notes that second chance promotion winners are contacted using the information in their Players Club profiles. Those prizes, whether cash, merchandise, or experiences, are taxable in the year received and follow the same reporting rules.
Does Georgia Charge Sales Tax on Lottery Tickets?
No. Georgia exempts lottery ticket sales from sales tax. A December 2023 evaluation by the Georgia Department of Audits and Accounts estimated the exemption at about $229.8 million in fiscal year 2024. The exemption affects the ticket price only; prizes remain fully subject to the Georgia lottery tax on income.
- Tickets: exempt from Georgia sales tax, as in almost all lottery states.
- Purpose: the exemption supports education funding under the Lottery for Education Act.
- Prizes: taxed as income on the federal return and Form 500.
- Losses: the ticket cost counts as a wagering loss only for those who itemize.
The Department of Audits and Accounts summary, Tax Incentive Evaluation: Exemption on the Sale of Lottery Tickets, prepared from a University of Georgia Carl Vinson Institute of Government report, notes that the Lottery for Education Act of 1992 created the Georgia lottery and that lottery tickets are exempt from sales tax in Georgia and almost all other states. It projects the cost of the exemption rising from $229.8 million in fiscal year 2024 to $263.1 million in fiscal year 2028.
This question shows up in searches for Georgia lottery tax because people reasonably wonder whether tax applies at purchase. It does not. The tax that matters to a winner is the income tax on the prize, and that is the subject of the rest of this guide. For the general rules on what Georgia sales tax does reach, see our guide to the Georgia sales tax exemption.
What Should a Georgia Lottery Winner Do in the First 30 Days?
Before claiming a large prize, sign and secure the ticket, decide who owns it, document any pool, and have the federal and Georgia tax computed for the cash and annuity choices. After claiming, set aside the expected federal balance, calendar estimated payments, and keep every form. The 60 day election and 180 day claim windows leave time to plan.
- Secure the ticket: sign it and keep copies; an unsigned ticket is hard to prove as yours if lost.
- Settle ownership: individual, group with Form 5754, or an entity formed in advance.
- Run the numbers: cash versus annuity, federal and Georgia, for the claim year.
- Reserve the gap: move the estimated federal shortfall into a separate account.
The Lottery’s FAQ encourages players to sign their winning tickets, because a lost or stolen unsigned ticket may be impossible to prove as theirs. That is the first step. Everything after it should happen in a deliberate order, because several choices are hard to undo once the claim form is signed.
| When | Step | Why it matters for Georgia lottery tax |
|---|---|---|
| Day 1 | Sign the ticket, photograph both sides, store it securely | Establishes ownership and supports the W-2G |
| Days 1 to 10 | Confirm who owns the ticket: one person, a pool, or an entity | Decides who receives the W-2G and who reports the income |
| Days 1 to 20 | Compute federal and Georgia tax for cash and annuity, and for the claim year | Shows the size of the balance beyond withholding |
| Before claiming | Check for state debts that may be set off under 50-27-53 | Avoids surprise at the claim window and starts the 30 day protest clock knowingly |
| At claim | Bring photo ID and proof of Social Security number; file Form 5754 if a group | Prevents backup withholding and misreported shares |
| Within 60 days of claim | Elect cash or annuity on jackpot games | Fits the qualified prize option rule in IRC 451(j) |
| After payment | Reserve the federal gap, schedule estimated payments, file Form 500-ES if needed | Limits underpayment penalties on both returns |
The Lottery’s How to Claim page says claim centers at headquarters and district offices accept claims by appointment and limited walk ins, and that prizes of $500,000 or more are generally paid within 5 to 10 business days by electronic deposit. Prizes from $601 to $249,999 claimed at an office are generally paid the same day. That timing matters for estimated tax, because the payment date fixes the tax year and the installment period.
Many winners also bring in an estate planning attorney and an investment adviser. Those roles are separate from tax preparation, but the tax computation is the input every other adviser needs. Getting it done before the claim is the single most useful step a winner can take.
What Are the Most Common Georgia Lottery Tax Mistakes?
The common mistakes are treating withholding as the final tax, forgetting prizes of $5,000 or less, skipping estimated payments after a large win, a nonresident not filing Form 500, one pool member claiming without Form 5754, and claiming gambling losses without itemizing or without records. Each one can lead to a balance, penalty, or notice.
- Withholding as tax: the 24 percent federal deposit rarely matches the final federal tax on a large prize.
- Small prizes forgotten: no withholding, but the Lottery reports winners above $600.
- Missed nonresident return: Georgia source income still requires Form 500.
- Unsupported losses: no diary, no deduction, and only 90 percent from 2026.
Most of these mistakes come from reading only the withholding line. The Lottery is clear that it withholds a fixed percentage, and that the final liability may differ. The IRS and the Department both compute the tax on the return, and both receive the Lottery’s information reporting.
| Mistake | Typical consequence | Fix |
|---|---|---|
| Treating the 24 percent as the final federal tax | A large balance and possible underpayment penalty | Compute the tax at claim and make estimated payments |
| Leaving off prizes of $5,000 or less | Federal and Georgia notices proposing tax, penalty, and interest | Report every prize; amend if one was missed |
| A nonresident skipping Form 500 | Georgia withholding never credited, or a Department inquiry | File Form 500 with Schedule 3 |
| One person claiming for a pool without Form 5754 | The whole prize on one return, and gift questions on transfers | Use individual payments or Form 5754 at claim |
| Losses claimed without itemizing or records | Deduction disallowed on examination | Itemize only when it helps, and keep a diary and tickets |
| Using a calculator with a stale Georgia rate | Wrong reserve for Georgia tax | Use the 4.99 percent 2026 rate from the Department |
None of these is unusual, and most are fixable with an amended return or a payment arrangement. The cost is mostly in interest and penalties that accumulate while the mistake goes unnoticed, which is why an early review after a large win is worthwhile.
What If the Georgia Lottery Tax Bill Cannot Be Paid in Full?
If the prize money has been spent or committed and the Georgia balance cannot be paid, file the return on time anyway and pay what is possible. The Department of Revenue offers payment plans for individual income tax, and other relief may exist in hardship cases. Federal balances have their own installment options with the IRS.
- File on time: the failure to file penalty is usually larger than the failure to pay penalty.
- Georgia payment plan: available through the Department for qualifying balances.
- Hardship: a Georgia offer in compromise is considered only in limited circumstances.
- Federal side: installment agreements are handled separately from the Georgia balance.
It is more common than people think for a winner to owe tax on a prize that is no longer in the bank. Gifts to family, a home purchase, debt payoff, or an investment that lost value can leave nothing set aside for the April balance. Because Georgia withholds 4.99 percent, the Georgia shortfall is usually smaller than the federal one, but it can still be significant when several prizes were under $5,000 or when the return includes other income.
Our guide to the Georgia Department of Revenue payment plan explains the Georgia Tax Center request, the terms, and what happens if a payment is missed. Where paying in full would cause genuine hardship, our guide to the Georgia offer in compromise explains when the Department considers an offer and why many requests do not qualify. Every outcome depends on the facts, and the Department decides each request.
The choice to avoid is not filing. A missing return stops the Georgia withholding from being credited, prevents any refund, and allows the Department to estimate the tax from the Lottery’s information return. A filed return with a balance due is much easier to resolve than an unfiled one.
How Do You Fix a Lottery Prize Left Off a Georgia Return?
File an amended Georgia return, Form 500X, reporting the prize and claiming the Georgia withholding from the W-2G, and amend the federal return first or at the same time. Paying the additional tax with the amendment stops further interest. Acting before the Department sends a notice is usually the simplest path.
- Federal first: the Georgia return builds from federal adjusted gross income.
- Georgia Form 500X: reports the prize and credits the Georgia withholding.
- Payment: include the additional tax to stop interest from growing.
- Notice received: respond within the deadline on the notice instead of only amending.
The Lottery reports winners of prizes above $600 to both the IRS and the Department, so an omitted prize may eventually produce a notice. Amending first keeps the correction in the taxpayer’s hands. Our guide to the Georgia amended tax return explains Form 500X, the deadlines, and how to report a federal change to Georgia.
An omitted prize over $5,000 can produce a Georgia refund on amendment, not a balance. The Lottery withheld 4.99 percent and sent it to the Department, but that money is credited only when the return reports it. A winner who left both the prize and the withholding off the original return may find the amendment roughly balances on the Georgia side, while the federal amendment still shows tax due.
If a Department notice has already arrived, read its deadline first. A proposed assessment has its own protest window, and filing an amended return alone may not stop the assessment process. The notice should be answered on time with the amendment attached or referenced.
Georgia Lottery Tax Help in Naples & Southwest Florida
Tax Expert Today LLC works from Naples, Florida and handles state tax matters nationwide, including Georgia lottery tax planning before a claim, Form 500 resident and nonresident returns, estimated payment schedules, group claim documentation, and responses to Georgia Department of Revenue notices. Georgia clients are served from the Naples office and do not need to travel.
- Georgia lottery tax help Naples serves Southwest Florida residents who won a Georgia prize and Georgia winners who split time in Florida.
- Before the claim: cash versus annuity computations and ownership planning.
- After the claim: federal and Georgia returns, estimated payments, and amendments.
- Remote engagement is standard. Documents are exchanged through a secure client portal and not by email.
Tax Expert Today LLC
11983 Tamiami Trail N, Naples, FL 34110
Telephone: (239) 441-2005
Hours: Monday through Friday, 10:00 a.m. to 5:00 p.m. Eastern Time
A local question we are asked often: I live in Naples and won $40,000 on a Georgia scratcher while visiting family in Savannah. Do I have to file in Georgia even though Florida has no income tax? Generally yes. Georgia treats Georgia lottery winnings as Georgia source income, so a Florida resident with that prize who must file a federal return must also file Georgia Form 500 as a nonresident. The Lottery would have withheld 4.99 percent for Georgia and 24 percent for federal tax, and the Georgia return is where that withholding is credited and any refund or balance is settled. Our Georgia tax services page describes how Georgia matters are handled from Naples, and our Naples tax planning page covers the Florida side.
When to Engage a Professional
A single prize under $5,000 with no other complications can usually be reported without help. Professional review is worth it before claiming a large prize, when choosing cash or annuity, for any group or entity claim, for nonresident or multistate filings, when installments may be sold, or when a state debt set off or Department notice is involved.
- A large prize where the federal gap and estimated payments need to be computed.
- The cash or annuity election within the 60 day window.
- Group, trust, or LLC claims where ownership and Form 5754 decide who is taxed.
- Nonresident or multistate winners with Georgia and home state returns to coordinate.
- A set off or notice with a 30 day or protest deadline running.
Tax Expert Today LLC brings together tax advisors, enrolled agents, CPAs, and attorneys and serves clients in all 50 states on federal and state tax matters, including Georgia income tax. A lottery engagement usually begins with the ticket facts and the winner’s prior year returns, followed by a computation of federal and Georgia tax for each payment choice, an estimated payment schedule, and a review of ownership and filing obligations in every state involved. Outcomes depend on the facts and the law in effect, and the IRS and the Department of Revenue decide every assessment and refund. Related Georgia topics include Georgia Form 500-ES estimated tax and the Georgia part year resident return, and our Georgia tax services page lists the full range. Call (239) 441-2005 for a free consultation.
Frequently Asked Questions About Georgia Lottery Tax
How much is the Georgia lottery tax?
Georgia taxes lottery prizes as ordinary income at the 2026 flat rate of 4.99 percent. On prizes over $5,000, the Georgia Lottery withholds 4.99 percent for Georgia and 24 percent for federal tax. The final tax is computed on the Georgia and federal returns and can be higher or lower than the amount withheld.
Are Georgia lottery prizes of $5,000 or less taxed?
Yes. Georgia’s withholding rule says all lottery proceeds are taxable regardless of the amount. Prizes of $5,000 or less are paid without income tax withholding, so the winner must report them and pay the federal and Georgia tax with the return. The Lottery reports winners of prizes above $600 to the IRS and the Department of Revenue.
Why do I owe federal tax after the Lottery withheld 24 percent?
The 24 percent federal withholding is a deposit. The prize is taxed at the winner’s own federal brackets, which reach 32, 35, and 37 percent. When part of the prize falls in those brackets, the withholding does not cover the full tax, and the difference is due with the return.
Does a nonresident have to pay Georgia lottery tax?
Yes. The Georgia Department of Revenue lists Georgia lottery winnings as Georgia source income. A nonresident who receives a Georgia Lottery prize and must file a federal return must also file Georgia Form 500, using Schedule 3, and claims the 4.99 percent Georgia withholding on that return.
Do I pay Georgia tax on lottery winnings if I live in Florida?
Yes, if the prize is from the Georgia Lottery. The prize is Georgia source income, so Georgia taxes it and a Georgia nonresident return is generally required. Florida has no personal income tax, so the only income taxes on the prize are Georgia tax and federal tax.
Can the Georgia Lottery take my prize for back taxes or child support?
Yes. Under O.C.G.A. 50-27-53, state agencies can list debts over $100, and the Lottery withholds them from the prize. State taxes rank first and delinquent child support second. The winner can protest in writing within 30 days of the notice, which sends the dispute to superior court.
Can gambling losses offset Georgia lottery winnings?
Only if you itemize deductions, only up to your gambling winnings, and from 2026 only 90 percent of losses under IRC 165(d). Georgia itemized deductions start from the federal Schedule A figures. You need records such as a diary, losing tickets, and account statements to support the deduction.
Is the cash option or the annuity taxed differently in Georgia?
Georgia taxes both at its flat rate in the year each payment is received, 4.99 percent in 2026. The bigger difference is federal: the cash option puts the whole prize in one year and mostly in the 37 percent bracket, while the annuity spreads income over 30 payments.
Does the Georgia retirement income exclusion cover lottery winnings?
No. The Department’s list of qualifying retirement income covers pensions and annuities, interest, dividends, net rental income, capital gains, royalties, and up to $5,000 of earned income. Lottery and gambling winnings are not on the list, so they are fully taxed even for retirees aged 62 and older.
I live in Naples, Florida and won a Georgia Lottery prize. Can you help with the Georgia return?
Yes. Tax Expert Today LLC handles state tax matters nationwide from its Naples, Florida office at 11983 Tamiami Trail N, including Georgia nonresident Form 500 returns for lottery prizes, cash or annuity computations, estimated payments, and Georgia Department of Revenue notices. Call (239) 441-2005 for a free consultation.
Published October 6, 2026 by Dr. Pellumb Kabashi « Back to Learning Center
Have a question this article touches on?
Tax Expert Today LLC, based in Naples, Florida and serving clients across the United States.
Schedule a Consultation (239) 441-2005