
By Dr. Pellumb Kabashi, DBA, MBA, EA, CFE, CES
Founder, Tax Expert Today LLC · Tax advisors, enrolled agents, CPAs, and attorneys · Serving clients in all 50 states
The Georgia rural hospital tax credit is a 100 percent Georgia income tax credit for a preapproved gift to an approved rural hospital, under O.C.G.A. 48-7-29.20. Limits are $5,000 single, $10,000 joint, and $25,000 for a pass-through owner through June 30, then up to Georgia tax after July 1. The 2026 cap is $100 million and about 54 percent was used on September 17. Call (239) 441-2005 for a free consultation.
What Is the Georgia Rural Hospital Tax Credit?
The Georgia rural hospital tax credit is a state income tax credit for cash given to a rural hospital organization approved by the Georgia Department of Community Health. O.C.G.A. 48-7-29.20 provides the credit, the Department of Revenue administers it as Tax Credit Code 136, and the credit is allowed only after the Department preapproves the gift.
- What it rewards: a cash gift to an approved rural hospital organization for the direct benefit of that organization.
- How it pays: a credit against Georgia income tax equal to 100 percent of the gift, up to the limits in the statute.
- Who can use it: individuals, pass-through owners, corporations, trusts, and pass-through entities that elect to pay tax at the entity level.
- What controls it: preapproval, a $4 million limit per hospital, and a $100 million statewide cap.
The statute defines a qualified rural hospital organization expense as the contribution of funds by an individual or corporate taxpayer to a rural hospital organization for the direct benefit of that organization during the tax year for which the credit is claimed, and it defines a rural hospital organization as one approved by the Department of Community Health under O.C.G.A. 31-8-9.1. The credit therefore follows the gift to the hospital. Paying a hospital bill, buying a service, or giving to a hospital foundation that is not on the approved list earns nothing under this section.
The program took effect on January 1, 2017. The Georgia Department of Audits and Accounts, which audits it every year, describes the reasons for it plainly: rural hospitals face depopulation, a high share of uninsured and Medicaid patients, and staffing pressure, and eight of them have closed since 2010. Earlier versions of the program credited only 70 percent and then 90 percent of a gift. The credit is now 100 percent, and the annual statewide cap has moved from $60 million to $75 million and, beginning in 2025, to $100 million. The 2024 legislation, HB 1339 also extended the program for five more years, so O.C.G.A. 48-7-29.20 is now repealed and reserved effective December 31, 2029.
Readers who know Georgia’s scholarship credit should not carry its rules over. The Georgia qualified education expense credit is prorated and has been fully preapproved on the first days of January, while the rural hospital credit is allocated first come, first served without proration and has not filled in recent years. The two share a federal tax problem, which is covered later in this article, but almost nothing else. For a Georgia household or business the rural hospital credit is one lever in a larger state plan of the kind described on our Georgia tax services page. The sections below follow the order a donor meets the rules: the limits, the cap, the hospital, the preapproval, the payment deadline, the return, and then the federal side, where most of the planning mistakes happen.
How Does the Georgia Rural Hospital Tax Credit Work?
A taxpayer asks the Department of Revenue for preapproval to give a stated amount to a listed hospital, pays it by the deadline, and claims the credit on the Georgia return for the year of the gift. Because the credit equals the gift, the money mostly moves from the Georgia tax bill to the hospital.
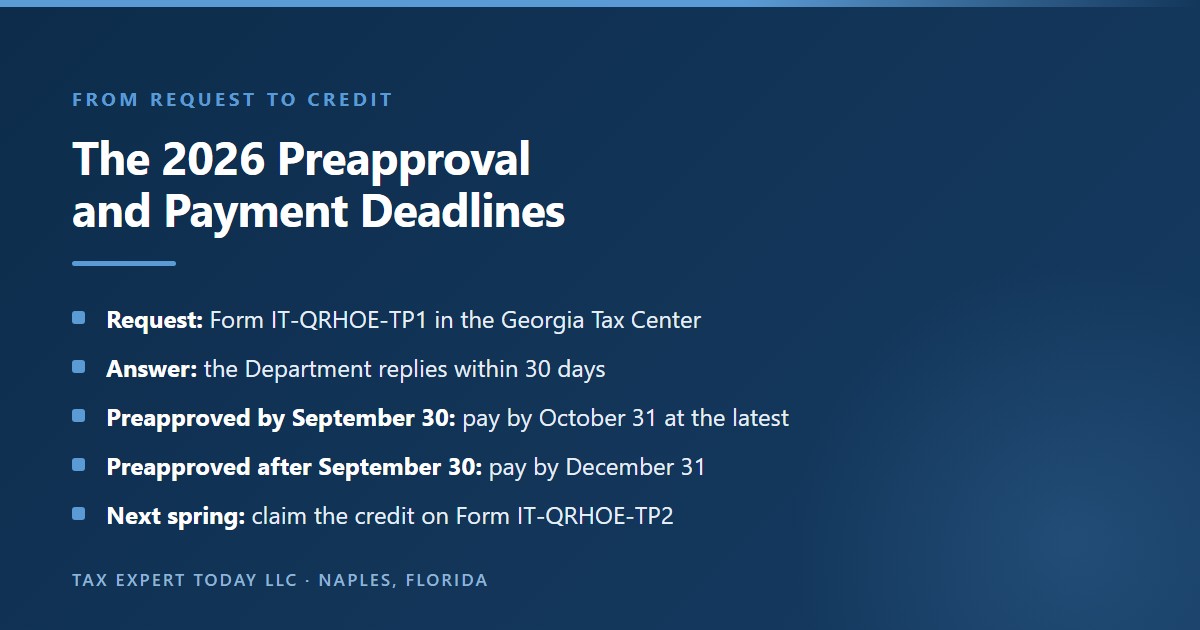
- Step one: choose a hospital on the Department of Community Health list, then request preapproval on Form IT-QRHOE-TP1 in the Georgia Tax Center.
- Step two: the Department approves or denies the request within 30 days and issues a tax credit certificate number.
- Step three: pay the approved amount to the hospital by the payment deadline that applies to the preapproval date.
- Step four: the hospital issues Form IT-QRHOE-RHO1 within 30 days of the gift and reports it to the Department.
- Step five: claim the credit on Form IT-QRHOE-TP2 with the Georgia return.
The simplest way to think about the credit is as a redirect. A household that expects to owe $6,000 of Georgia income tax and is preapproved for a $2,500 gift, with a $2,500 credit, still parts with $6,000 in total. It pays $2,500 to the hospital and $3,500 to the state. Nothing in that arithmetic creates a profit, and the credit is not a refund of money the household would not otherwise have paid. What the taxpayer gains is a choice about where a portion of an existing Georgia tax bill goes, and the taxpayer pays the hospital months earlier than the state.
The redirect framing also explains who can use the credit fully. The statute provides that the total credit for a year cannot exceed the taxpayer’s Georgia income tax liability, and that any unused credit may be applied against the succeeding five years of tax. A taxpayer with little Georgia liability, such as a retiree whose income is mostly excluded under the Georgia retirement income exclusion, can end up with a credit that sits unused for years. Timing is the other half of the mechanism: the gift is made during the year, often well before the return is filed the following spring, so the donor funds the hospital first and recovers the amount through a lower payment to the state later.
How Much Can You Claim? Georgia Credit Limits by Taxpayer
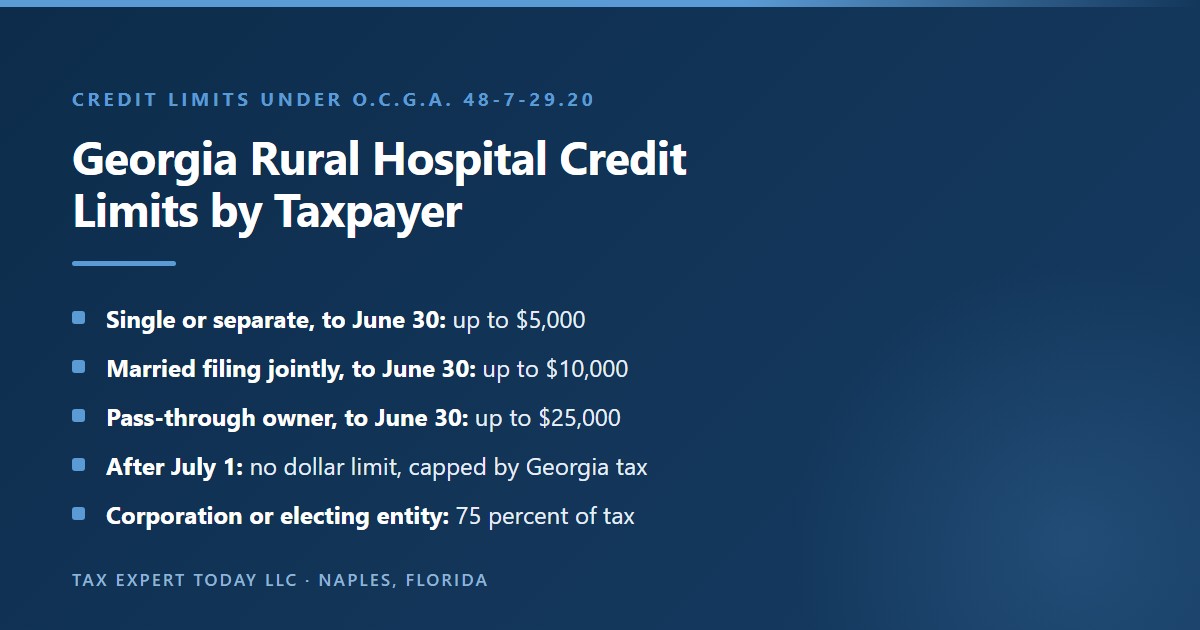
The credit equals the amount given, within limits by taxpayer and date. Through June 30 an individual may be approved for $5,000, a joint return $10,000, and a pass-through owner $25,000. After July 1 individuals have no dollar limit. A corporation, trust, or electing entity is limited to 75 percent of its Georgia liability.
- Single or head of household: up to $5,000 from January 1 through June 30.
- Married filing separately: up to $5,000 in the same window, per the regulation.
- Married filing jointly: up to $10,000 in the same window.
- Owner of an LLC, S corporation, or partnership: up to $25,000 in the first half, limited to tax actually paid on the selected Georgia income.
- Corporation, fiduciary, or electing entity: up to 75 percent of Georgia income tax liability in either window.
| Taxpayer | January 1 to June 30 | July 1 to December 31 | Authority |
|---|---|---|---|
| Single or head of household | $5,000 | Amount given, capped by Georgia tax liability | Reg. 560-7-8-.57(4)(a) and (4)(g)1 |
| Married filing separately | $5,000 | Amount given, capped by Georgia tax liability | Reg. 560-7-8-.57(4)(b) and (4)(g)2 |
| Married filing jointly | $10,000 | Amount given, capped by Georgia tax liability | Reg. 560-7-8-.57(4)(c) and (4)(g)3 |
| Member, shareholder, or partner not electing at the entity level | $25,000, limited to tax actually paid on the selected Georgia income | No dollar limit, still limited to tax actually paid on Georgia pass-through income | Reg. 560-7-8-.57(4)(d) and (4)(g)4; HB 1339 |
| C corporation, fiduciary, electing S corporation, or electing partnership | 75 percent of Georgia income tax liability | 75 percent of Georgia income tax liability | O.C.G.A. 48-7-29.20; Reg. 560-7-8-.57(4)(e) and (4)(g)5 |
The pass-through owner figure was raised by HB 1339 effective January 1, 2025. In tax years 2019 through 2024 an owner of an LLC, S corporation, or partnership had the same $10,000 first half limit as a married couple filing jointly, which the Auditor’s 2025 report notes in its exhibit footnotes. Older pages that still quote $10,000 for owners are describing a rule that no longer applies. The Georgia HEART summary of the 2024 amendments lists the $25,000 owner limit alongside the extended payment deadlines discussed below.
Every limit is a ceiling on the credit, never a floor. The amount a taxpayer actually receives is the smallest of the statutory limit for that window, the amount the Department preapproves, the amount actually paid to the hospital by the deadline, and the taxpayer’s Georgia income tax liability for the year, with any excess of the paid amount over liability carried forward for up to five years. The regulation adds that a preapproved amount above what the taxpayer’s limit later allows cannot be claimed and cannot be carried forward, which is why the sizing of the request matters more than its timing for owners and entities.
Why Do the Georgia Limits Change on July 1?
The statute separates the year into two preapproval windows. From January 1 through June 30 the Department caps what each type of individual donor may be approved for, and it caps how much of each hospital’s room can go to individuals and to corporate donors. From July 1 through December 31 it approves requests until the annual cap is reached.
- Opening date: the Department’s 2026 report shows January 2, 2026 as the first day requests could be filed for the first half.
- First half hospital buckets: each hospital may be preapproved for no more than $2 million from individuals and $2 million from corporate donors through June 30.
- If a bucket is full: later requests for that hospital and donor type are denied, with no proration by application date.
- Second half: the buckets end, and only the $4 million hospital limit and the statewide cap remain.
The regulation spells out the two per hospital buckets in paragraph (7). From January 1 through June 30 the Department preapproves credits for each rural hospital organization from individual taxpayers in an aggregate amount not to exceed $2 million, and from corporate, fiduciary, electing S corporation, and electing partnership taxpayers in an aggregate amount not to exceed $2 million. A taxpayer denied in the first half because a bucket is full may reapply on or after July 1 for the same hospital, without priority over other applicants, or may apply for a different hospital. For priority when the statewide cap is close, the date of the new application governs.
The July 1 change shows up in the Department’s own monthly totals. Preapprovals for 2026 stood at $28,228,467 on the June 24 report and at $42,668,498 on the July 22 report, an increase of about $14.4 million in a single month after the individual dollar limits ended. In the first half of the year the total rose by roughly $3 million to $6 million a month. Donors who intend to give more than the first half limit, and who are content with the after July 1 timing, are the source of most of that jump. The practical result is that a donor with a large Georgia liability has a real choice between giving the first half limit early and giving a larger amount later, and the choice interacts with the payment deadline covered below.
What Is the Georgia Rural Hospital Credit Cap, and How Full Is It in 2026?
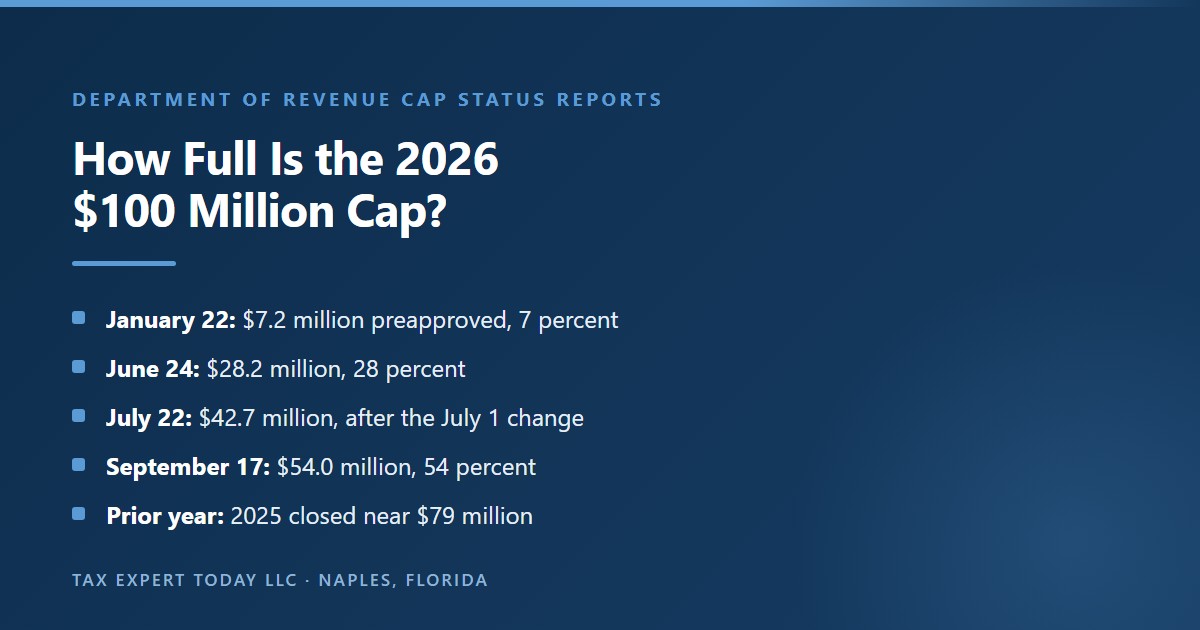
The statewide cap is $100 million per calendar year beginning in 2025, up from $75 million in 2023 and 2024 and $60 million before that. The Department of Revenue reported on September 17, 2026 that $53,974,527 had been preapproved, which is 54.0 percent, leaving $46,025,473 of the 2026 cap.
- 2026 cap: $100,000,000 for tax years beginning on or after January 1, 2025.
- Used by September 17: $53,974,527 of preapprovals processed.
- Remaining: $46,025,473, before any preapproved gift that is never paid is returned to the pool.
- Paid so far: hospitals had reported $29,706,285 of contributions actually received, which is 55 percent of the preapproved total.
The Department publishes a cap status report about once a month on its monthly rural hospital credit report page. Read together, the 2026 reports show the pace of the year, and the 2025 reports show how the prior year ended. The figures below are the amounts preapproved through each report date, taken from the Department’s own text on each report.
| 2026 report date | Preapproved to date | Share of the $100 million cap | Remaining |
|---|---|---|---|
| January 22, 2026 | $7,229,130 | 7.2% | $92,770,870 |
| February 20, 2026 | $13,586,985 | 13.6% | $86,413,015 |
| March 19, 2026 | $17,439,748 | 17.4% | $82,560,252 |
| April 22, 2026 | $22,377,593 | 22.4% | $77,622,407 |
| May 26, 2026 | $25,461,532 | 25.5% | $74,538,468 |
| June 24, 2026 | $28,228,467 | 28.2% | $71,771,533 |
| July 22, 2026 | $42,668,498 | 42.7% | $57,331,502 |
| August 26, 2026 | $48,621,220 | 48.6% | $51,378,780 |
| September 17, 2026 | $53,974,527 | 54.0% | $46,025,473 |
The same reports for 2025 show a similar shape and a finish well short of the cap. The September 17, 2026 report is the most recent one available on the day this article was written, and the Georgia HEART home page, which counts applications it has submitted or is about to submit, showed $57,498,298 applied for and $42,501,705 remaining the same week. The two figures measure slightly different things, and the Department’s figure is the one that controls.
| 2025 report date | Preapproved to date | Share of the $100 million cap |
|---|---|---|
| June 23, 2025 | $30,428,888 | 30.4% |
| September 24, 2025 | $55,101,991 | 55.1% |
| December 15, 2025 | $71,468,227 | 71.5% |
| January 22, 2026 (2025 year, after the year closed) | $79,980,473 | 80.0% |
| March 19, 2026 (2025 year, after uncontributed amounts were removed) | $79,167,210 | 79.2% |
Two things stand out. First, 2026 is tracking almost exactly where 2025 was at the same point: $54.0 million by September 17 in 2026 against $55.1 million by September 24 in 2025. Second, the 2025 total climbed by about $16 million between September and mid December, which is the year end rush, and it still closed near $79 million. The Auditor’s report shows that contributions were $72.4 million in 2023 and $74.3 million in 2024, against a $75 million cap in both years, so under the old cap the program came within a percent or two of full. Under the $100 million cap it has not. None of this forecasts 2026, and the report itself warns that amounts change if a preapproved donation is never confirmed as made.
Does the Georgia Rural Hospital Credit Sell Out Like the Education Credit?
No, not in recent years. The scholarship credit under O.C.G.A. 48-7-29.16 was fully preapproved by January 3, 2026, with requests prorated. The rural hospital credit is allocated first come, first served with no proration by application date, and its cap was still 46 percent unused on September 17, 2026. The binding constraint is more often a single hospital’s limit.
- Different allocation: the education credit is decided in one opening day queue, and this credit is decided request by request.
- No proration by date: the regulation states that there is no proration based on the date an application is received.
- A larger cap: $100 million for the hospital credit against a scholarship cap that is far more oversubscribed.
- Timing risk: the risk is a full hospital bucket or a missed payment deadline, not a sold out cap.
The contrast matters because readers who have read about the Georgia qualified education expense credit often assume the same January race applies here. It does not. A donor who applies in September can still be preapproved, as the September 17 report shows, and a donor whose first choice hospital is full is routed to another hospital rather than turned away. The regulation says that if a request would push a hospital over its limit, the Department preapproves the proportional amount up to the limit and attributes the remainder to the listed hospital with the highest financial need that has not yet reached its own limit.
There is one exception to the no sell out point. If the statewide cap were ever reached during a calendar year, the regulation provides that later requests are denied and are not reconsidered even if uncontributed amounts later reopen room. That has not happened at the $100 million level, but the wording is the reason a donor with a large Georgia liability should not assume the credit will always be there in December. The safer reading is that the credit is generally available, and that the earlier the request is filed, the fewer variables remain.
Which Hospitals Qualify, and What Is the $4 Million Hospital Limit?
Only hospitals on the Department of Community Health’s annual list of approved rural hospital organizations qualify. No hospital may receive more than $4 million of preapproved credits in a calendar year. The Department of Revenue denies a request that names a hospital that is not listed when it checks, and the donor must then file a new request.
- The list: the Department of Community Health posts it each year, ranked by financial need and in alphabetical order.
- The limit: $4 million of credit per hospital per calendar year, with no proration by application date.
- Undesignated gifts: they go to the highest ranked hospital that has not reached its limit.
- File after listing: the regulation says not to file the request until the hospital appears on the list.
The Georgia HEART program’s summary of the law states the qualification criteria: a county population of 50,000 or less, excluding military personnel; tax exempt status or management by a public hospital authority; acceptance of Medicare and Medicaid; and a minimum annual provision of indigent or uncompensated care. A qualifying hospital must also file a five year viability and stability plan with the Department of Community Health each year. The Department’s rural hospital tax credit page lists the yearly documents and, as of September 23, 2026, states that the 2026 documents were still pending completion. A donor should confirm the current list before filing.
The 2026 monthly report shows how uneven the giving is. The five hospitals with the largest preapproved amounts on September 17, 2026 were:
| Hospital (2026 report) | Preapproved credits | Share of the $4 million hospital limit | Contributions reported received |
|---|---|---|---|
| Colquitt Regional Medical Center | $3,449,019 | 86% | $1,127,687 |
| TMC Higgins General Hospital | $2,814,453 | 70% | $1,503,353 |
| Coffee Regional Medical Center | $2,425,516 | 61% | $1,207,170 |
| Southeast Georgia Health System, Inc. | $2,303,522 | 58% | $766,022 |
| John D. Archbold Memorial Hospital | $2,193,046 | 55% | $1,469,046 |
The Auditor’s report explains the pattern. Most contributions are designated by donors and not necessarily directed to the neediest hospitals: in 2024, 98 percent of contributions were designated. Colquitt Regional received nearly $4 million in both 2023 and 2024, and a hospital that is close to its limit is where a late request can be split. Undesignated amounts in 2026 were small, $447,891 of the $53.97 million preapproved. In 2024 the undesignated gifts went to Northeast Georgia Medical Center Lumpkin, which ranked first in financial need.
Eligibility itself changed this year. Senate Bill 111 as passed, Act 462 of 2026, was signed on May 11, 2026, shows a July 1, 2026 effective date in the legislature’s status history, and amends O.C.G.A. 31-8-9.1 to revise the definition of a rural hospital organization. The bill’s first reader title concerns an unrelated subject, which is why a search by title does not find it. In committee testimony reported in the press, a presenter described the change as adding rural freestanding emergency departments and facilities licensed for labor and delivery, and roughly seven more hospitals, to the program. Treat that description as background rather than as the statutory text, and rely on the Department of Community Health list for which organizations are eligible for the year of the gift.
How Does Preapproval Work on Form IT-QRHOE-TP1?
A donor must request preapproval electronically on Form IT-QRHOE-TP1 through the Georgia Tax Center, or have Georgia HEART file the request. Requests are ranked by the date and time of electronic submission, the Department replies within 30 days, and a gift made without preapproval earns no credit.
- Only electronic: the Department will not preapprove a request submitted in any other manner.
- Ranked by time stamp: first come, first served, with no proration based on the date received.
- A 30 day answer: the notice states the amount, the credit certificate number, and the hospital or hospitals attributed.
- One request per gift: each donation to each hospital, and each donation before and after July 1, is applied for separately.
The Department’s donor submission instructions walk through the Georgia Tax Center screens. The donor opens the applicable tax account, selects Manage my credits, then Request Credit Pre-Approval, and chooses credit type 136, the Qualified Rural Hospital Organization Credit. An individual states a filing status and the tax year end of the return that will claim the credit, and a joint filer supplies the spouse’s information. A taxpayer who has never filed a Georgia income tax return must first call the Taxpayer Services Call Center at 1-877-423-6711 to be registered. A corporate, fiduciary, or individual tax account is required.
There are two routes. In the first, the donor files the request directly. In the second, the donor completes an online application with Georgia HEART, a company that contracts with the hospitals rather than the state, and HEART submits the request to the Department in the order it is received, tells the donor the approval and the payment deadline, and later provides the receipt. The Auditor found that hospitals pay HEART a fee of 3 percent of contributions, which is the limit in state law, so the fee is borne by the hospital and does not reduce the donor’s credit. The donor still pays the hospital, and the credit is still claimed by the donor on the Georgia return.
A preapproval is not a payment. The regulation states that if a taxpayer is preapproved for an amount that exceeds what the return later allows, the excess cannot be claimed and cannot be carried forward. That is why the request should be sized to a documented estimate of Georgia tax rather than to the largest figure a form will accept, a point developed in the owner and entity sections below.
What Are the 2026 Payment Deadlines After Preapproval?
For a request preapproved on or before September 30, the gift must be paid within 180 days of the Department’s notice and no later than October 31. For a request preapproved after September 30, the gift must be paid on or before December 31. The regulation and the Department page state both rules.
- Preapproved by September 30: the earlier of 180 days from the notice or October 31.
- Preapproved after September 30: December 31 of the same year.
- October 31, 2026: falls on a Saturday, so a check or transfer should be sent well before the weekend.
- Georgia HEART: its home page describes an October 1 application that it says carries a December 31, 2026 payment deadline.
These rules took effect on January 1, 2025 under HB 1339. Before that, the statute allowed 180 days from the notice regardless of date, which left some preapprovals due in the last days of December with no time to reallocate unpaid amounts. The Georgia HEART summary says the revised deadlines should help ensure that all available credits are used. The table below applies the rule to sample preapproval dates in 2026.
| Preapproval notice date (2026) | 180 days later | Payment deadline |
|---|---|---|
| January 15 | July 14 | July 14 |
| March 2 | August 29 (Saturday) | August 29 |
| April 20 | October 17 (Saturday) | October 17 |
| May 4 | October 31 (Saturday) | October 31 |
| June 1 | November 28 | October 31, the fixed date |
| September 29 | March 28, 2027 | October 31, the fixed date |
| October 2 | Not applicable | December 31 |
The table shows why the last week of September is a decision point. As of September 23, 2026, a request filed today may be answered before or after September 30, since the Department has up to 30 days, and the answer date decides whether the deadline is October 31 or December 31. A donor who needs the longer runway should not assume it, and a donor who needs certainty should ask the Department or HEART which side of September 30 the notice will fall on. The regulation states the same two rules in paragraph (8)(d), and the Department’s report of timelines for 2026 restates them.
What Happens If You Are Preapproved but Do Not Pay?
The credit is lost for the unpaid amount. It cannot be claimed and cannot be carried forward. The Department then adds the uncontributed amount back to the pool available to other donors. A taxpayer who reapplies receives no priority, and the date of the new application governs if the cap is close.
- Nothing to claim: a credit exists only for the amount actually contributed.
- No carryforward: the regulation bars carrying forward a preapproved amount that was never given.
- The pool is refilled: the Department adds uncontributed amounts back to the room available for preapproval.
- No priority on reapplying: a repeat request is treated as new.
The regulation gives a worked example. A married couple filing jointly is preapproved for $7,100, gives $3,000 within 180 days and before October 31, and files a Georgia return. They can claim only $3,000, and the $4,100 that was preapproved but not given cannot be claimed or carried forward. The numbers in the Department’s September 17, 2026 report show why this matters in practice: hospitals had reported $29.7 million of contributions received against $54.0 million preapproved, so roughly $24.3 million of approved credit had not yet been matched by a confirmed gift.
The Auditor’s report also describes a workaround that donors used and the Department later closed. Before July 2024, the Department’s system could not record a zero dollar contribution, so Georgia HEART reported a $1 contribution for a taxpayer who decided not to give, to release the taxpayer’s preapproved credit to other donors more quickly. The Department modified its system in July 2024 to allow $0 contribution reporting. A donor who will not give an approved amount should tell the hospital or HEART promptly, because it returns room to the pool for other donors and avoids a credit certificate that does not match a gift.
How Do Pass-Through Owners Use the $25,000 Georgia Limit?
An LLC member, S corporation shareholder, or partner may be approved for up to $25,000 through June 30, but the credit is allowed only on Georgia income on which tax was actually paid. With several entities, the total credit cannot exceed $25,000, and the individual decides which entities to include.
- The ceiling: $25,000 in the first half, raised from $10,000 effective January 1, 2025.
- The real limit: Georgia tax actually paid on the income of the entities the owner selects.
- More than one entity: combine their Georgia income, loss, and expense, then multiply by the marginal rate.
- Joint returns: a spouse with ownership interests is separately eligible for a credit of the same kind.
The regulation’s example is built around the 2025 rate of 5.19 percent. An individual owns all of an S corporation, half of a partnership, and 20 percent of an LLC taxed as a partnership. The owner requests preapproval on May 31, expects $300,000 of Georgia income from the S corporation and $200,000 from the partnership, leaves the LLC out, and is preapproved for the $25,000 limit, since $25,000 is less than the $25,950 of tax that 5.19 percent of $500,000 supports. The owner gives $25,000. When the return is filed, the actual income from the selected entities is far lower, and the owner can claim only $7,785, which is 5.19 percent of $150,000. The remaining $17,215 is lost. Nothing carries forward.
The owner may include an entity that was not part of the estimate at the time of preapproval, which the regulation confirms with the LLC in its example. The regulation’s example reaches its $150,000 base by adding the owner’s $50,000 salary from the S corporation, the $15,000 fixed partner payment from the partnership, the S corporation’s income, and the partner’s share of the partnership and LLC income. The lesson is that the base is the owner’s Georgia income from the selected entities, not only the passed through share, and a request should be built from a worksheet that includes each component.
How Is Tax Actually Paid Computed for the Pass-Through Limit?
The regulation multiplies the combined Georgia income, loss, and expense from the owner’s selected entities by the applicable marginal Georgia rate, and that product is the tax treated as actually paid. Income that the owner subtracted because an entity paid Georgia tax at the entity level is excluded from the base.
- The rate: Georgia’s flat rate for 2026 is 4.99 percent per the Department’s Important Tax Updates page.
- The base: Georgia income, loss, and expense from the entities the owner selects, combined.
- The exclusion: income subtracted because the entity paid tax under Regulation 560-7-3-.03.
- The timing choice: the owner can decide at filing which entities to include.
Restating the regulation’s example at the 2026 rate shows how far a request can overshoot. Suppose an owner is preapproved for the $25,000 limit and later finds that the Georgia income from the selected entities is $150,000. At 4.99 percent, the tax treated as paid is $7,485, so the credit is $7,485 and $17,515 of the preapproved amount is lost. If the same owner had selected $500,000 of Georgia income, the base would support $24,950 of credit, just under the $25,000 limit. A request that starts from the expected base, rather than from the limit, avoids giving away a credit that cannot be used.
The regulation states that from July 1 through December 31 the Georgia Tax Center option to indicate pass-through ownership is not available, since the credit is not limited for individuals during that period. It adds that members may still choose to apply the pass-through provisions when claiming the credit, and that those provisions apply where the entity itself has no liability. The practical reading is that the $25,000 figure is a first half preapproval limit, and that the tax actually paid test continues to control what the owner can claim in either half. An owner whose income is largely excluded, for example because the entity elected to pay Georgia tax itself, should assume the base will be small.
Owners who are still deciding whether the entity should pay tax at the entity level will find the trade off in our article on the Georgia pass through entity tax election. The election and this credit interact directly, as the next section explains, and the interaction is one of the more consequential planning points for a Georgia S corporation or partnership.
How Does the Rural Hospital Credit Work With the Georgia Pass-Through Entity Election?
An S corporation or partnership that elects to pay Georgia tax at the entity level may claim the credit itself, up to 75 percent of its Georgia income tax liability, but it cannot pass the credit through to owners. Owners must exclude the entity taxed income when they compute their own $25,000 owner limit.
- Entity route: the electing entity gives and claims the credit against its own liability.
- No pass through: the regulation states that electing entities cannot pass the credit to members, partners, or shareholders.
- Owner route: an owner of a non-electing entity gives personally and uses the $25,000 owner limit.
- An either or choice: the same Georgia income cannot support both routes.
The Auditor’s report shows how large this route has become. Of the 767 corporate taxpayers that gave in 2024, 521, or 68 percent, were pass-through entities that elected to pay tax at the entity level. The report attributes the growth in corporate contributions to federal and state changes: the federal limit on state and local tax deductions led Georgia to enact HB 149 in 2021, which allows owners of pass-through entities to pay state tax at the entity level, and the Department updated its rules so electing entities can cover up to 75 percent of their Georgia liability through this credit, which treats them like C corporations.
The election matters for the credit because a first half preapproval for an electing entity is not tied to a fixed dollar amount, only to 75 percent of liability. For an owner of a non-electing entity the first half limit is $25,000 no matter how large the entity is. A profitable S corporation with $2 million of Georgia income has an entity liability of roughly $100,000 at 4.99 percent, so the entity route can support a far larger gift than the owner route, at the price of the election itself and the loss of any pass through of the credit. The election is analyzed in the Georgia pass through entity tax election article, and it should be modelled before a hospital request is filed, since the hospital request cannot be redirected after the fact.
Two further points prevent errors. First, a pass-through entity that has no liability of its own may make the expenditure, but all of the credit forms, meaning preapproval, claiming, and reporting, are then filed in the names of its members, shareholders, or partners, and the credit can be applied only against those owners’ liabilities. The entity must give the hospital the information it needs to complete those forms. Second, credits earned by owners are based on their profit and loss percentages at the end of the year, so an ownership change during the year needs attention before the request is sized.
How Do C Corporations, Trusts, and Electing Entities Claim the Georgia Credit?
A C corporation, a fiduciary, an electing S corporation, or an electing partnership may claim the smaller of the amount given or 75 percent of its Georgia income tax liability. A preapproved amount above that limit cannot be claimed and cannot be carried forward, and a fiduciary cannot pass the credit through to its beneficiaries.
- The limit: the smaller of the actual amount given or 75 percent of Georgia income tax liability.
- Lost excess: any preapproved amount above the limit is neither claimable nor carried forward.
- Unused credit: a claimed but unused credit carries forward five years for the entity.
- No pass through: neither an electing entity nor a fiduciary can pass the credit to owners or beneficiaries.
The regulation’s example uses a corporation that requests preapproval on May 31 for a $100,000 gift, expecting a Georgia income tax liability of $150,000. The Department preapproves $100,000. The corporation gives $100,000. When it files, its actual liability is $80,000, so the credit is limited to $60,000, which is 75 percent of $80,000, and the extra $40,000 cannot be claimed or carried forward. The same result applies to an S corporation that has elected to pay at the entity level, with the added rule that any unused credit carries forward at the entity level but cannot be used by shareholders.
The exposure for a business is therefore an estimating error, and it is a larger one than for an individual, because the sizing depends on a forecast of Georgia liability that may not be knowable until the return is nearly done. A business with volatile income has a better argument for a request in the second half of the year, when more of the year is known, than in the first half. The credit is claimed against Georgia income tax under Chapter 7 of Title 48. The net worth tax is a separate tax, and an entity should not assume the credit offsets it. Our article on the Georgia net worth tax covers how that tax is computed, and the Georgia corporate tax rate article covers the rate that drives the liability figure.
Trusts have a further issue. The statute and regulation treat a fiduciary as its own taxpayer for this credit and bar passing the credit to beneficiaries. A trust that distributes most of its income and therefore has little Georgia liability of its own will find that 75 percent of a small number is small. Trustees weighing a gift should read the trust instrument alongside the credit, and our estate and trust planning page explains how the firm approaches fiduciary questions.
Is a Georgia Rural Hospital Gift Also a Federal Charitable Deduction?
Generally not for the credited amount. Under Treas. Reg. 1.170A-1(h)(3), a federal charitable deduction is reduced by any state or local tax credit the donor receives or expects to receive in consideration for the payment. Because this credit is 100 percent of the gift, the exception for credits of 15 percent or less does not help.
- The general rule: the deduction is reduced by the credit received or expected.
- It applies regardless of timing: the reduction occurs whether or not the credit is claimed in that year.
- The 15 percent exception: unavailable, because a 100 percent credit exceeds it.
- The effect for most donors: no federal charitable deduction for the credited amount.
The regulation’s first example describes a 70 percent state credit for a $1,000 payment and reduces the deduction by $700 regardless of whether the taxpayer is able to claim the credit in that year. The Auditor’s report notes the practical result for this program: since the 2019 federal rule, contributions from individuals no longer qualify as charitable deductions, and the report ties the low share of undesignated gifts to that change. The full derivation of the federal rule, and its effect on an itemizer, is set out once in our article on the Georgia qualified education expense credit, and this article applies it to the hospital credit rather than repeating it.
The federal deduction question is separate from the Georgia one. A donor who takes no federal charitable deduction for the credited amount has nothing to add back on the Georgia return under the add-back rule covered below. A donor who did deduct a charitable amount that is later credited has both a federal issue and a Georgia add-back to address, and the hospital’s letter of confirmation, which states the amount and the credit, is the record that ties the pieces together.
Can an Itemizer Treat the Gift as a State Tax Payment on Schedule A?
Yes, in many cases. Treas. Reg. 1.164-3(j) lets an itemizing individual treat the disallowed charitable portion as a payment of state or local tax, to the extent the credit offsets that year’s or the preceding year’s liability. It remains subject to the federal cap on state and local tax deductions.
- Who qualifies: an individual who itemizes and pays cash or a cash equivalent.
- When it counts: the year of payment, to the extent the credit offsets that year’s or the prior year’s Georgia tax.
- Carryforward credits: an excess credit carried forward may be treated as a tax payment in the year it is applied.
- The cap still applies: the safe harbor does not avoid the limit in IRC 164(b)(6).
The safe harbor appears in Treas. Reg. 1.164-3(j). The federal cap matters more now than it did before 2025. Under IRC 164(b)(7), the applicable limitation amount is $40,000 for 2025 and $40,400 for 2026, then 101 percent of the prior year amount through 2029, and $10,000 after 2029. For 2026 the limit is reduced by 30 percent of the amount by which modified adjusted gross income exceeds $505,000, but not below $10,000. A donor whose state and local taxes already exceed the applicable limit gets no additional federal benefit from treating the gift as state tax, because the deduction is already capped. A donor who does not itemize gets no federal effect at all.
A worked illustration shows the point. Suppose a married couple that itemizes owes $9,000 of Georgia tax, is preapproved for $9,000 in the second half of the year, and gives $9,000. The credit offsets the Georgia liability, so the couple pays nothing more to the state. The safe harbor lets them treat the $9,000 paid to the hospital as state tax paid, so their Schedule A shows the same state tax deduction it would have shown had they paid the state directly, still subject to the cap. If the couple already has $40,400 of other state and local tax, the gift changes nothing federally. If they have room under the cap, the treatment preserves a deduction that the general rule would have removed. The couple should confirm the numbers with the return preparer before giving, not after.
Can a Business Deduct the Gift for Federal Purposes?
A C corporation may treat a payment that earns a credit against its own state tax as an ordinary and necessary business expense to the extent of the credit, under Treas. Reg. 1.162-15(a)(3)(i). The pass-through safe harbor does not apply if the credit reduces a state income tax, so an electing entity relies on general facts.
- C corporations: a safe harbor treats the payment as a section 162 business expense to the extent of the credit.
- Specified pass-through entities: a similar safe harbor exists, but not when the credit reduces a state income tax.
- Electing Georgia entities: the credit reduces Georgia income tax, which is the excluded case.
- Cash only: the regulation defines a payment as cash or a cash equivalent.
The distinction is easy to miss. The Auditor’s report describes corporations and electing pass-through entities as able to claim a business expense deduction as well as the Georgia credit, and that is accurate for a C corporation. For an entity that pays Georgia income tax at the entity level, the specific safe harbor in Treas. Reg. 1.162-15(a)(3)(ii)(C) states that it does not apply if the credit reduces a State or local income tax, which describes the Georgia credit taken against an electing entity’s Georgia income tax. That does not mean the payment is nondeductible. It means the regulation does not supply the answer, and the treatment depends on the general rules and the facts, which should be documented before the return is prepared. Treat the Auditor’s description as background and the regulation as the authority.
A gift made by a pass-through entity that has no Georgia tax of its own, so that the credit is earned by the owners, raises a different reporting question, since the expenditure is the entity’s and the credit belongs to the owners. The entity return and the owner returns should be prepared together. Nothing in this article applies to a particular taxpayer, and the federal treatment of any specific gift depends on the entity type, the return being prepared, and the facts.
What Is the Georgia Add-Back for Charitable Deductions?
O.C.G.A. 48-7-29.20(g) provides that no credit is allowed for an amount deducted as a charitable contribution to a bona fide charitable organization. A taxpayer who took a federal deduction for an amount for which the Georgia credit is allowed must add that part of the deduction back to Georgia taxable income.
- The rule: no credit for an amount also deducted as a charitable contribution.
- The add-back: the federal deduction tied to the credit is added to Georgia taxable income.
- If nothing was deducted: when the federal charitable deduction was reduced to zero, there is nothing to add back.
- Limited itemizers: the regulation supplies a ratio formula for a taxpayer whose federal itemized deductions were limited.
The regulation’s formula multiplies the charitable contribution related to the credit by a fraction whose numerator is the itemized deductions subject to limitation that were actually allowed and whose denominator is the total of those deductions before the limitation. In its example, a taxpayer has a $2,500 contribution related to the credit and $1,500 of property taxes, both subject to limitation, plus $10,000 of investment interest that is not limited. The federal limitation leaves $3,000 of the $4,000 of limited deductions, so the add-back is $2,500 multiplied by $3,000 over $4,000, or $1,875. The example illustrates the method and is not a statement about any current federal limitation.
For most donors under the current federal rules the result is simple. The federal charitable deduction for the credited amount is removed by Treas. Reg. 1.170A-1(h)(3), the itemizer may claim the amount as state tax instead, and the Georgia return has nothing to add back. The add-back becomes a live issue when a preparer, or software, carries the hospital gift to Schedule A as a charitable contribution. That is the error the rule exists to catch, and a Georgia return that claims the credit while the federal return deducts the same dollars invites a notice.
How Do You Claim the Georgia Rural Hospital Credit on the Return?
Complete Form IT-QRHOE-TP2, the credit computation, with the Georgia return for the year of the gift, and keep the hospital’s Form IT-QRHOE-RHO1 letter of confirmation. An electronically filed Georgia return that includes the software’s electronic Form TP2 satisfies the filing requirement.
- The form: Form IT-QRHOE-TP2 computes the credit and goes with the return.
- The letter: the hospital issues Form IT-QRHOE-RHO1 within 30 days of the contribution.
- The record: the letter states the donor’s name, address, tax identification number, amount, date, and credit.
- The hospital’s duty: it reports the gift to the Department monthly, and the credit does not depend on the hospital’s own filings once the gift is confirmed.
The statute requires the letter of confirmation to contain the taxpayer’s name, address, tax identification number, the amount and date of the contribution, and the amount of the credit. The regulation requires the hospital to provide the letter within 30 days of the contribution and to file a monthly report, Form IT-QRHOE-RHO2, with the Department. It also provides that once the hospital confirms receipt of a preapproved donation, the donor receives the full benefit of the credit even if the hospital does not comply with its own reports and filings. That protection is useful, since the donor cannot control the hospital’s paperwork.
A donor who files a paper return, or whose software does not carry the form, should ask the preparer to attach Form TP2 and to keep the letter of confirmation with the workpapers. The Department’s credit page lists the forms, and the credit code on the return is 136. A return that omits the credit can be corrected by amendment, as described in our article on the Georgia amended tax return. Because the credit belongs to the year of the gift rather than the year the return is filed, a fiscal year filer should state on the preapproval request the tax year end of the return that will claim the credit.
What Happens to Unused Georgia Rural Hospital Credit?
A credit that is claimed but not used in the year of the gift may be applied against the succeeding five years of Georgia tax, and it cannot be applied to prior years. Any amount above the taxpayer’s limit for the year is not eligible for carryforward. Credits that go unclaimed for the full period expire.
- Five years: the carryforward period in the statute and the regulation.
- No carryback: the credit cannot be used against prior year liability.
- Excess is lost: amounts above the limits in paragraph (4) of the regulation are not carried forward or reassigned.
- Expired credit exists: the Auditor identified $1.5 million of credits approved in 2018 that remained unclaimed and expired.
The Auditor’s 2025 report shows how much credit sits unused. In tax year 2023, $91.5 million of rural hospital credit was available to taxpayers, made up of $72.5 million approved that year and the rest carried from earlier years. Taxpayers claimed $44.2 million, and $45.8 million, about 50 percent, carries forward to later years. The report presents the carried forward balance as increasing each year: the amount remaining was $7.9 million for 2018 and $45.8 million for 2023. The pattern suggests that many donors give more than their current Georgia liability can absorb, and the carryforward is what keeps those gifts from being wasted.
| Tax year | Credit available | Credit used | Remaining |
|---|---|---|---|
| 2020 | $64,163,677 | $50,891,755 | $13,271,922 |
| 2021 | $72,760,070 | $58,652,014 | $14,108,056 |
| 2022 | $71,894,793 | $52,904,983 | $18,989,810 |
| 2023 | $91,523,299 | $44,221,180 | $45,776,210 |
The takeaway for a donor is that a credit is not worth its face amount if it cannot be used for years. A donor with a small Georgia liability who gives $10,000 in the second half of the year, when no dollar limit applies, may claim only a fraction of it on the current return, carry the rest for up to five years, and then see any unused remainder expire. The order in which credits are applied, and the other Georgia credits that compete for the same liability, should be planned before the gift, not after. A donor who does not expect to use the credit within five years is better advised to give less, or to give in a year in which income is higher.
Is Georgia Reviewing Excess Rural Hospital Credit Claims?
Yes. The Auditor found that the Department did not originally check whether corporations and pass-through owners had the liability their credits required, and the Department finalized an adjustment process in February 2025. It runs an annual query each third quarter, so the query for 2024 returns was scheduled for the third quarter of 2026.
- The finding: taxpayers could and did receive higher credits than their tax liability supported.
- The process: a query run each third quarter, after the returns for the prior year are received.
- The timing: the 2024 query was scheduled for the third quarter of 2026, which is now.
- The limit on the Department: a generally applicable three year statute of limitations to adjust returns.
The Auditor’s report states that excess credits claimed by corporations on tax year 2022 returns had not yet been adjusted when it was written, that staff expected to complete adjustments in April 2025, and that the Department had until April or October 2026, three years after the 2022 filing deadlines, to make them. The report also notes that approximately $335,000 in contribution discrepancies over the period represented about 0.1 percent of the nearly $351 million of credits approved. The scale of the problem is small, but the direction is clear, since an entity or owner that claimed more than 75 percent of liability, or more than the tax actually paid on selected income, is now exposed to adjustment.
A taxpayer who claimed the credit should keep a one page computation with the return: the preapproval notice and certificate number, the letter of confirmation, the liability figure, the 75 percent computation for an entity, or the selected entities and the marginal rate for an owner, and the resulting credit. A taxpayer who finds that a prior return claimed too much should consider an amended return rather than waiting for a notice, and the process is described in our Georgia amended tax return article. Under the regulation, a credit found not to satisfy the statute is disallowed and tax and interest are due on the disallowed credit.
How Does the Credit Affect Georgia Withholding and Estimated Payments?
The credit lowers the Georgia tax that a donor must eventually pay, so a donor who has been approved and has paid the hospital can reduce estimated tax payments accordingly. Georgia HEART suggests dividing the amount given by four and reducing each quarterly payment by that fraction. The reduction should follow the gift, not precede it.
- The idea: money redirected to the hospital need not also be sent to the state through estimates.
- HEART’s method: divide the gift by four and reduce each of the four installments.
- The caution: reduce payments only for an approved and paid amount, and only up to the tax the credit will actually offset.
- Withholding: an employee may be able to adjust withholding with a new Form G-4 if the credit will be large.
The Georgia HEART FAQ gives an example. A taxpayer who expects to owe $10,000 of Georgia tax gives $1,200 to a hospital in March and would ordinarily pay $2,500 on each of four due dates. Because $1,200 is redirected to the hospital, each installment can be reduced by $300, to $2,200. That is a reasonable approach for a donor whose credit will fully offset the reduction. It is not safe for a donor who reduces installments on a preapproval that has not been paid, whose credit exceeds liability, or whose liability was forecast from income that did not arrive.
Georgia penalizes underpayment of estimated tax, and the underpayment rules are covered in our guide to Georgia Form 500 ES estimated tax and computed in the Georgia estimated tax penalty calculator. A donor whose gift is made late in the year, for instance in November under a preapproval issued after September 30, cannot reduce the earlier installments after the fact. For that donor the credit reduces the balance due on the return and does not help the installments that were already due, so the donor should model both before deciding how much to give.
Can a Nonresident or Part-Year Resident Use the Georgia Rural Hospital Credit?
A credit can reduce only Georgia income tax, so a nonresident or part-year resident can use it only against the Georgia tax on the Georgia return. The limits are then measured against Georgia income tax actually owed. Georgia HEART tells non-residents to consult a tax advisor, because it says the credit involves complexities for filers from other states.
- The offset: the credit can reduce only the Georgia tax on a Georgia return.
- A small base: a nonresident with modest Georgia income has little Georgia tax to offset.
- The pass-through rule: the owner limit applies to Georgia income only, at the Georgia rate.
- Other-state effects: the federal treatment is unchanged, and the home state may have its own rules.
The HEART FAQ warns that its accounting firm confirmed that there are complexities for tax filers from other states taking the credit, even when they work in Georgia and pay Georgia income tax. The statutory design explains the caution. The credit is a credit against Georgia tax, so a taxpayer with Georgia income taxed on a nonresident return, such as a Florida resident with Georgia rental income or a Georgia partnership interest, may be able to use it, but only up to the Georgia tax owed. A taxpayer with a part-year Georgia return, described in our article on the Georgia part year resident tax return, is in the same position.
A person who moved out of Georgia during the year should also consider timing. A gift made after the move, when the taxpayer no longer has a Georgia liability that will absorb the credit, may produce a credit that can only be carried forward against later Georgia tax. Our overview of the nonresident state tax return rules covers how the filing obligation is determined. In this respect the hospital credit is like any other Georgia credit: its value depends on the Georgia return on which it will be used.
Georgia Rural Hospital Tax Credit Example: Four Donors
The four hypothetical donors below show how the same rules produce different results. Each is computed at Georgia’s 4.99 percent flat rate for 2026, and each assumes the gift is preapproved and paid by the deadline. The examples are illustrations of the mechanics and are not predictions about any taxpayer.
- Donor A: a single filer with a modest Georgia bill, who gives within the first half limit.
- Donor B: a married couple with a larger Georgia bill, who gives after July 1.
- Donor C: an S corporation owner who oversizes the request.
- Donor D: a C corporation whose liability comes in below forecast.
| Donor A | Donor B | Donor C | Donor D | |
|---|---|---|---|---|
| Taxpayer | Single filer | Married filing jointly, itemizers | S corporation owner, not electing | C corporation |
| Georgia tax before the credit | $6,000 | $9,000 | $14,970 on $300,000 of selected income, assuming no other Georgia income | $80,000 |
| Gift preapproved and paid | $5,000 (first half limit) | $9,000 (after July 1) | $25,000 (owner limit) | $100,000 |
| Limit that applies | $5,000 | Georgia liability of $9,000 | Tax actually paid, $14,970 | 75 percent of $80,000, or $60,000 |
| Georgia credit allowed | $5,000 | $9,000 | $14,970 | $60,000 |
| Preapproved amount lost | $0 | $0 | $10,030 | $40,000 |
| Georgia tax still paid to the state | $1,000 | $0 | $0 | $20,000 |
| Federal treatment of the gift | No charitable deduction for the credited amount | Treated as state tax if itemizing, subject to the SALT cap | Depends on how the gift is reported and the return | Business expense safe harbor to the extent of the credit |
In each column the donor’s total outlay to the hospital and the state is the same as it would have been without the gift, except where the request was larger than the limit supports. Donor A pays $5,000 to the hospital and $1,000 to Georgia instead of $6,000 to Georgia. Donor B pays $9,000 to the hospital and nothing to Georgia. Donor C gives $25,000 but can claim only $14,970, so $10,030 is a gift that earned no credit. Donor D gives $100,000 but is limited to $60,000, so $40,000 earned no credit, and Donor D still owes $20,000 to the state.
Donors C and D show the one place where the choice of approach changes the result, and it is the size of the request. Both were preapproved for more than the return could support, because the preapproval is based on the taxpayer’s own estimate and the Department does not test it at that stage. A request built from a written estimate of Georgia liability, with a margin for income that may fall short, avoids a gift that earns no credit. Where a business owner is not sure which route to take, the answer should come from a comparison of the owner route and the entity route on the same set of facts.
How Is the Rural Hospital Credit Different From the Education Credit and Other Georgia Credits?
The rural hospital credit and the student scholarship credit are separate programs with separate statutes, separate caps, and separate limits. The Georgia HEART program states that a donor who contributes to a scholarship organization may also contribute to a rural hospital, and the differences below explain why one is easy to plan and the other is a race.
- Different statutes: O.C.G.A. 48-7-29.20 for hospitals and 48-7-29.16 for scholarships.
- Different allocation: request by request for hospitals, one opening day queue with proration for scholarships.
- Different limits: higher individual limits for hospitals, and a $150 million scholarship cap against $100 million here.
- A shared federal rule: both credits reduce the federal charitable deduction under Reg. 1.170A-1(h)(3).
| Feature | Rural hospital credit | Education expense credit |
|---|---|---|
| Statute | O.C.G.A. 48-7-29.20 (through December 31, 2029) | O.C.G.A. 48-7-29.16 |
| Recipient | Approved rural hospital organization | Student scholarship organization |
| Credit per dollar given | 100 percent | 100 percent |
| Individual limit | $5,000 single, $10,000 joint through June 30; none after July 1 | $2,500 single, $5,000 joint |
| Pass-through owner limit | $25,000 through June 30, limited to tax paid | $25,000, limited to tax paid |
| Statewide cap | $100 million, about 54 percent preapproved on September 17, 2026 | $150 million under HB 328, fully preapproved on January 3, 2026 under the prior $120 million cap |
| How it is allocated | First come, first served, no proration by date | First come, first served with proration |
| Payment deadline | Earlier of 180 days or October 31 if preapproved by September 30; December 31 after | 60 days from notice, same calendar year |
| Carryforward | Five years | Three years for tax years beginning on or after January 1, 2025 |
The table shows why a donor may want both credits, and why the second is a matter of planning rather than of speed. The two credits are each limited by the same Georgia liability, so a donor who gives to both should confirm how the credits are ordered against that liability and not treat each as a separate allowance. The education credit is explained in our article on the Georgia qualified education expense credit, and the Georgia 529 deduction, which is a deduction and not a credit, is covered in the Georgia 529 plan tax deduction article. At a 4.99 percent flat rate a deduction saves about five cents per dollar, while a credit saves a full dollar of Georgia tax per approved dollar, which is why these are compared as credits and not as deductions.
Where Does the Money Go, and Who Reviews It?
Hospitals must use the contributions for health care related purposes, including capital expenditures that support care. Each hospital reports to the Department of Community Health each year, and the Department of Audits and Accounts audits the whole program annually, including the contributions, the credits, and any fees paid to third parties.
- Permitted uses: health care services and capital expenditures that facilitate them.
- Annual audit: the Department of Audits and Accounts audits the program every year by statute.
- Reported spending: hospitals reported spending $70.5 million in 2023 and holding $42.0 million unspent.
- The fee cap: third party fees may not exceed 3 percent of contributions.
The Auditor’s 2025 report says most funds went to capital expenditures or regular operating expenses in 2023, and that hospitals are not required to spend contributions within a specific period, so funds are often set aside for capital projects, equipment, and the recruitment of medical professionals. It also found that the fees Georgia HEART received in tax year 2023 totaled $2.17 million and did not exceed the statutory limit of 3 percent. The report describes the credit administration as largely consistent with the statute, with recommendations on reporting accuracy.
For a donor, the point of these facts is that the credit is not a payment to a program that the state runs. It is a gift to a specific hospital, chosen by the donor, and the hospital decides how to use it within the statute. A donor with a business relationship or a personal connection to a community has a natural reason to designate. A donor with none can leave the gift undesignated, and it goes to the hospital with the greatest financial need that is still below its limit, with the same credit.
What Are the Most Common Georgia Rural Hospital Tax Credit Mistakes?
The recurring mistakes are paying before or without preapproval, missing the payment deadline, sizing an owner or entity request from the limit instead of from tax, filing for a hospital not yet on the list, reducing estimated payments before the gift is paid, and carrying the gift to Schedule A as a charitable deduction.
- No preapproval: a gift made without an approved request earns no credit.
- Missed deadline: the unpaid amount is lost and cannot be carried forward.
- Oversized request: excess owner or entity preapprovals are neither claimable nor carried forward.
- Unlisted hospital: the Department denies the request and a new one must be filed.
- Double counting: the credited amount is not also a federal charitable deduction.
Three further mistakes are specific to 2026. The first is assuming the credit follows the education credit’s January race, which leads a donor to file in the first hour of the year and to give in January, when a later, better informed request would have served the donor better. The second is treating the September 30 date as unimportant, when it changes the deadline from December 31 to as early as October 31. The third is relying on a page that still quotes the $10,000 owner limit, the $75 million cap, or the 180 day rule without the October 31 fixed date, all of which changed for 2025.
Georgia Rural Hospital Tax Credit Help in Naples & Southwest Florida
Tax Expert Today LLC works from Naples, Florida and handles state tax matters nationwide, including Georgia credit planning, sizing preapproval requests against Georgia liability, owner limit computations, pass-through election trade-offs, and the federal treatment of the gift. Georgia clients are served from the Naples office and do not need to visit Georgia or Florida.
- Georgia tax credit help Naples covers residents, part-year residents, and business owners with Georgia income.
- Southwest Florida owners of Georgia businesses often weigh the owner route against an entity level election.
- Request sizing ties the preapproval amount to a documented estimate rather than the largest figure a form accepts.
- Remote engagement is standard. Documents are exchanged through a secure client portal rather than by email.
Tax Expert Today LLC
11983 Tamiami Trail N, Naples, FL 34110
Telephone: (239) 441-2005
Hours: Monday through Friday, 10:00 a.m. to 5:00 p.m. Eastern Time
A local question we are asked often: I live in Naples and own an interest in a Georgia partnership that pays me Georgia income. Can I use the Georgia rural hospital credit? Possibly, if you will have Georgia income tax to offset. As a Florida resident you would file a Georgia nonresident return, and the credit can reduce only the Georgia tax on that return. If the partnership elects to pay Georgia tax at the entity level, that income drops out of your base, and the entity route is different. The request should be sized to the Georgia tax actually paid on the income you select, before the gift is made. The full range of Georgia engagements is described on our Georgia tax services page, and planning for Southwest Florida residents is covered on our Naples tax planning services page.
When to Engage a Professional
A household with a steady Georgia tax bill and no pass-through income can usually handle this credit through a hospital’s or Georgia HEART’s application. Review is worth it for business owners choosing between the owner route and an entity election, for corporations sizing a request, for itemizers near the federal cap, and for anyone who moved states.
- An owner in several pass-through entities deciding which to select for the $25,000 limit.
- An S corporation or partnership weighing the Georgia pass-through entity election against the owner route.
- A C corporation or trust estimating Georgia liability for a request that cannot be corrected later.
- An itemizer near the SALT cap whose federal result depends on the state tax safe harbor.
- A taxpayer who claimed the credit before and wants the computation reviewed before the Department’s excess credit query reaches the return.
Dr. Pellumb Kabashi is an enrolled agent and the founder of Tax Expert Today LLC, and the firm includes tax advisors, enrolled agents, certified public accountants, and attorneys. Georgia Department of Revenue matters are state tax matters rather than federal ones, and they are handled under Georgia procedure and Georgia authority. Nothing in this article is advice for a particular taxpayer, and the result in any specific case depends on facts that a general article cannot know. Households and business owners who want a complete Georgia plan rather than a single credit can start with our Georgia tax planning and business advisory page. Call (239) 441-2005 for a free consultation, or reach the Naples, Florida office during business hours.
Frequently Asked Questions
What is the Georgia rural hospital tax credit?
It is a Georgia income tax credit under O.C.G.A. 48-7-29.20 for a preapproved cash gift to a rural hospital organization approved by the Department of Community Health. The credit equals 100 percent of the gift, subject to limits by taxpayer type, a hospital limit, and a statewide cap.
How much can I contribute for the Georgia rural hospital tax credit?
From January 1 through June 30 the limits are $5,000 for a single filer or a married person filing separately, $10,000 for a joint return, and $25,000 for a pass-through owner. After July 1 the dollar limits fall away for individuals, but the credit is still limited by Georgia income tax liability.
What is the Georgia rural hospital tax credit cap for 2026?
The 2026 cap is $100 million. The Department of Revenue reported on September 17, 2026 that $53,974,527 had been preapproved and $46,025,473 remained. No single hospital may receive more than $4 million of preapproved credits in a calendar year.
What is the deadline to pay after preapproval?
A donor preapproved on or before September 30 must pay within 180 days of the notice but no later than October 31. A donor preapproved after September 30 must pay on or before December 31. October 31, 2026 falls on a Saturday, so plan to pay earlier.
What happens if I am preapproved but do not donate?
The credit is lost for the amount not paid. It cannot be claimed or carried forward, and the Department returns the uncontributed amount to the pool available to other donors. A donor who reapplies later receives no priority over other applicants.
Can I deduct the donation on my federal return?
Generally not as a charitable deduction, because Treas. Reg. 1.170A-1(h)(3) reduces the deduction by the state credit. An itemizing individual may instead treat the credited amount as state tax paid under Treas. Reg. 1.164-3(j), subject to the federal cap on state and local taxes.
Can I choose which hospital receives my donation?
Yes, among the hospitals on the Department of Community Health list, until a hospital reaches its $4 million limit. An undesignated gift goes to the listed hospital with the highest financial need that has not reached its limit. The credit is denied if the gift is designated for a particular individual.
Does the Georgia rural hospital credit carry forward?
Yes. A credit claimed but not used in the year of the gift may be applied against the succeeding five years of Georgia tax. Any preapproved amount above the taxpayer’s limit cannot be claimed or carried forward, and the credit cannot be applied to prior years.
Is the Georgia rural hospital credit better than the education expense credit?
Neither replaces the other. They are separate programs with separate statutes, caps, and limits, and the Georgia HEART program states that a donor may use both. The rural hospital cap has not been fully used in recent years, while the education cap has been exhausted in early January.
How do I claim the Georgia rural hospital tax credit?
Complete Form IT-QRHOE-TP2 with the Georgia return for the year of the gift and keep the hospital’s Form IT-QRHOE-RHO1 letter of confirmation. An electronically filed return that includes the software’s version of Form TP2 satisfies the filing requirement.
Published September 23, 2026 by Dr. Pellumb Kabashi « Back to Learning Center
Have a question this article touches on?
Tax Expert Today LLC, based in Naples, Florida and serving clients across the United States.
Schedule a Consultation (239) 441-2005